Indian Stock Market Today: Nifty Falls 0.34% as Smallcaps Slide 2.37%
Quick Summary
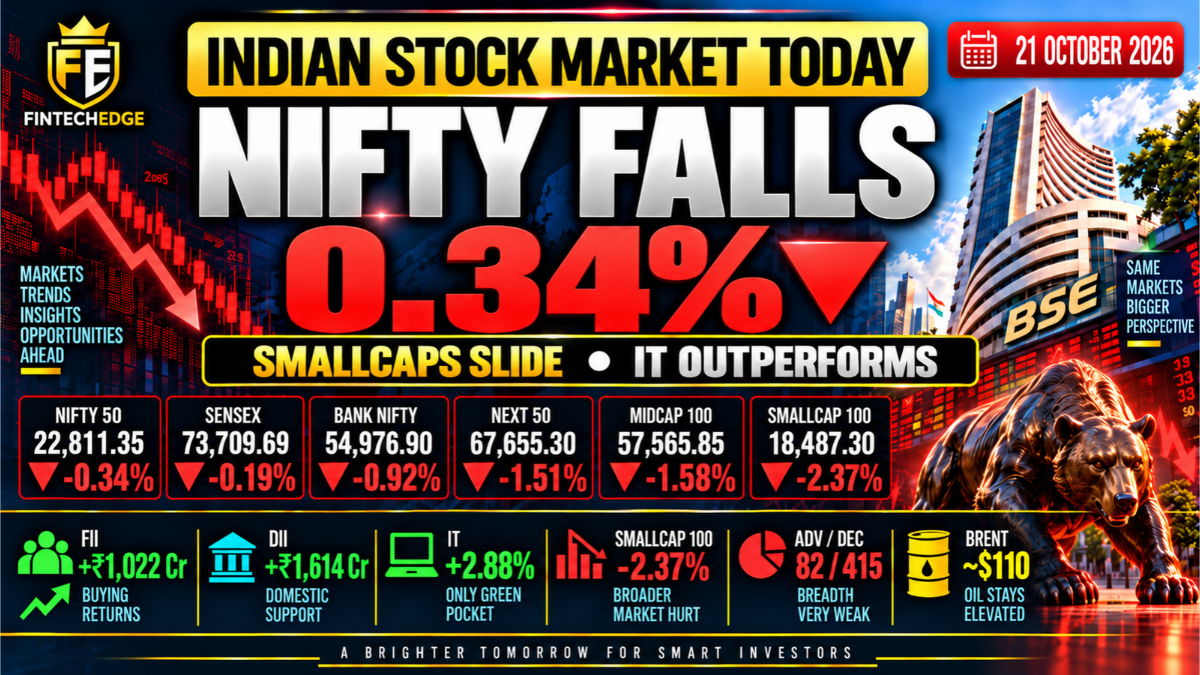
- Nifty 50 fell 0.34% to 22,811.35, while Sensex declined 0.19% to 73,709.69.
- Broader-market weakness was much sharper, with Next 50 down 1.51%, Midcap 100 down 1.58%, and Smallcap 100 down 2.37%.
- Bank Nifty fell 0.92%, showing continued pressure in financial stocks.
- Nifty IT gained about 2.9%, remaining the clearest pocket of strength.
- Brent crude moved back above $110 per barrel, keeping macro pressure elevated.
- FIIs bought ₹1,022 crore, while DIIs bought ₹1,614 crore in the stock segment.
- Jio Platforms’ IPO drew strong demand, while the rupee strengthened to around ₹94.46 per dollar.
Indian Market Performance — 21 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian equities ended lower on 21 October 2026, but the relatively small decline in the headline indices understated the weakness across the broader market.
The Nifty 50 fell 0.34% to 22,811.35, while the Sensex declined 0.19% to 73,709.69. Bank Nifty lost 0.92%, but the pressure became much more pronounced outside the large-cap benchmarks: the Nifty Next 50 fell 1.51%, the Midcap 100 declined 1.58%, and the Smallcap 100 dropped 2.37%. Pasted text
IT was the major exception, extending its recent earnings-led strength even as financials, autos and metals weakened. Brent crude moved back above $110 per barrel, adding to India’s macro pressure, while the Jio Platforms IPO attracted exceptionally strong demand.
One of the more unusual features of the day was institutional activity: both FIIs and DIIs were net buyers, even though most of the market finished lower.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,811.35 | -0.34% |
| Sensex | 73,709.69 | -0.19% |
| Bank Nifty | 54,976.90 | -0.92% |
| Nifty Next 50 | 67,655.30 | -1.51% |
| Nifty Midcap 100 | 57,565.85 | -1.58% |
| Nifty Smallcap 100 | 18,487.30 | -2.37% |
The headline benchmarks suggest only a modest negative session.
The broader-market data tell a very different story.
The Smallcap 100 lost more than seven times as much as the Nifty in percentage terms, while both the Midcap 100 and Next 50 declined more than 1.5%.
That divergence is the most important feature of today’s market.
Smallcaps and Midcaps Lead the Sell-Off
The weakness beneath the benchmarks was far more significant than the 0.34% decline in the Nifty suggests.
Smallcaps were the hardest hit, with the Nifty Smallcap 100 dropping 2.37%. The Midcap 100 fell 1.58%, while the Next 50 declined 1.51%.
This matters because the Nifty and Sensex are dominated by a relatively small group of large companies.
When heavyweight stocks hold up—or when one large sector such as IT performs strongly—the headline indices can appear relatively stable even while a large number of stocks are falling.
That was the pattern today.
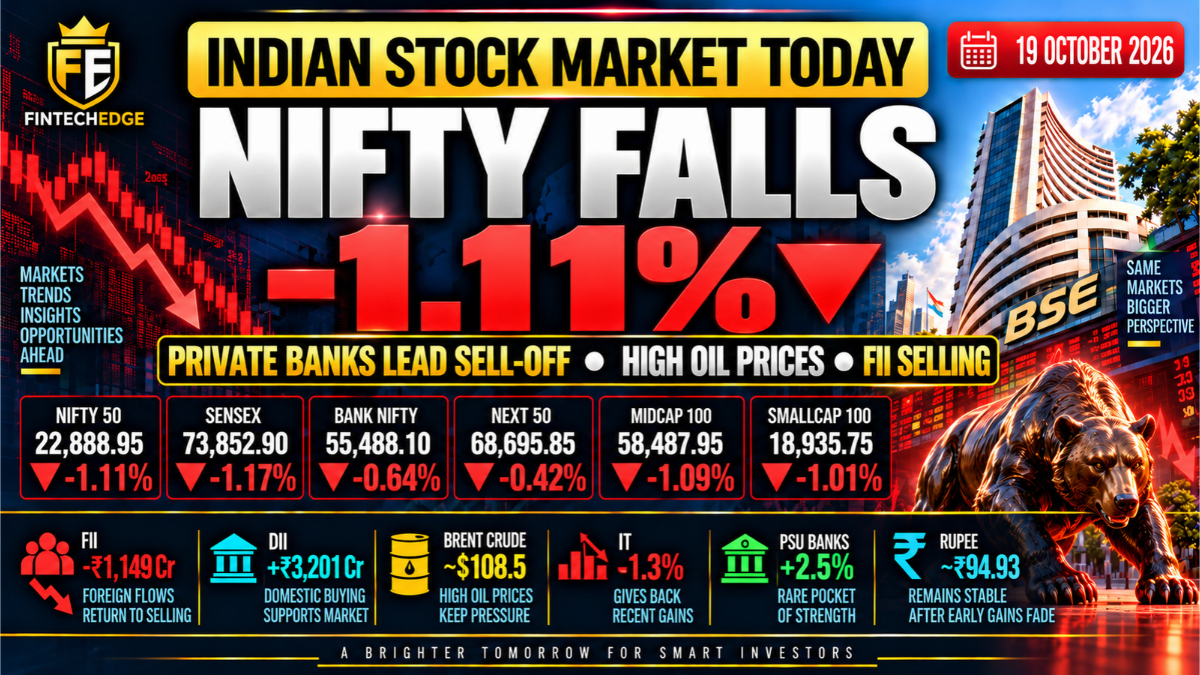
It also extends the broader-market deterioration visible in the 19 October session, when midcaps and smallcaps had already fallen around 1%.
Today that pressure intensified.
For retail investors, this distinction is important. A portfolio tilted toward small- and mid-cap stocks could have experienced a much more difficult session than the headline Nifty number implies.
That does not, by itself, predict what comes next.
But it does tell us that market participation weakened significantly outside the largest stocks.
IT Remains a Bright Spot
IT continued to stand out against the rest of the market.
The Nifty IT index gained about 2.9%, extending the earnings-driven rebound that began earlier in October.
L&T Technology Services was among the strongest individual performers, surging after strong quarterly results, while large IT names such as TCS, HCLTech, Infosys and Tech Mahindra continued to show relative strength.
This matters because IT companies carry substantial weight in the Nifty and Sensex.
Their gains helped offset weakness elsewhere and partly explain why the headline indices declined much less than midcaps and smallcaps.
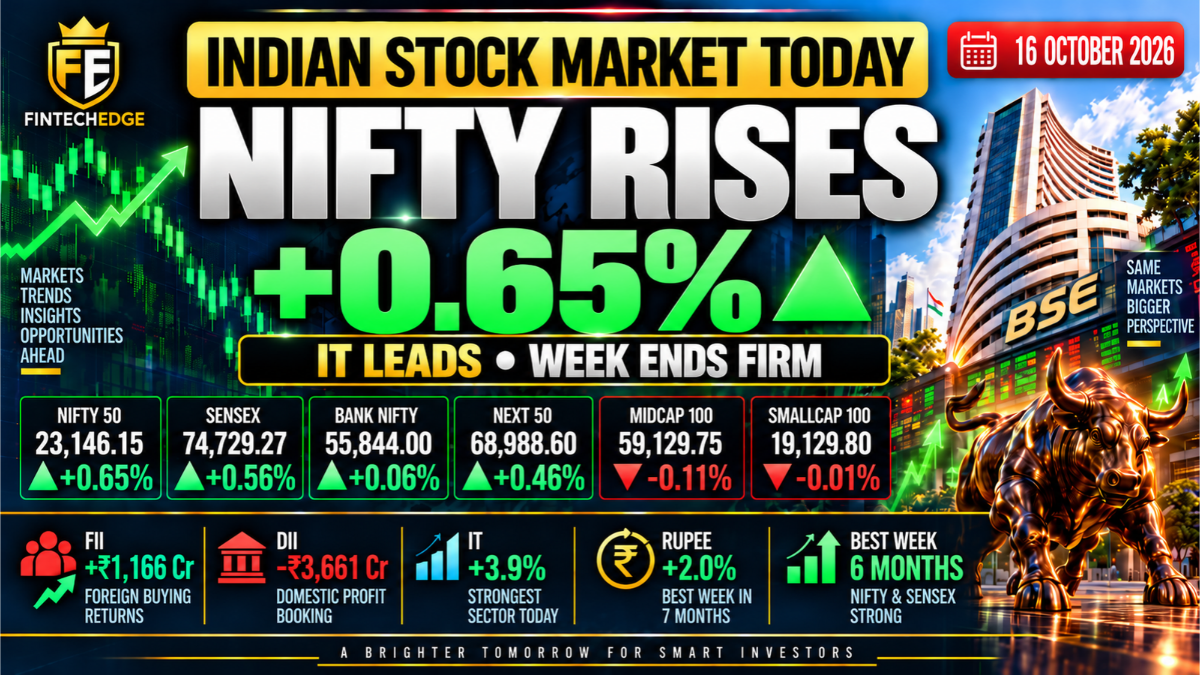
The contrast is particularly striking when compared with 16 October, when IT led the Nifty to its best week in six months.
Still, the recent strength should not be overstated.
The data show that IT remains a relative outperformer after encouraging company results. They do not prove that the sector has permanently bottomed or that it will continue outperforming indefinitely.
Oil Above $110 Keeps Macro Pressure High
Crude oil again became an important part of the domestic market backdrop.
Brent moved back above $110 per barrel.
For India, that matters through several channels.
Higher oil can increase pressure on:
- inflation;
- the import bill;
- the current account deficit;
- the rupee;
- interest-rate expectations;
- and company margins.
India imports a substantial share of its crude requirements, which means oil shocks have broader consequences than they would for a major energy exporter.
The impact is particularly relevant now because domestic financial conditions have already tightened and global yields remain elevated.
It would be too simplistic to say oil caused today’s sell-off.
The market was also dealing with weak financial stocks, falling midcaps and smallcaps, and continued caution across global risk assets.
But oil above $110 remains one of the clearest macro risks facing Indian equities.
FIIs and DIIs Both Buy Despite Weak Market
One of the most interesting contradictions of the session came from institutional flows.
Your 21 October stock-segment data showed:
- FII: +₹1,022 crore
- DII: +₹1,614 crore
Both foreign and domestic institutions were therefore net buyers.
That differs sharply from the pattern seen on many recent sessions, when foreign selling was offset by domestic institutional buying.
It also means the transcript’s claim that FII selling continued today should not be used.
The actual daily data show the opposite.
Still, one day of FII buying should be kept in context.
October cumulative foreign flows remain deeply negative, so today’s buying does not establish that overseas investors have decisively returned to India.
What is more interesting is that institutional buying from both groups was not enough to prevent a sharp broader-market decline.
That suggests weakness was coming from other parts of the market as well, including smaller stocks and non-institutional participation.
Bank Nifty Falls Nearly 1%
Financial stocks remained under pressure.
Bank Nifty fell 0.92%, considerably more than the Nifty’s 0.34% decline.
Banks are among the largest components of the headline indices, so weakness in the sector normally creates significant downward pressure.
Today, IT strength helped offset part of that drag.
This is another reason the Nifty’s relatively small decline should not be read as evidence that conditions were broadly stable.
Underneath the benchmark, financials were weak and several other sectors faced much heavier selling.
Jio Platforms IPO Draws Strong Demand
The Jio Platforms IPO was one of the biggest corporate-market events of the day.
The $3.2 billion offering was fully subscribed within two hours, with demand eventually exceeding the shares available.
That is a significant demonstration of investor appetite for a large, high-profile issue.
But there is an important contrast.
Strong IPO demand did not translate into strong performance across the broader equity market.
Midcaps and smallcaps still fell sharply.
That means it would be incorrect to treat the IPO response as proof that overall market sentiment was bullish.
It would also be speculative to say the IPO itself drained liquidity from the secondary market.
The safer conclusion is simply:
Jio Platforms attracted exceptional demand even as the broader market remained weak.
Rupee Strengthens on IPO-Linked Inflows
The rupee was one of the more positive macro developments.
It strengthened around 0.5% to ₹94.46 per dollar, helped by foreign inflows associated with the Jio Platforms IPO.
That provided some support at a time when crude oil was moving higher.
A stronger rupee can reduce pressure from:
- imported inflation;
- energy imports;
- overseas financing;
- and foreign investor currency risk.
But high crude limits how much relief currency strength can provide.
The rupee’s move should also be viewed as partly event-driven because of IPO-related inflows.
It does not necessarily mean the broader currency trend has permanently changed.
Global AI Sentiment Remains Volatile
The global technology backdrop remains complicated.
Recent sessions have seen heavy pressure in semiconductor and AI-related stocks, but that does not mean the AI trade has definitively broken.
Earnings continue to generate sharp moves in both directions.
That is an important distinction because the transcript frames the global AI trade as if it has already ended.
The evidence supports a more cautious conclusion:
global AI-linked stocks remain volatile and increasingly selective, rather than clearly entering a permanent decline.
For Indian IT, company-specific earnings have been more important than broad global technology sentiment in recent sessions.
Domestic Macro Data Remains Supportive
India’s September infrastructure output rose 7.9% year-on-year, providing a more constructive domestic macro signal.
That does not override today’s market weakness, but it is worth noting because financial markets and economic activity do not always move together over short periods.
The stock market can remain under pressure from valuation, liquidity, oil and global factors even when parts of the domestic economy are showing healthy growth.
What to Watch Next
Broader-market breadth
The biggest question is whether smallcap and midcap weakness continues. Another sharp underperformance would keep the divergence between the headline indices and the broader market in focus.
Brent crude
Oil above $110 remains one of the most important macro variables for India.
IT
IT remains the clearest relative winner. Continued earnings support could keep the sector resilient even if the broader market remains weak.
Bank Nifty
Banks fell almost 1% today. Stabilisation in financials would reduce an important source of pressure on the benchmarks.
FII flows
FIIs were net buyers today despite weak market performance. Whether that buying continues will be more meaningful than a single session.
Jio Platforms IPO
Investor demand has been strong. Attention now shifts to how the issue progresses and eventually lists.
Rupee
IPO-linked inflows helped the currency strengthen, but elevated oil remains a counterweight.
FintechEdge View
The Indian stock market today is another example of why the Nifty alone can give an incomplete picture.
The headline index fell only 0.34%, but Smallcap 100 dropped 2.37%, Midcap 100 lost 1.58%, and Next 50 fell 1.51%.
That is not a mild market decline beneath the surface.
IT was strong enough to cushion the benchmarks, while the Jio Platforms IPO attracted substantial demand and both FIIs and DIIs were net buyers.
Yet broader-market selling remained intense.
The key takeaway is therefore not simply that the Nifty fell.
It is that market breadth weakened sharply even while IT, institutional buying and IPO demand provided pockets of strength.
That divergence is the most important signal to carry into the next session.
Sources & References
- Indian shares fall as broader markets weaken while IT gains Reuters
- Jio Platforms IPO draws strong demand after opening for public bids Reuters
- Jio IPO-linked inflows support the rupee despite high oil prices Reuters
- India infrastructure output rises 7.9% in September Reuters
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.