Indian Stock Market Today: Nifty Rises 0.63% as Smallcaps Jump 2%
Quick Summary
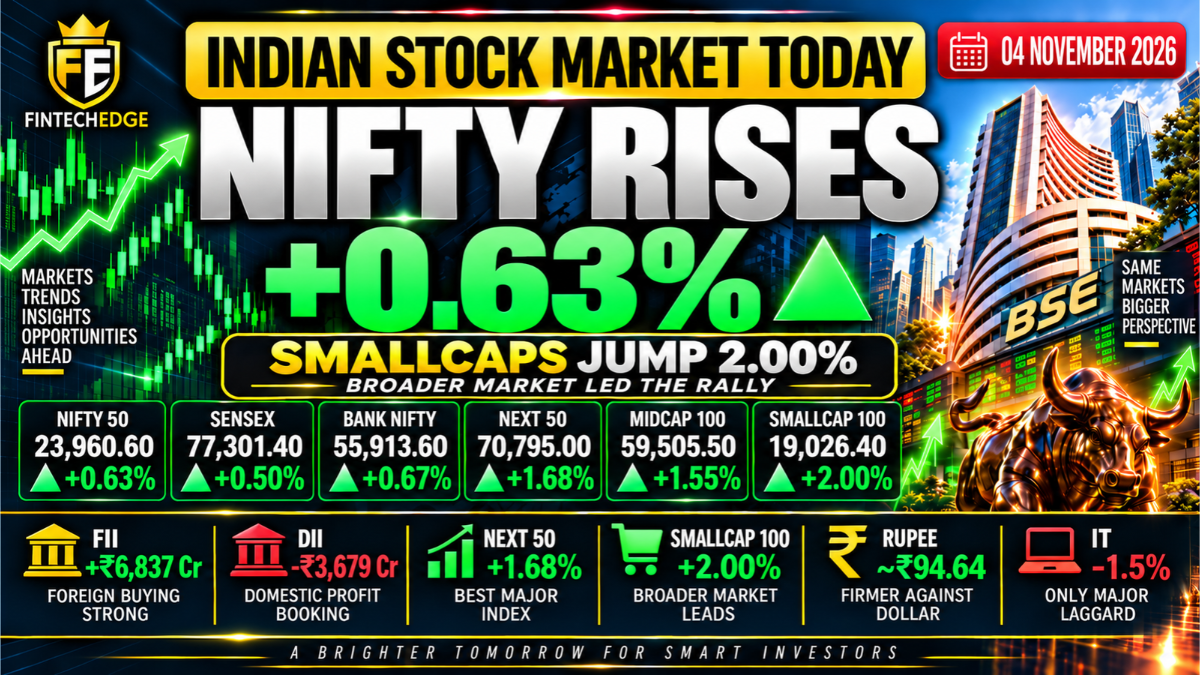
- Nifty 50 rose 0.63% to 23,960.60, while Sensex gained 0.50% to 77,301.40.
- The benchmarks extended their winning streak to five consecutive sessions, the longest run in nearly five months.
- Broader markets led the session, with Smallcap 100 up 2.00%, Next 50 up 1.68%, and Midcap 100 up 1.55%.
- Bank Nifty gained 0.67%, participating in the rally but lagging the broader-market indices.
- Brent crude eased toward $102 per barrel, providing relief for India’s inflation, currency and external-balance outlook.
- IT was the main weak pocket, falling around 1.5%, while media, metals and realty outperformed.
- The rupee strengthened further to around ₹94.64 per dollar.
Indian Market Performance — 4 November 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian stock market today extended its rally on 4 November 2026, with the Nifty 50 rising 0.63% to 23,960.60 and the Sensex gaining 0.50% to 77,301.40. The bigger story, however, was beneath the headline indices: the Nifty Smallcap 100 jumped 2.00%, the Midcap 100 gained 1.55%, and the Next 50 advanced 1.68% as broader-market participation improved sharply.
The session also extended the benchmark winning streak to five consecutive trading days, the longest run in nearly five months. Over those five sessions, the Nifty and Sensex have gained roughly 5.6%. Lower crude oil, a stronger rupee and improving expectations around foreign portfolio flows added support, while IT remained the main weak pocket.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 23,960.60 | +0.63% |
| Sensex | 77,301.40 | +0.50% |
| Bank Nifty | 55,913.60 | +0.67% |
| Nifty Next 50 | 70,795.00 | +1.68% |
| Nifty Midcap 100 | 59,505.50 | +1.55% |
| Nifty Smallcap 100 | 19,026.40 | +2.00% |
All six major indices tracked by FintechEdge finished higher, but the scale of the gains was very different.
Unlike 3 November, when large caps led while smallcaps gained only 0.31%, today the leadership shifted decisively toward the broader market.
That change in participation is the most important feature of the session.
Nifty Extends Winning Streak to Five Sessions
The Nifty and Sensex have now advanced for five consecutive sessions, marking their longest winning streak in nearly five months.
Over this period, the benchmarks have gained roughly 5.6%, taking them materially higher from late-October levels.
The pace of the rally moderated today compared with the previous two sessions:
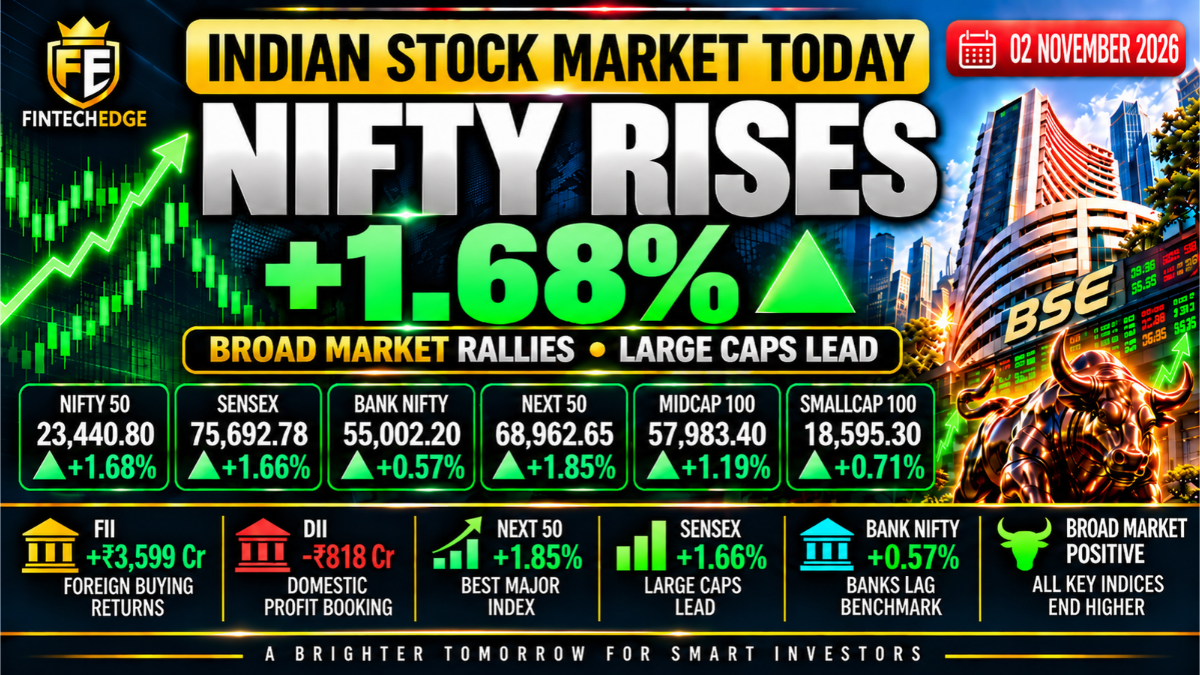
- 2 November: Nifty +1.68%
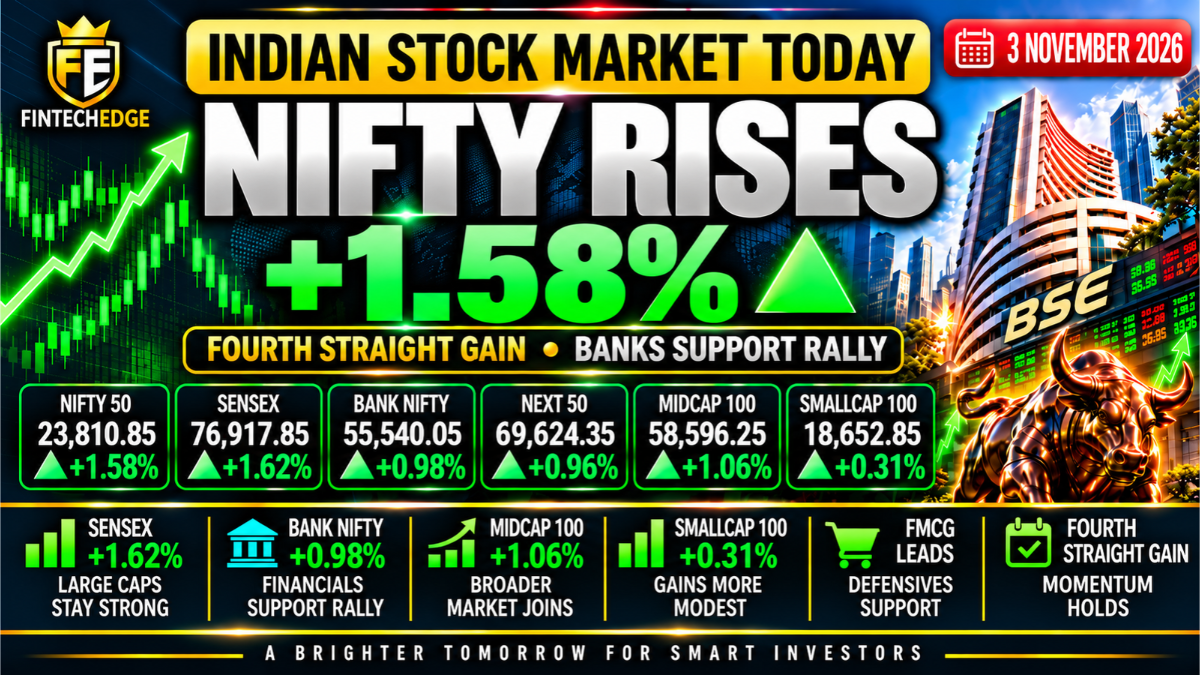
- 3 November: Nifty +1.58%
- 4 November: Nifty +0.63%
But the lower headline gain does not mean the market was weaker.
In fact, today’s internal participation was arguably better because smaller companies materially outperformed the large-cap indices.
That is why the 0.63% Nifty move should not be viewed in isolation.
The five-day recovery is clearly significant, but it still does not prove that the earlier correction has ended or that another sustained uptrend has begun.
The data show improving momentum. They do not establish what comes next.
Smallcaps and Midcaps Lead the Market
The strongest part of the market today was the broader segment.
The Smallcap 100 rose 2.00%, the Next 50 gained 1.68%, and the Midcap 100 advanced 1.55%.
Compare that with:
- Nifty 50: +0.63%
- Sensex: +0.50%
Smallcaps therefore gained more than three times as much as the Nifty.
This is a meaningful reversal from the pattern seen through much of October.
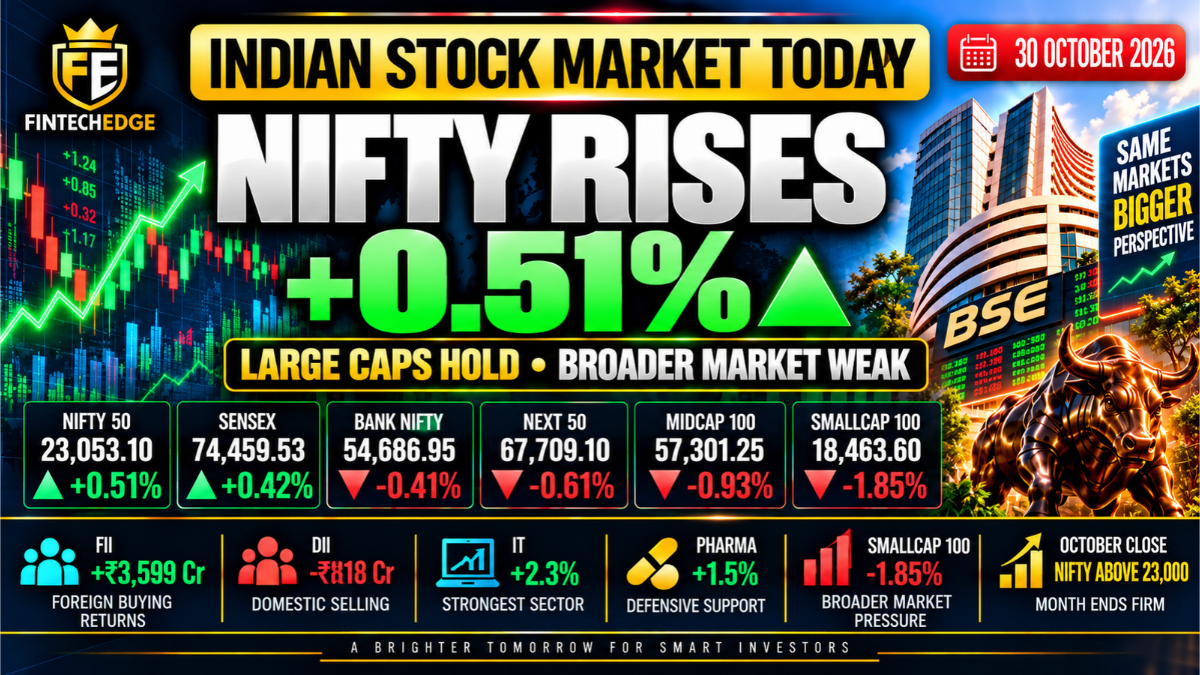
During October, the headline benchmarks recovered while smaller companies remained under pressure. Smallcaps fell around 4.2% for the month and midcaps declined around 3.4%.
The divergence was visible even as recently as 3 November, when the Smallcap 100 gained just 0.31% while the Nifty rose 1.58%.
Today’s session looked very different.
For investors holding midcap or smallcap-heavy portfolios, the market likely felt stronger than the 0.63% Nifty gain suggests.
Still, one strong session should not be treated as confirmation that the broader-market correction is over. Smaller stocks have been volatile in both directions, and sustained participation matters more than a single-day surge.
Foreign-Flow Optimism Supports Sentiment
Foreign institutional flows have become an important part of the improving market narrative. Foreign investors had bought around $821 million of Indian equities in November, reducing their year-to-date net outflow to approximately $30.59 billion. That marks an improvement from the heavy selling seen through much of 2026, although FIIs remain substantial net sellers for the year overall.
For additional context, the previous session’s data showed
- 3 November FII stocks: +₹6,837 crore
- 3 November DII stocks: -₹3,679 crore
These are previous-session figures and should not be treated as 4 November flows.
The key question now is whether the early-November improvement in foreign buying develops into a more sustained trend.buying develops into a sustained change in behaviour.
Crude Oil Falls Toward $102
One of the strongest macro tailwinds for India is the continued decline in crude oil.
Brent crude fell toward roughly $102 per barrel, significantly below the $110–$118 levels seen during parts of October.
For India, lower crude can help across several channels:
- reduce imported inflation;
- ease pressure on the trade deficit;
- support the current account;
- reduce dollar demand from oil importers;
- improve corporate input costs;
- and support the rupee.
That makes the fall in oil particularly important for Indian equities.
The improvement does not mean oil is now cheap. Around $102 per barrel remains elevated.
But the direction has changed enough to reduce one of the biggest macro pressures that weighed on Indian markets last month.
If crude remains closer to $100 than $120, the backdrop for inflation, currency stability and rate-sensitive sectors becomes less difficult.
IT Is the Main Weak Pocket
IT was the clear exception to today’s broad strength.
The sector fell around 1.5%, even as most domestic sectors advanced.
That weakness deserves context.
IT was October’s strongest major sector, surging around 17.7% during the month — its best monthly performance in more than six years.
So one negative session after such a strong run is not enough to establish a reversal.
The more important observation is sector rotation.
Money that had previously concentrated heavily in IT appears to be spreading into other parts of the market, particularly media, metals, realty and broader-market names.
That rotation helped lift the midcap and smallcap indices today.
Sector Rotation Broadens
Sector participation improved meaningfully.
The available data show:
- Media: around +5%
- Metals: around +2%
- Realty: around +2%
- Consumer durables: positive
- Oil & gas: positive
- Energy: positive
- FMCG: positive
- IT: around -1.5%
This is important because several of these outperforming sectors contain significant midcap and smallcap exposure.
That helps explain why the broader market substantially outperformed the Nifty.
It also makes today’s rally structurally different from 2 November, when Reliance’s 11.6% surge played an unusually large role in the benchmark advance.
Today, leadership was more distributed.
Rupee Strengthens to Around ₹94.64
The rupee strengthened further to around ₹94.64 per dollar, compared with ₹94.74 previously.
Lower crude and a softer dollar helped the currency backdrop.
This is supportive for India because currency weakness had been one of the major concerns during the period of high oil prices and rising global yields.
A stronger rupee can help:
- reduce imported inflation pressure;
- improve sentiment among foreign investors;
- reduce the cost of dollar-denominated imports;
- and ease pressure on the RBI.
Still, currency movements remain highly sensitive to global yields, crude oil, the dollar and foreign capital flows.
Bank Nifty Participates but Lags the Broader Market
Bank Nifty gained 0.67%.
That was slightly better than the Nifty’s 0.63% gain, but far below:
- Next 50: +1.68%
- Midcap 100: +1.55%
- Smallcap 100: +2.00%
So banks participated, but they did not lead.
That distinction matters because banking and financial stocks carry significant weight in the large-cap indices.
Today, leadership clearly shifted away from the largest benchmark components and toward the broader market.
From a market-breadth perspective, that is arguably healthier than a rally driven almost entirely by one or two heavyweight stocks.
Why Today’s Market Was Stronger Than the Nifty Suggested
The Nifty gained 0.63%.
But the Smallcap 100 gained 2%.
That difference changes how the session should be interpreted.
Yesterday, large caps led.
Today, the broader market led.
Across the last five sessions, different groups have taken turns supporting the recovery:
- large-cap heavyweights;
- banks;
- FMCG;
- realty;
- metals;
- smallcaps;
- midcaps.
That widening participation is constructive from a market-structure perspective.
But there is an important distinction between better breadth and confirmation of a lasting uptrend.
Today provides evidence for the first.
It does not yet establish the second.
What to Watch Next
Whether the five-session rally continues
The Nifty and Sensex have gained roughly 5.6% over five sessions. A pause after such a run would not be unusual.
Smallcaps and midcaps
Today’s outperformance is significant. The next question is whether broader-market strength persists.
Foreign portfolio flows
Early November data look more supportive, but foreign investors remain large net sellers for 2026 overall.
Brent crude
Oil near $102 is materially more favourable for India than the recent $110–$118 range.
IT
After a strong October, IT weakened today. Whether this is simply rotation or something more persistent will become clearer over subsequent sessions.
Rupee
The currency strengthened again to around ₹94.64, reinforcing the improving macro backdrop.
FintechEdge View
The Indian stock market today extended its recovery to five consecutive sessions, but today’s most important signal was not the Nifty’s 0.63% gain.
It was the improvement in market breadth.
Smallcaps surged 2%, midcaps gained 1.55%, and the Next 50 advanced 1.68%, meaning the strongest part of the market shifted away from the headline large-cap indices.
Lower crude near $102, a stronger rupee and improving expectations around foreign flows provided a more supportive macro backdrop, while IT was the main sectoral laggard.
The five-session rally is now meaningful, but it should still be interpreted carefully.
The strongest conclusion is that participation has broadened materially and external pressures have eased, but neither development by itself proves that the earlier correction is permanently over.
The next few sessions will show whether this broader participation can persist beyond the current five-day run.
Sources & References
- Indian shares extend winning streak as broader markets strengthen — Reuters
- Smallcap 100 jumps 2%, Midcap 100 gains 1.55% — Moneycontrol
- Sector performance and IT weakness — Moneycontrol
- Brent crude, rupee and global-market developments — Reuters
- Nifty 50, Sensex, Bank Nifty and broader-index closing data —NSE India
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.