Indian Stock Market Today: Nifty Falls 0.70% as Smallcaps Buck the Trend
Quick Summary
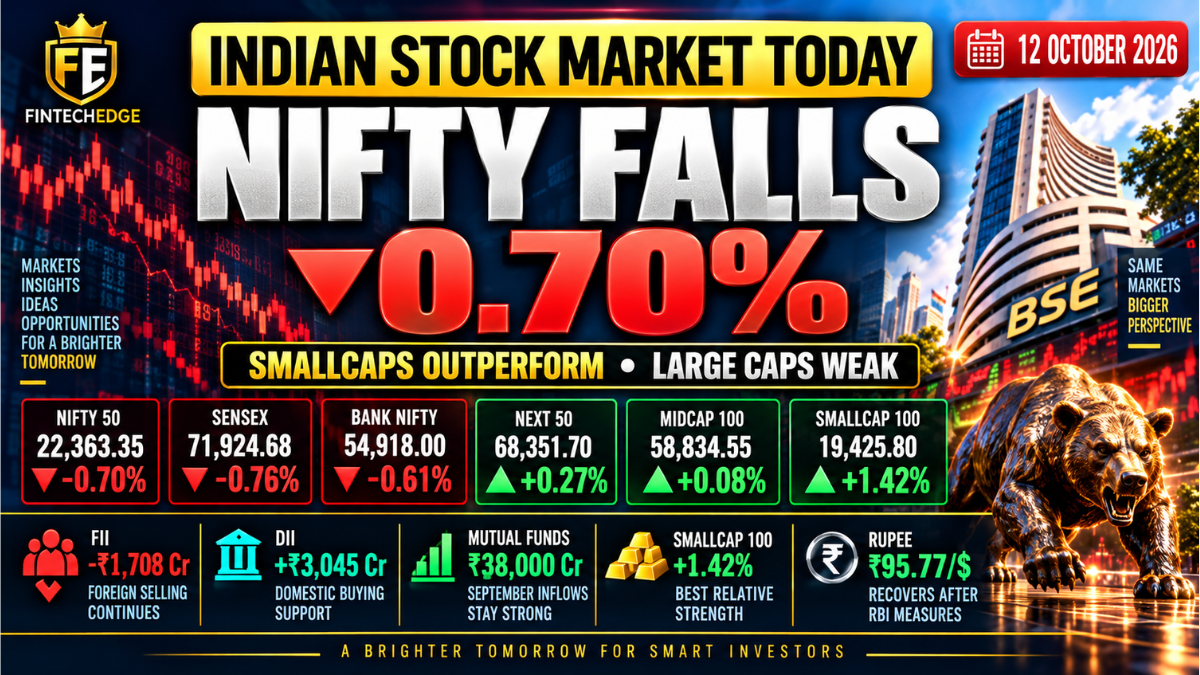
- Nifty 50 fell 0.70% to 22,363.35, while Sensex declined 0.76% to 71,924.68.
- Bank Nifty slipped 0.61%, but broader-market indices held up better.
- Smallcap 100 jumped 1.42%, while Next 50 gained 0.27% and Midcap 100 added 0.08%.
- The rupee rebounded sharply to around ₹95.77 per dollar after RBI measures aimed at reducing dollar demand.
- FIIs sold ₹1,708 crore, while DIIs bought ₹3,045 crore in the stock segment.
- Brent crude remained elevated around $103–$106 per barrel, keeping inflation and currency risks in focus.
- Banks and IT weighed on the benchmarks even as smallcaps and other broader-market segments remained comparatively resilient.
Indian Market Performance — 12 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian equities ended lower on 12 October 2026, but the weakness in the headline indices did not reflect what was happening across the entire market.
The Nifty 50 fell 0.70% to 22,363.35, while the Sensex declined 0.76% to 71,924.68. Bank Nifty also slipped 0.61%.
Yet beneath the benchmarks, the picture was very different. The Nifty Next 50 gained 0.27%, the Midcap 100 edged up 0.08%, and the Smallcap 100 jumped 1.42%.
The session therefore showed a clear split between large-cap weakness and broader-market resilience. At the same time, the rupee staged a sharp rebound after RBI measures, while high oil prices and continued foreign selling remained important macro pressures.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,363.35 | -0.70% |
| Sensex | 71,924.68 | -0.76% |
| Bank Nifty | 54,918.00 | -0.61% |
| Nifty Next 50 | 68,351.70 | +0.27% |
| Nifty Midcap 100 | 58,834.55 | +0.08% |
| Nifty Smallcap 100 | 19,425.80 | +1.42% |
The most important feature of the session was the divergence.
Large-cap benchmarks declined, while all three broader-market indices tracked by FintechEdge finished higher.
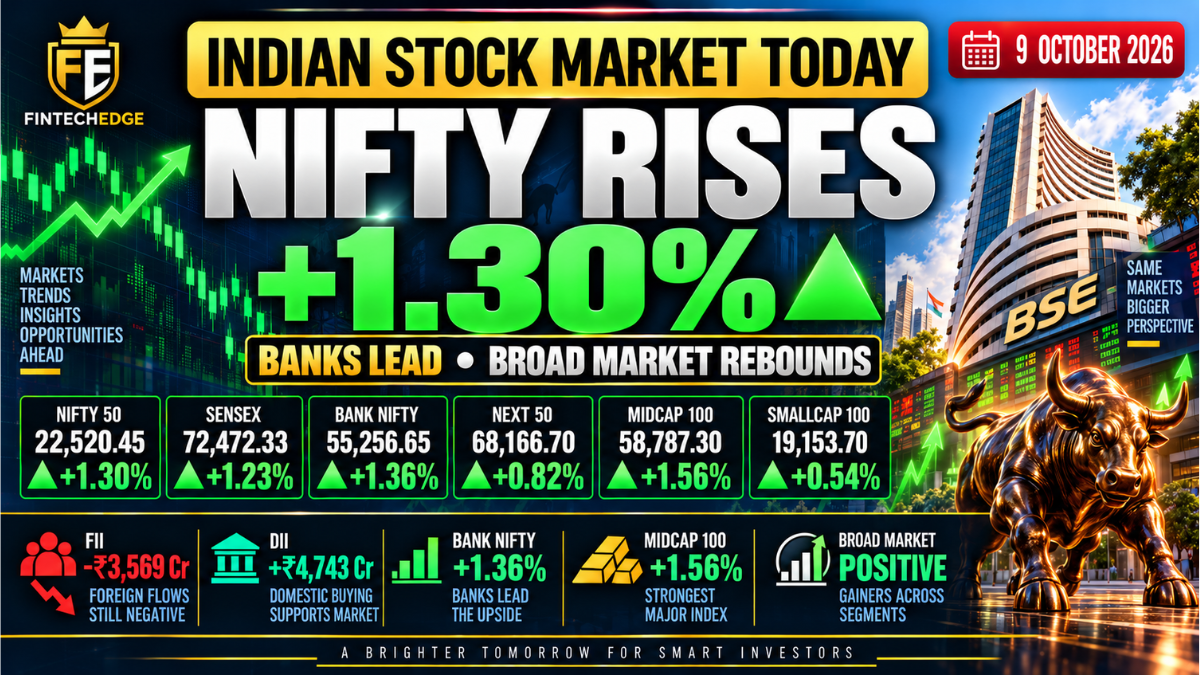
That makes today very different from the broad sell-off seen on 8 October, when the Next 50, midcaps and smallcaps all fell more than 2%.
Smallcaps Buck the Benchmark Weakness
The Smallcap 100 was the clear standout.
While the Nifty fell 0.70% and Sensex lost 0.76%, smallcaps gained 1.42%. The Next 50 and Midcap 100 also managed positive closes.
This matters because headline indices can sometimes give an incomplete picture of market participation.
The Nifty and Sensex are heavily influenced by their largest constituents. Weakness in large banks, IT companies or heavyweight stocks can pull the benchmarks lower even when many other parts of the market are holding up.
That was largely the pattern today.
The divergence should still be interpreted carefully.
The Midcap 100 gained only 0.08%, and the Next 50 just 0.27%, so the strongest relative performance came specifically from smallcaps rather than from a broad surge across every non-large-cap segment.
One positive smallcap session also does not establish that risk appetite has fully returned.
The better conclusion is simply:
headline indices weakened, while the broader market—especially smallcaps—showed better resilience.
Rupee Rebounds After RBI Measures
The rupee was one of the most important macro developments of the day.
Reuters reported that the currency jumped about 1% to ₹95.77 per dollar, marking its strongest one-day gain in six months after the RBI introduced measures aimed at reducing spot-market dollar demand.
The measures included direct dollar supply to oil companies and changes affecting parts of the foreign-exchange derivatives market.
This is important because oil companies are major buyers of dollars.
By reducing some of that demand in the open market, the RBI can ease immediate pressure on the rupee.
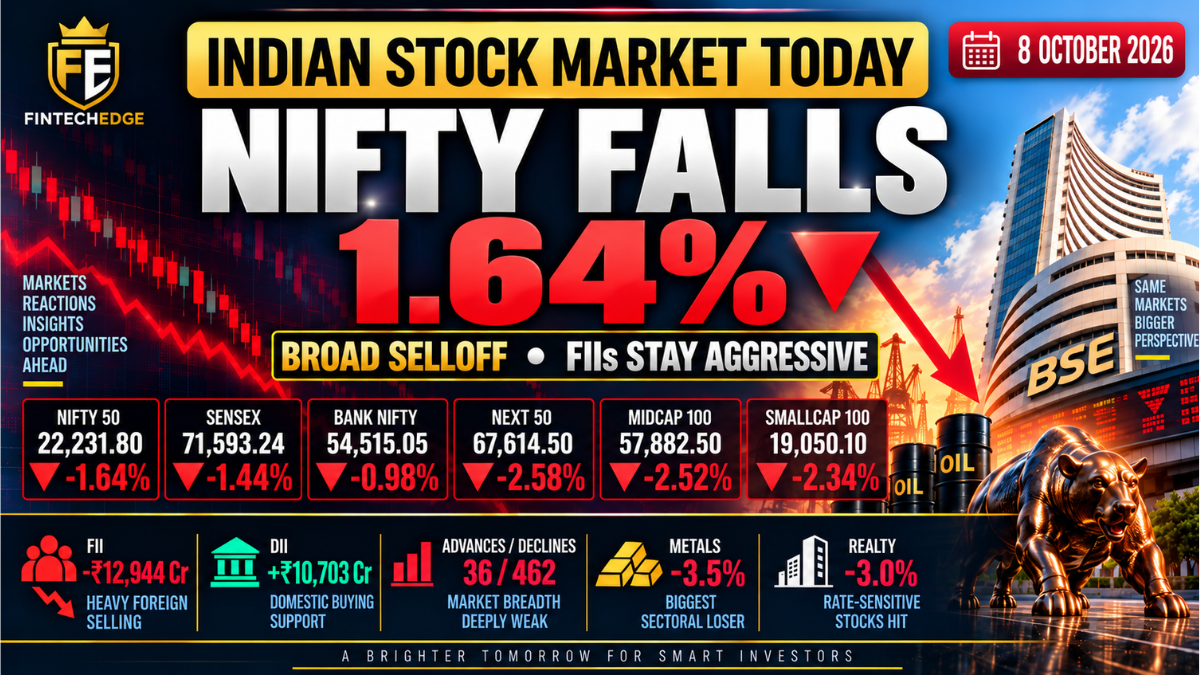
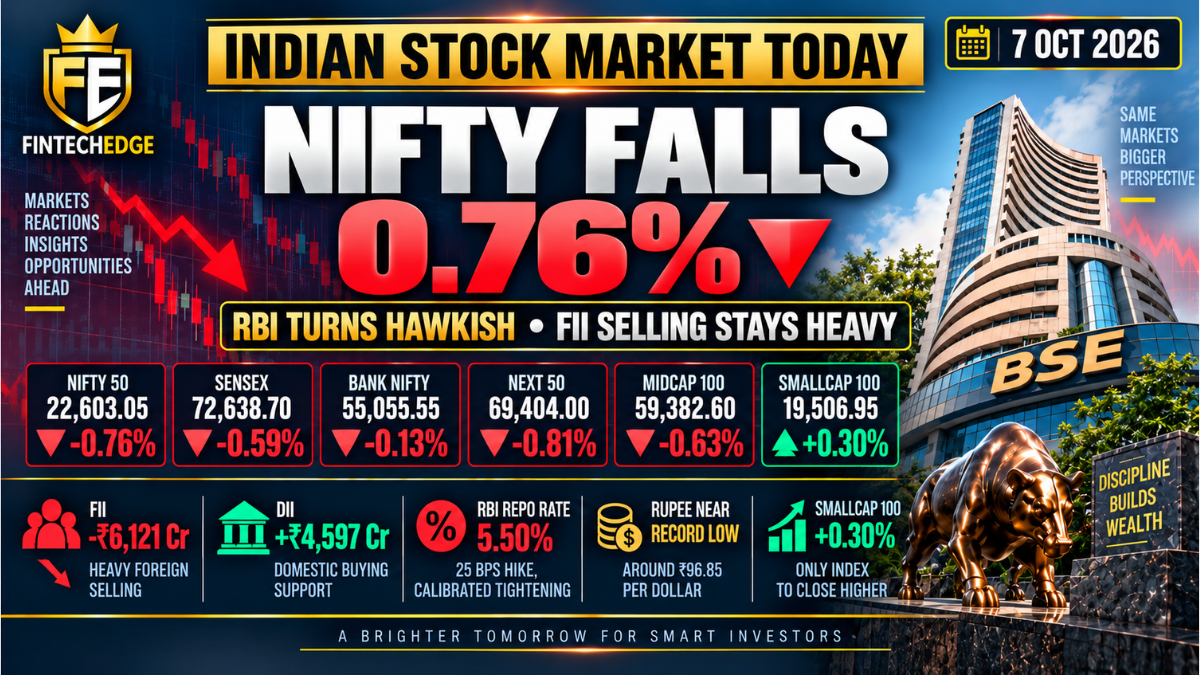
The move comes after several weeks in which currency weakness had become a major part of the market story, including the pressure seen after the RBI rate hike on 7 October.
Still, one strong day in the currency should not be interpreted as a complete reversal.
Oil remains expensive, FIIs are still net sellers, and global yields remain elevated.
The rupee rebound therefore shows that RBI intervention can reduce immediate pressure, but it does not remove the structural factors influencing the currency.
Oil Remains a Key Macro Headwind
Brent crude remained elevated around $103–$106 per barrel amid geopolitical and supply uncertainty.
For India, that continues to matter through several channels.
Higher oil can increase pressure on:
- the import bill;
- inflation;
- the current account;
- the rupee;
- and domestic interest-rate expectations.
The relationship is particularly important now because the RBI has already moved into a tighter monetary-policy environment.
High oil prices can make the central bank’s job more difficult by keeping imported inflation elevated even if domestic demand conditions remain manageable.
The RBI’s decision to supply dollars directly to oil companies also shows how closely the oil and currency pressures are connected.
But oil should not be treated as the sole explanation for today’s index decline.
The market was dealing with a combination of large-cap weakness, foreign selling, tighter policy and global macro uncertainty.
RBI Tightening and FX Support Create a Mixed Backdrop
The RBI has now taken two different types of action.
First, it raised the repo rate to 5.50% and shifted to calibrated tightening.
Second, it introduced additional measures aimed at supporting the rupee.
Those actions address different problems.
Higher policy rates are aimed primarily at inflation and financial conditions, while FX measures are intended to manage currency pressure and dollar demand.
For markets, that creates a mixed policy backdrop.
The rupee benefited today, but equities still faced pressure from elevated oil, inflation concerns and foreign selling.
In other words, policy action eased one source of stress without eliminating the others.
FIIs Sell ₹1,708 Crore, DIIs Buy ₹3,045 Crore
Institutional activity remained an important part of the session.
Your 12 October stock-segment data showed:
- FII: -₹1,708 crore
- DII: +₹3,045 crore
FIIs therefore remained net sellers, while domestic institutions continued to provide support.
The foreign outflow was considerably smaller than some of the heavier selling sessions seen earlier this month, but it was still negative.
That distinction matters.
It would be premature to say foreign selling has ended, but the scale of pressure was more manageable than during sessions such as 8 October, when FII selling reached ₹12,944 crore.
Meanwhile, DII buying remained larger than the day’s FII outflow.
That helps explain why the broader market could remain resilient even while the headline indices fell.
Banks and IT Weigh on the Benchmarks
Banks and IT were among the weaker areas of the market.
Bank Nifty declined 0.61%, and weakness in heavyweight sectors helped drag the Nifty and Sensex lower.
This is important because both financials and IT have significant influence on benchmark performance.
So even with positive participation elsewhere, weakness in those large index components can keep the headline numbers under pressure.
That helps explain today’s apparent contradiction:
the Nifty and Sensex fell, while much of the broader market held up better.
It is exactly why looking only at the headline index can sometimes give an incomplete picture of the session.
Domestic Fund Flows Continue to Provide Support
Domestic liquidity remains an important counterweight to foreign selling.
The video transcript highlighted strong mutual-fund inflows in September, and continued DII buying shows why that matters for the market structure.
Regular inflows into mutual funds and other domestic investment vehicles give institutions capital to deploy even when foreign investors are reducing exposure.
That does not mean domestic buying can prevent market declines.
But it can absorb part of the selling pressure and help explain why certain segments—particularly midcaps and smallcaps—can remain comparatively resilient during periods of FII outflows.
For today’s article, this is supporting context rather than the main story.
The more important observable fact is that DIIs bought ₹3,045 crore while FIIs sold ₹1,708 crore.
Global Backdrop Remains Cautious
Global sentiment remained mixed as investors continued to watch elevated oil prices, high bond yields, corporate earnings and upcoming US inflation data.
These factors remain important for India because global yields influence capital flows and currency pressure, while US inflation data can affect expectations around the Federal Reserve.
The external backdrop therefore remains uncertain even as the rupee received some domestic policy support.
What to Watch Next
Rupee
The currency’s sharp rebound was significant. The next question is whether the improvement holds or whether oil and foreign outflows begin pushing it lower again.
Brent crude
Oil around $103–$106 remains an important risk for inflation, the current account and the rupee.
FII flows
Foreign selling continued today, although at a smaller scale. A sustained moderation would improve the market backdrop.
Smallcap strength
Smallcaps gained 1.42% while the headline indices fell. Whether that divergence continues will be an important signal about underlying risk appetite.
Banks and IT
Both weighed on the benchmarks today. Stabilisation in these heavyweight sectors would make it easier for the Nifty and Sensex to participate if broader-market strength continues.
US inflation and yields
Upcoming US inflation data could again influence Treasury yields and global risk sentiment.
FintechEdge View
The Indian stock market today was a good example of why the Nifty alone does not always describe the full market.
The Nifty and Sensex declined, but the Smallcap 100 gained 1.42%, while the Next 50 and Midcap 100 also managed positive closes.
At the same time, the rupee staged a significant rebound following RBI measures, and domestic institutions continued to absorb foreign selling.
But important pressures remain.
Oil is still elevated, FIIs remain net sellers, global yields remain high and the RBI is operating in a tighter policy environment.
Today’s market therefore cannot be described simply as bullish or bearish.
It was a split session: weakness in large-cap benchmarks alongside resilience in parts of the broader market.
That divergence—not the 0.70% fall in the Nifty—is the more useful signal to carry forward.
Sources & References
- Indian shares slip as oil and inflation concerns weigh despite rupee support measures Reuters
- Rupee jumps after RBI measures reduce spot-market dollar demand Reuters
- RBI rupee measures trigger currency rally and forward-market swings Reuters
- Global markets remain cautious as oil and inflation risks stay elevated Reuters
- September mutual fund industry data AMFI India
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.