Indian Stock Market Today: Nifty Falls 1.11% as Private Banks Lead Sell-Off
Quick Summary
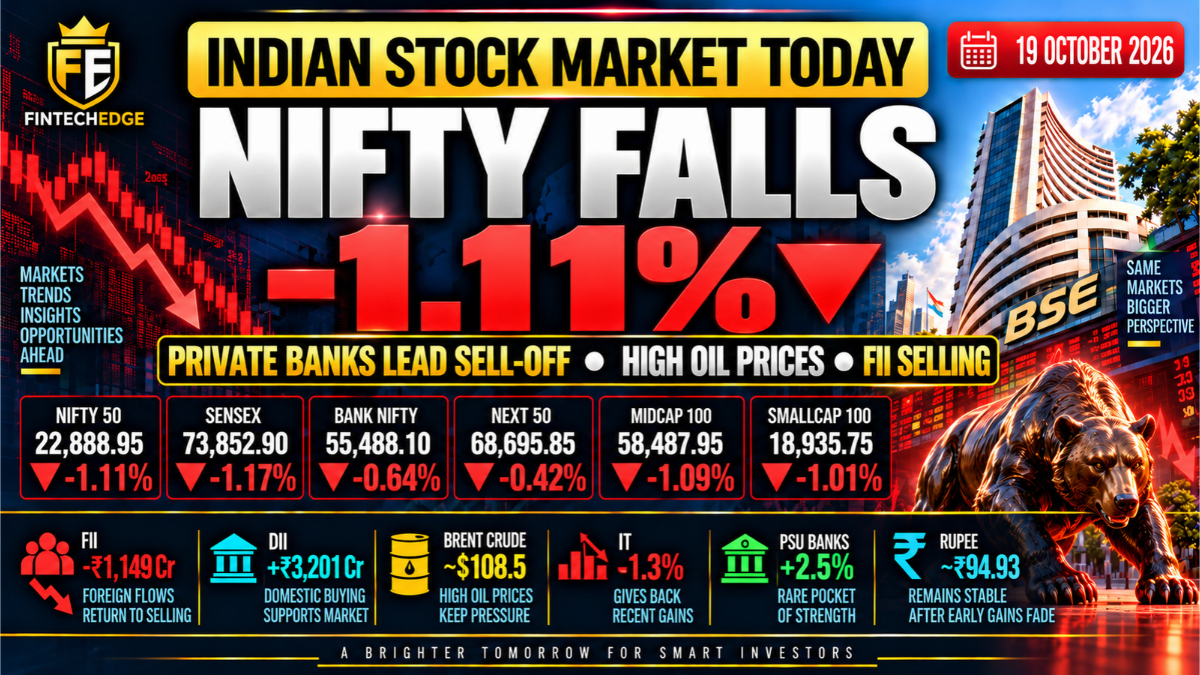
- Nifty 50 fell 1.11% to 22,888.95, while Sensex dropped 1.17% to 73,852.90.
- Private banks were a major drag, while Bank Nifty declined 0.64%.
- Selling spread to the broader market, with Midcap 100 down 1.09% and Smallcap 100 down 1.01%.
- FIIs returned to net selling at ₹1,149 crore, while DIIs bought ₹3,201 crore.
- Brent crude remained elevated near $108.5 per barrel, keeping macro pressure in focus.
- PSU banks were a rare pocket of strength, gaining about 2.5%.
- IT fell about 1.3%, giving back part of last week’s strong gains.
Indian Market Performance — 19 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian equities fell sharply on 19 October 2026, reversing part of the previous week’s rebound.
The Nifty 50 fell 1.11% to 22,888.95, while the Sensex dropped 1.17% to 73,852.90. Bank Nifty declined 0.64%, and the weakness extended beyond the large-cap benchmarks: the Midcap 100 lost 1.09% and the Smallcap 100 fell 1.01%. Pasted text
Private banks were the clearest domestic drag, while elevated crude oil prices, renewed FII selling and weaker global risk sentiment added pressure. Unlike several recent sessions in which broader markets held up better than the benchmarks, today’s decline was much more widespread. Reuters also reported that 15 of 16 major sectoral indices ended lower, while PSU banks were the notable exception.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,888.95 | -1.11% |
| Sensex | 73,852.90 | -1.17% |
| Bank Nifty | 55,488.10 | -0.64% |
| Nifty Next 50 | 68,695.85 | -0.42% |
| Nifty Midcap 100 | 58,487.95 | -1.09% |
| Nifty Smallcap 100 | 18,935.75 | -1.01% |
All six indices tracked by FintechEdge closed lower.
That is an important change from 16 October, when the Nifty and Sensex advanced while midcaps and smallcaps remained nearly flat.
Today, the weakness was more broad-based.
Private Banks Lead the Decline
Private-bank weakness was the clearest domestic pressure on the market.
Axis Bank was one of the biggest drags after its September-quarter profit came in slightly below expectations. The bank reported standalone net profit of ₹70.03 billion, compared with analyst expectations of about ₹71.24 billion, as higher operating expenses and weaker non-interest income offset healthy loan growth and lower provisions.
Axis Bank shares fell sharply, while HDFC Bank and ICICI Bank also weakened.
This matters because private banks carry substantial weight in the Nifty and Sensex.
A decline in several large financial stocks can therefore have a much larger impact on the benchmarks than weakness in many smaller companies.
Bank Nifty fell 0.64%, which was still less than the Nifty’s 1.11% decline. That tells us banking weakness was important, but it was not the only problem.
Oil, IT weakness, broader-market selling and foreign outflows all contributed to the session.
Broader Market Also Weakens
The broader market weakened much more clearly than it had during the previous week’s large-cap-led recovery.
The Midcap 100 fell 1.09%, while the Smallcap 100 lost 1.01%.
The Nifty Next 50 performed somewhat better but still declined 0.42%.
This is an important contrast with 15 October, when the Nifty and Sensex rallied strongly even as the broader market struggled.
Today, there was much less separation.
The large-cap benchmarks were lower, and midcaps and smallcaps were lower too.
That makes the session more genuinely risk-off than some of the recent headline declines.
Oil Remains a Macro Headwind
Brent crude remained around $108.5 per barrel, despite easing from recent highs.
For India, oil at these levels remains a significant macro concern because the country imports a large portion of its crude requirements.
Higher oil can affect:
- inflation;
- the import bill;
- the current account;
- the rupee;
- domestic interest-rate expectations;
- and foreign investor sentiment.
The relationship becomes particularly important when foreign investors are already reducing exposure to Indian equities.
That said, oil should not be treated as the sole reason for today’s decline.
The domestic trigger was more clearly visible in private-bank weakness, while high crude added to an already difficult macro backdrop.
FIIs Return to Net Selling
Institutional-flow data also weakened again.
Your 19 October stock-segment figures show:
- FII: -₹1,149 crore
- DII: +₹3,201 crore
That reverses the pattern seen on 16 October, when FIIs had turned net buyers for the day.
The change is important because last Friday’s positive FII number could have been interpreted as an early improvement in foreign flows.
Today’s data show that one session was not enough to establish a trend change.
At the same time, DIIs resumed their familiar supporting role by buying more than ₹3,200 crore of equities.
Domestic buying therefore continued to cushion part of the foreign selling pressure.
The correct conclusion is not that FIIs have decisively exited again, but that foreign flow remains unstable and has not yet turned consistently positive.
PSU Banks Buck the Trend
The banking sector itself was highly divided.
Private banks were among the biggest losers, but PSU banks moved in the opposite direction.
Reuters reported that the public-sector bank index rose about 2.5%, helped by strong earnings from Punjab National Bank and Union Bank.
This was one of the most interesting divergences of the session.
It shows why simply saying “banks were weak” would be inaccurate.
The actual picture was:
private banks sold off, while PSU banks showed strong relative strength.
That does not prove PSU banks have formed a long-term bottom or that the relative strength will continue.
It simply means earnings supported that segment while private-bank earnings disappointed investors.
IT Gives Back Some Recent Gains
IT also weakened after being the dominant market leader in the previous week.
The sector fell around 1.3% on Monday after delivering an exceptional rally in the preceding sessions.
The pullback needs context.
On 16 October, IT had capped its strongest weekly performance in 18 years.
A decline after a move of that scale does not by itself mean the IT rebound has ended.
It means some of the recent gains were given back as the broader market weakened.
The next round of earnings and global technology sentiment will matter more than one negative session.
Rupee Holds Near ₹94.93
The rupee remained comparatively stable.
It ended near ₹94.93 per dollar, with early gains fading as stock-market weakness and importer demand for dollars offset some of the benefit from softer crude.
That follows the currency’s strongest weekly performance in seven months.
For Indian equities, currency stability remains helpful because it reduces one source of concern for foreign investors and lowers some imported inflation pressure.
But high oil and continued portfolio outflows mean the underlying pressures have not disappeared.
Global Tech Sentiment Remains Fragile
The international backdrop also remained cautious.
US chip and AI-related stocks were attempting to recover on Monday after a sharp sell-off in the previous week, helped by lower Treasury yields and easing oil prices.
The rebound overseas does not remove the broader concerns around:
- AI valuations;
- capital spending;
- high borrowing costs;
- and elevated inflation.
For India, this matters most through global risk appetite and foreign portfolio flows rather than through a direct one-to-one relationship with domestic equities.
Jio Platforms IPO Moves Into Focus
Investor attention is also turning toward the upcoming Jio Platforms IPO.
Reuters reported that the offer is expected to open on Wednesday and is being watched closely as one of the largest equity-market events in India.
This should be treated as an upcoming catalyst rather than an explanation for today’s decline.
The IPO could influence liquidity and investor attention, but the stronger drivers today were private-bank weakness, oil, broad selling and FII outflows.
What to Watch Next
Private-bank earnings
Today’s decline was heavily influenced by financials. Stabilisation in HDFC Bank, Axis Bank and other private banks would reduce pressure on the benchmarks.
Market breadth
Midcaps and smallcaps fell alongside the Nifty today. Whether that weakness continues will be important for judging the health of the broader market.
FII flows
FIIs returned to selling after one positive session. A more consistent improvement in foreign flows would be more meaningful than any single day.
Brent crude
Oil around $108 remains a significant macro risk for India.
IT
The sector gave back some gains after an exceptional week. Whether earnings support continues will determine if the recent rebound can hold.
Jio Platforms IPO
The upcoming IPO will be an important liquidity and sentiment event for the domestic market.
FintechEdge View
The Indian stock market today looked materially weaker than several of the recent sessions because the selling was not confined to one part of the market.
The Nifty and Sensex fell more than 1%, but midcaps and smallcaps also declined by around the same amount.
Private banks were the clearest domestic drag, while elevated crude and renewed FII selling added to the pressure.
There were still important exceptions.
PSU banks rose strongly on earnings, and the rupee remained relatively stable.
But compared with last week’s IT-led recovery, today’s market was much less supportive beneath the surface.
The most useful conclusion is therefore straightforward:
19 October was a broad pullback, led by private-bank weakness and reinforced by high oil and renewed foreign selling—not simply a one-sector correction.
Sources & References
- Indian shares fall as private banks lead losses; investors await Jio IPO Reuters
- Axis Bank slides after quarterly profit falls short of expectations Reuters
- Axis Bank quarterly profit rises but misses estimates on higher costs Reuters
- Wall Street tech and AI stocks rebound after recent sell-off Reuters
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.