Indian Stock Market Today: Nifty Falls 0.44% as Oil and Yields Weigh
Quick Summary
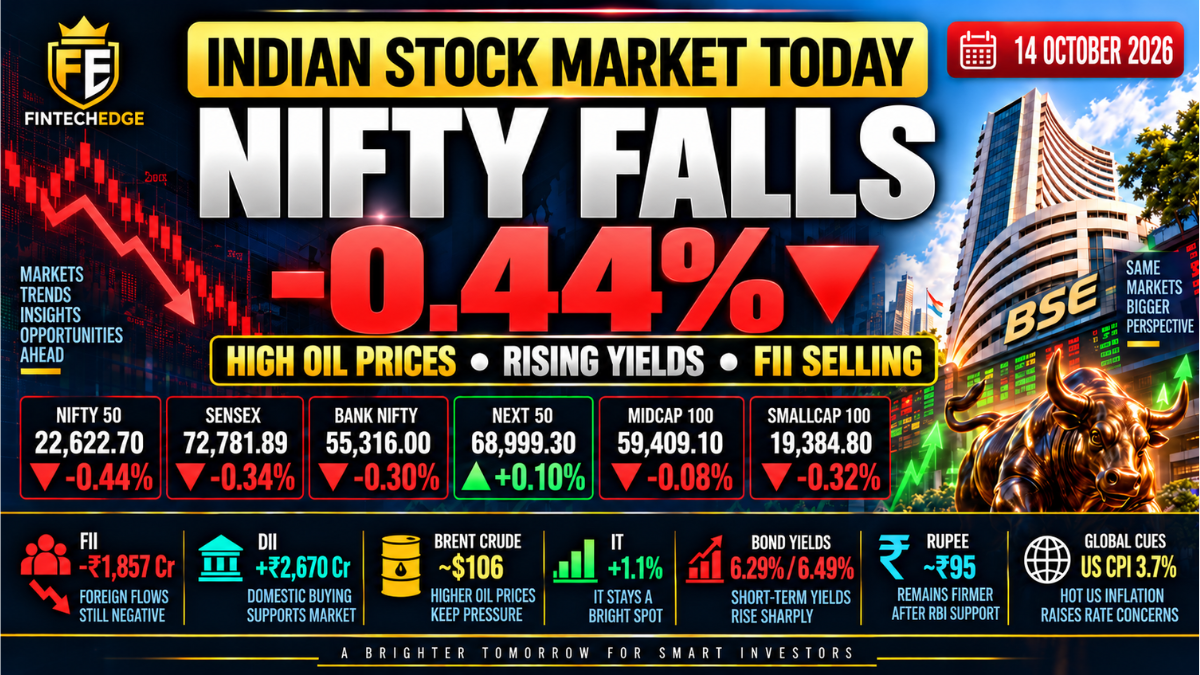
- Nifty 50 fell 0.44% to 22,622.70, while Sensex declined 0.34% to 72,781.89.
- Bank Nifty slipped 0.30%, while Nifty Next 50 edged 0.10% higher.
- Midcap 100 was nearly flat at -0.08%, while Smallcap 100 declined 0.32%.
- Brent crude remained near $106 per barrel, keeping inflation and currency risks elevated.
- FIIs sold ₹1,857 crore, while DIIs bought ₹2,670 crore in the stock segment.
- IT remained a relative bright spot, gaining around 1.1% despite weaker headline indices.
- Rising domestic borrowing costs and hotter US inflation kept rate concerns in focus.
Indian Market Performance — 14 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian equities slipped on 14 October 2026, giving back part of the previous session’s strong gains as elevated crude oil prices, rising domestic borrowing costs and continued foreign selling weighed on sentiment.
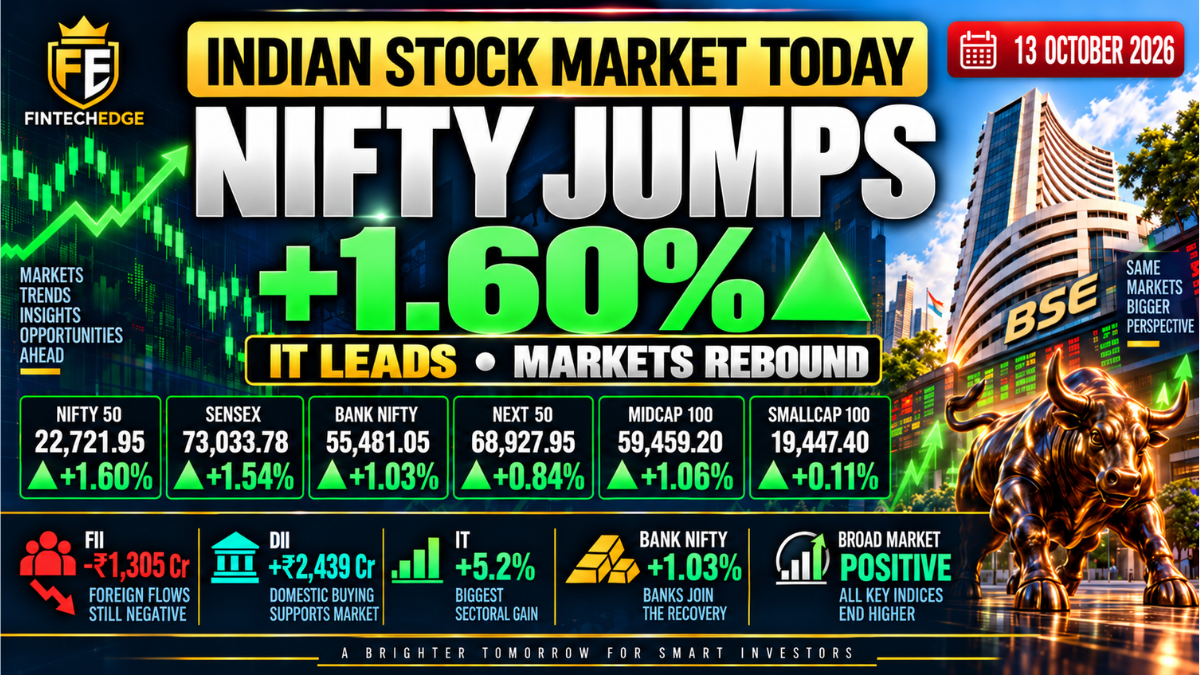
The Nifty 50 fell 0.44% to 22,622.70, while the Sensex declined 0.34% to 72,781.89. Bank Nifty slipped 0.30%.
The broader market, however, showed relatively limited damage. The Nifty Next 50 edged 0.10% higher, while the Midcap 100 fell only 0.08% and the Smallcap 100 declined 0.32%.
The session therefore looked more like consolidation after the strong IT-led rally on 13 October than a broad risk-off move. IT remained a relative bright spot, but high oil prices, rising short-term borrowing costs and persistent FII selling kept the overall market under pressure.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,622.70 | -0.44% |
| Sensex | 72,781.89 | -0.34% |
| Bank Nifty | 55,316.00 | -0.30% |
| Nifty Next 50 | 68,999.30 | +0.10% |
| Nifty Midcap 100 | 59,409.10 | -0.08% |
| Nifty Smallcap 100 | 19,384.80 | -0.32% |
The headline indices finished lower, but the broader-market picture was relatively stable.
The Next 50 ended slightly positive, while midcaps were almost unchanged. Smallcaps fell, but their 0.32% decline was still smaller than the Nifty’s 0.44% fall.
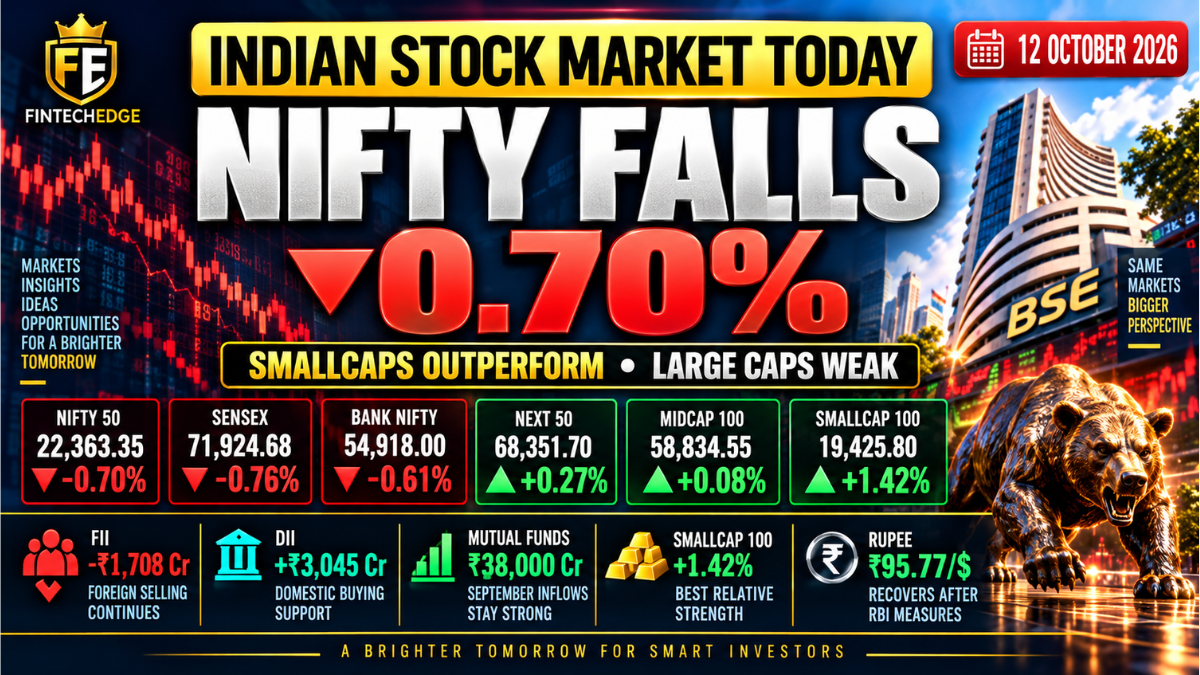
That makes today different from the sharper broad sell-off seen on 8 October, when the Next 50, midcaps and smallcaps all lost more than 2%.
Oil Near $106 Keeps Macro Pressure High
Elevated crude oil remained one of the clearest macro headwinds for Indian equities.
Brent crude traded near $106 per barrel amid continuing geopolitical uncertainty and concerns around global energy supply.
For India, this matters because the economy imports a large portion of its crude requirements.
Higher oil prices can affect several areas at once:
- the import bill;
- inflation;
- the current account;
- the rupee;
- and expectations around interest rates.
The oil backdrop is particularly important now because the RBI has already shifted toward tighter monetary policy.
Higher crude can make inflation more difficult to contain, while also increasing dollar demand from Indian oil importers.
That does not mean oil alone explains today’s market decline.
The Nifty was also dealing with continued foreign selling and rising domestic borrowing costs. But crude around $106 keeps one of India’s most important external vulnerabilities firmly in focus.
Rising Borrowing Costs Add to Rate Concerns
One of the more important developments beneath the equity market was the rise in short-term government borrowing costs.
India’s 182-day Treasury bill yield rose to around 6.29%, while the 364-day T-bill yield reached about 6.49%.
Both are now significantly above the RBI’s 5.50% repo rate.
That matters because market interest rates influence the cost of money across the financial system.
When short-term yields rise sharply, borrowing conditions can tighten for:
- companies;
- banks and NBFCs;
- consumers;
- real estate;
- autos;
- and other rate-sensitive sectors.
This does not mean the RBI is certain to raise rates again.
Bond markets can move for several reasons, including liquidity, supply, inflation expectations and global rate movements.
But the rise in yields does show that financial conditions are becoming more restrictive.
That is an important signal for equities because higher borrowing costs can eventually affect both earnings expectations and valuation multiples.
FIIs Sell ₹1,857 Crore, DIIs Buy ₹2,670 Crore
Institutional flows remained mixed.
Your 14 October stock-segment data showed:
- FII: -₹1,857 crore
- DII: +₹2,670 crore
Foreign investors therefore remained net sellers, while domestic institutions once again provided support.
This has become a recurring feature of the market.
FIIs have continued reducing exposure, while domestic institutions have absorbed a significant portion of that supply.
The scale of today’s FII selling was nowhere near some of the extreme outflow sessions seen earlier this month, but it was still negative.
Domestic buying exceeded foreign selling today, which likely helped limit broader-market damage.
That pattern also helps explain why the market has often shown pockets of resilience even while FII activity remains weak.
IT Remains a Relative Bright Spot
IT continued to outperform after the sharp sector rally seen on 13 October.
The Nifty IT index gained about 1.1%, extending some of the strength generated by recent earnings from HCLTech and TCS.
This is notable because the headline benchmarks finished lower.
The sector has now delivered several stronger sessions after a prolonged period of weakness.
But it is still too early to conclude that IT has formed a durable bottom or entered a new uptrend.
The more useful observation is simply that IT remained one of the few clear areas of relative strength while several rate-sensitive sectors struggled.
That helped cushion the decline in the benchmark indices.
Broader Market Holds Up Better
The broader market performed better than the headline Nifty decline might suggest.
The Nifty Next 50 gained 0.10%, while the Midcap 100 was almost unchanged at -0.08%.
The Smallcap 100 declined 0.32%, but that was still a relatively contained move compared with some recent sessions.
This indicates that today’s selling pressure was not equally distributed across the market.
Yesterday’s rally had been driven mainly by IT, large caps, banks and midcaps, with smallcaps barely participating.
Today, broader indices remained relatively stable even as the benchmarks slipped.
That suggests the market was mixed rather than uniformly weak.
Sector Performance Remains Divided
Sectoral performance was also mixed.
IT remained firm, while energy, FMCG, oil & gas and selected public-sector names showed relative strength.
On the weaker side, financial services, real estate, autos and pharma faced pressure.
This division is consistent with the broader macro setup.
Rate-sensitive sectors have more reason to react negatively when borrowing costs rise, while certain defensive or energy-related areas can behave differently depending on earnings and commodity conditions.
The important point is that today was not a session where every sector moved in the same direction.
That helps explain why the headline indices were lower even though the broader market remained relatively stable.
Rupee Remains Firmer After RBI Measures
The rupee continued to trade firmer after recent RBI measures aimed at reducing dollar demand.
The currency touched around ₹94.77 per dollar before giving back part of the move and trading closer to ₹95.
This follows the significant rebound seen after the RBI intervened more aggressively in the foreign-exchange market.
A stronger rupee can be supportive because it reduces some pressure from:
- imported inflation;
- oil purchases;
- foreign investor concerns;
- and external financing conditions.
But the currency still faces competing forces.
Elevated crude prices increase dollar demand from importers, while persistent portfolio outflows create additional pressure.
So the recent rupee recovery is important, but it should not be interpreted as the end of India’s currency challenge.
Hot US Inflation Adds a New Global Risk
Another important development came from the US inflation data.
Headline US CPI rose 3.7% year-on-year, while core inflation remained elevated.
That pushed short-term Treasury yields higher and strengthened expectations that US monetary policy could remain restrictive for longer.
The timing matters.
The data arrived after the Indian market session, so it should not be treated as the reason for today’s domestic decline.
But it becomes an important factor for the next session.
Higher US yields can:
- increase demand for dollar assets;
- pressure emerging-market currencies;
- reduce foreign appetite for equities;
- and raise valuation pressure globally.
That makes the global rate environment one of the biggest variables for Indian markets to watch from here.
What to Watch Next
Brent crude
Oil near $106 remains an important macro risk. Any further rise would increase pressure on inflation, the rupee and India’s external balances.
Domestic bond yields
The rise in short-term borrowing costs deserves attention. Further increases could weigh more heavily on rate-sensitive sectors.
FII flows
Foreign investors remain net sellers. A sustained reduction in outflows would improve the market backdrop.
IT
IT remains one of the stronger sectors after recent earnings. The next question is whether the strength can continue as more companies report results.
Rupee
The currency has strengthened after RBI intervention, but importer dollar demand and portfolio outflows remain important counterforces.
US inflation and Treasury yields
Hotter US inflation could push yields higher again and increase pressure on emerging markets.
FintechEdge View
The Indian stock market today was considerably more balanced than the Nifty’s 0.44% decline suggests.
Headline indices weakened, but the broader market remained relatively stable. The Next 50 actually finished higher, midcaps were almost unchanged, and smallcaps saw only a modest decline.
At the same time, IT continued to show relative strength following the strong earnings-driven rally seen earlier this week.
The bigger concern remains the macro environment.
Crude oil is still elevated, domestic borrowing costs are rising, FIIs remain net sellers and US inflation has revived concerns around global interest rates.
The rupee’s recent recovery is helpful, but it offsets only one part of that pressure.
For now, today’s session looks less like a renewed broad sell-off and more like a mixed consolidation day after the previous session’s sharp rally.
The next meaningful signal will come from whether oil and yields ease—or whether those pressures begin to spread more clearly into the broader market.
Sources & References
- Indian shares slip as oil prices and foreign outflows weigh Reuters
- India’s short-term borrowing costs rise sharply above the policy rate Reuters
- Rupee remains firmer after RBI measures but gains lose momentum Reuters
- Hot US inflation pushes yields higher and raises rate concerns Reuters
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.