Indian Stock Market Today: Nifty Falls 0.39% as Smallcaps Drop 2.94%
Quick Summary
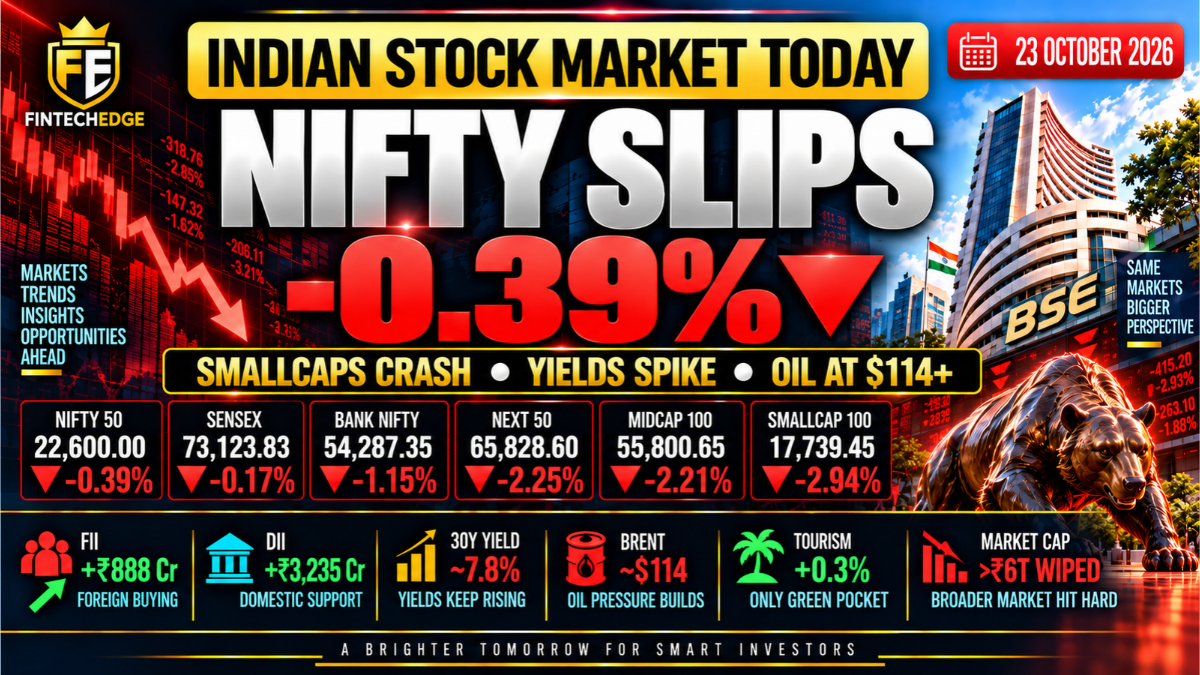
- Nifty 50 fell 0.39% to 22,600.00, while Sensex declined 0.17% to 73,123.83.
- Broader-market selling was much sharper, with Next 50 down 2.25%, Midcap 100 down 2.21%, and Smallcap 100 down 2.94%.
- Bank Nifty fell 1.15%, adding pressure from financial stocks.
- Brent crude traded near $115 per barrel, keeping inflation, rupee and corporate-margin concerns elevated.
- FIIs bought ₹888 crore, while DIIs bought ₹3,235 crore in the stock segment.
- For the week, Nifty lost about 2.4%, while smallcaps fell roughly 7.3% and midcaps about 5.6%.
- The rupee lost some recent momentum as elevated oil offset earlier support.
Indian Market Performance — 23 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian stock market today ended lower on 23 October 2026, but the relatively small decline in the Nifty again understated the pressure across the wider market.
The Nifty 50 fell 0.39% to 22,600.00, while the Sensex declined 0.17% to 73,123.83. Bank Nifty dropped 1.15%, but the deeper damage came from the broader indices: the Nifty Next 50 lost 2.25%, the Midcap 100 fell 2.21%, and the Smallcap 100 plunged 2.94%.
Crude oil near $115 remained the dominant macro pressure, while financials and smaller companies continued to weaken. Yet institutional-flow data produced an unusual contrast: both FIIs and DIIs were net buyers despite the sharp broader-market sell-off.
The session also completed a difficult week in which smallcaps and midcaps suffered far heavier losses than the headline benchmarks.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,600.00 | -0.39% |
| Sensex | 73,123.83 | -0.17% |
| Bank Nifty | 54,287.35 | -1.15% |
| Nifty Next 50 | 65,828.60 | -2.25% |
| Nifty Midcap 100 | 55,800.65 | -2.21% |
| Nifty Smallcap 100 | 17,739.45 | -2.94% |
The central market signal was the gap between the headline benchmarks and the broader indices.
The Nifty fell less than half a percent, but the Smallcap 100 lost almost 3%.
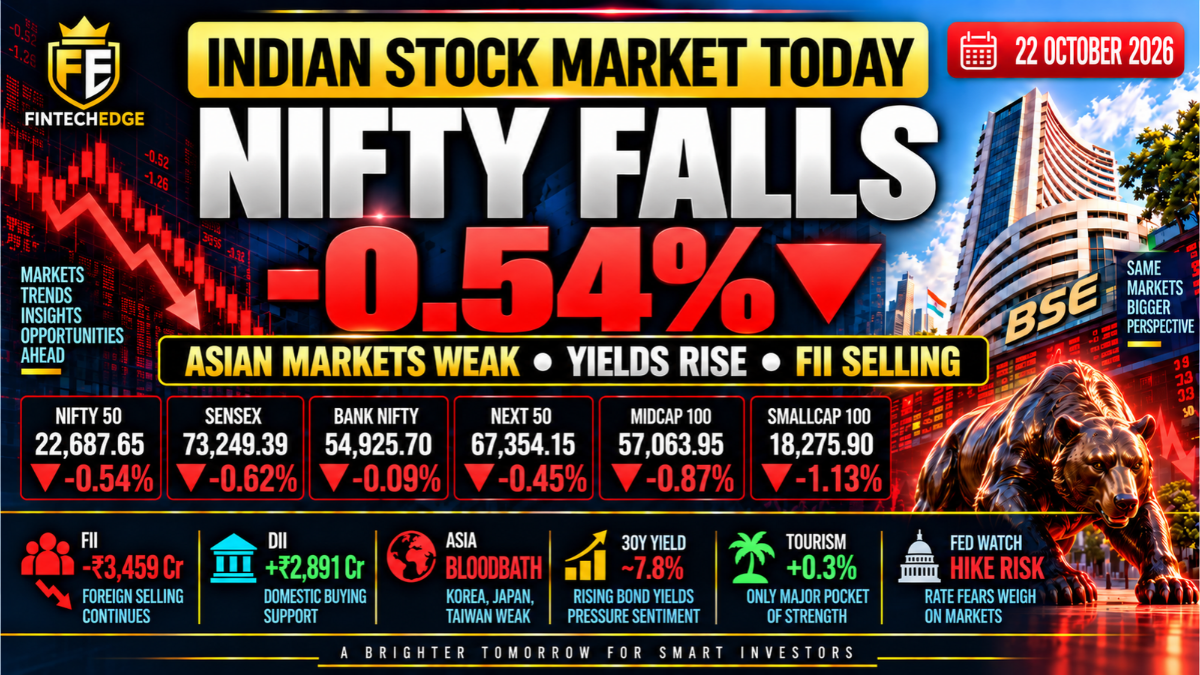
That divergence was even sharper than the broad weakness seen on 22 October, when smallcaps had already declined 1.13% and midcaps 0.87%.
Smallcaps and Midcaps Lead the Sell-Off
The Nifty’s 0.39% decline does not adequately describe what happened across the market.
The Smallcap 100 fell 2.94%, the Next 50 declined 2.25%, and the Midcap 100 lost 2.21%.
For investors exposed mainly to smaller companies, this was therefore a much more difficult session than the benchmark suggested.
That pattern has now persisted across several sessions.
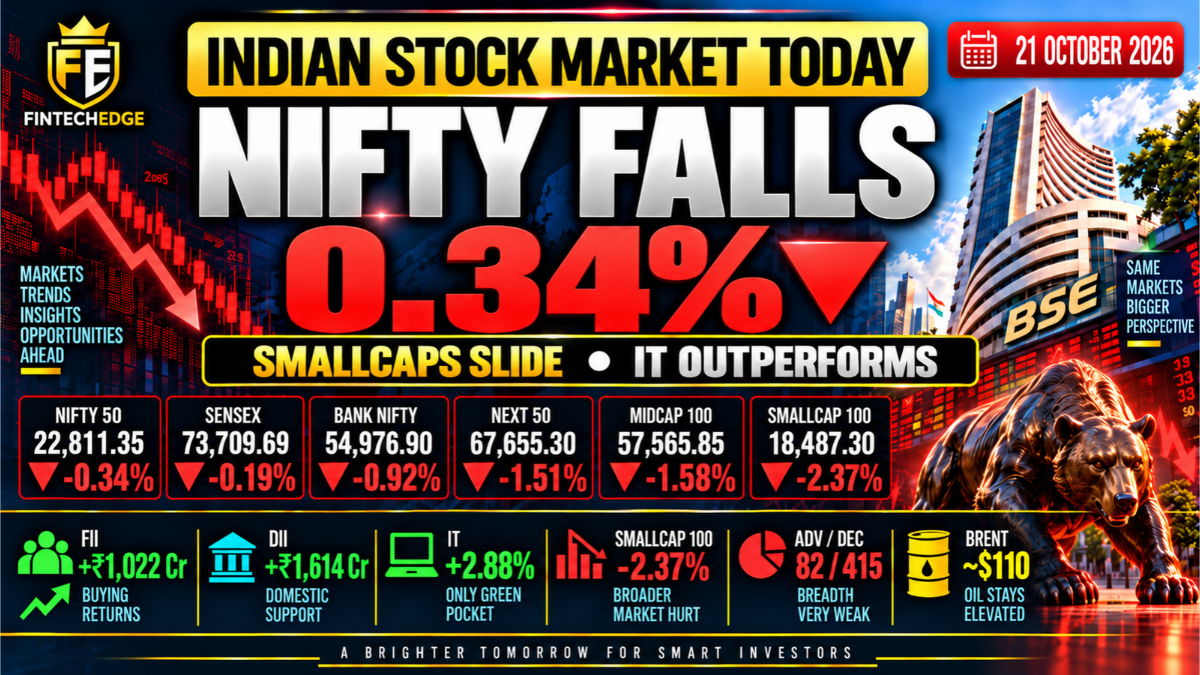
On 21 October, smallcaps fell 2.37% even though the Nifty declined only 0.34%. On 22 October, the broader market again underperformed.
Today that weakness intensified.
This is why market breadth matters.
The Nifty and Sensex represent the largest companies in the market. Their movement can sometimes be cushioned by a handful of heavyweight stocks even while a much larger number of shares are falling.
That is effectively what the recent sessions have shown.
Oil Near $115 Keeps Macro Pressure High
Crude oil remained the clearest external pressure.
Brent traded around $114.99 per barrel after touching about $115.16, its highest level since early May. Pasted text
For India, high crude prices matter because the country imports a large share of its energy requirements.
Sustained oil prices at these levels can affect:
- inflation;
- the import bill;
- the current account;
- the rupee;
- corporate input costs;
- and interest-rate expectations.
Those concerns become more important when markets are already dealing with weaker breadth and elevated global yields.
Oil should not be treated as the sole explanation for every stock-market move.
But in the current environment, it remains one of the most important macro variables for Indian assets.
Bank Nifty Falls More Than 1%
Financial stocks added to the pressure.
Bank Nifty fell 1.15%, much more than the Nifty’s 0.39% decline.
Banks carry heavy weight in the benchmark indices, so weakness in financials can have an outsized influence on the Nifty and Sensex.
The banking sector has also had an uneven week, with several large financial names coming under pressure.
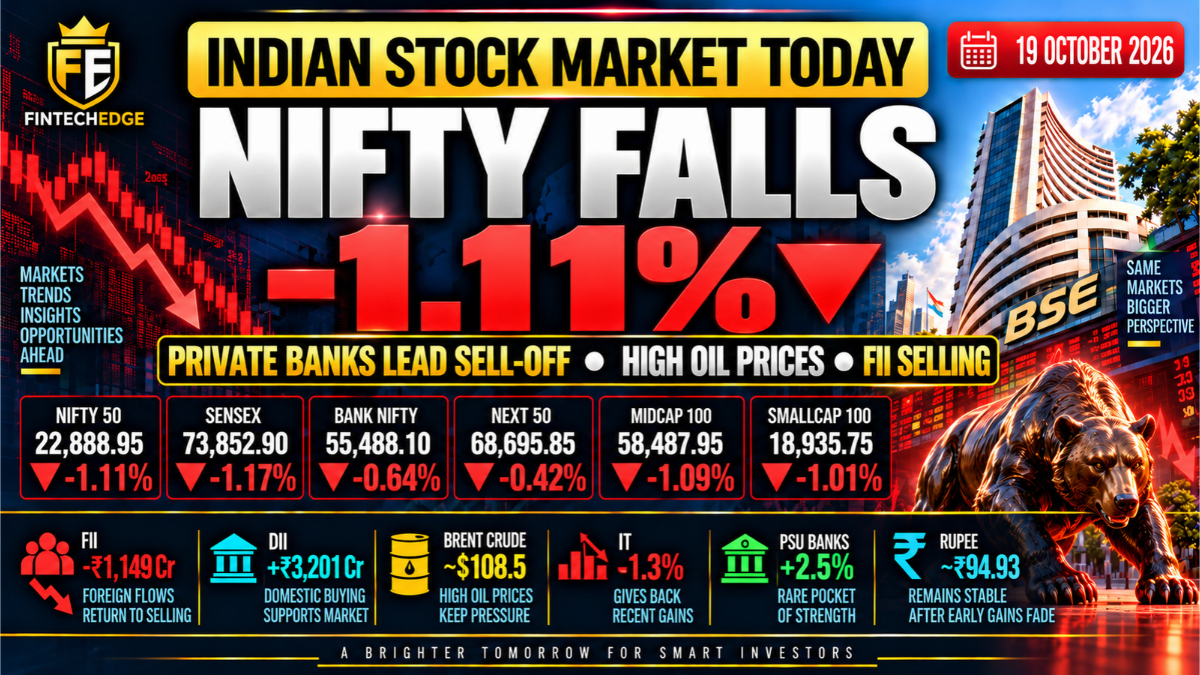
That follows the weakness seen earlier in the week, including 19 October, when private banks were among the main drags.
Still, today’s decline should not be interpreted as a long-term sector call.
It simply shows that financials were another source of pressure in an already weak market.
FIIs and DIIs Both Buy Despite Weak Market
Institutional activity produced one of the most interesting contradictions of the day.
Your 23 October stock-segment data showed:
- FII: +₹888 crore
- DII: +₹3,235 crore
Both foreign and domestic institutions were therefore net buyers.
That is important because a sharp market fall is often automatically attributed to institutional selling.
Today’s data do not support that explanation.
Institutional buying was not enough to prevent the broader market from falling sharply.
At the same time, one positive FII session should not be interpreted as a structural return of foreign capital.
October cumulative FII flows remain negative.
The useful conclusion is narrower:
Institutional stock-market flows were positive on the day, but broader selling pressure remained strong enough to overwhelm that support.
Benchmarks End a Difficult Week Lower
The weekly numbers put today’s weakness into better perspective.
The Nifty lost roughly 2.4% for the week, while the Sensex fell about 2.2%.
But the damage in smaller stocks was much larger:
- Smallcaps: about -7.3%
- Midcaps: about -5.6%
These were their weakest weekly performances in around 20 months.
That makes the large-cap versus broader-market divergence a weekly story, not simply a one-day anomaly.
Smallcaps and midcaps fell more than twice as much as the benchmark indices.
This does not tell us where they go next.
But it clearly shows where this week’s pressure was concentrated.
Rupee Loses Some Recent Momentum
The rupee also lost some of the improvement seen earlier in the week.
Rising crude prices reduced the benefit of recent supportive flows and increased concerns around India’s import bill.
This relationship is important because oil imports require dollar payments. When crude rises sharply, importer demand for dollars can increase and create additional pressure on the currency.
The rupee had benefited recently from IPO-linked inflows and RBI measures, but elevated oil has made that backdrop more difficult again.
Global Tech Sentiment Remains Fragile
Global technology markets also remained volatile.
Recent selling in semiconductor and AI-linked stocks has raised questions about valuations and crowded positioning.
But it would be too strong to say the AI trade has permanently broken.
Recent sessions have shown sharp moves in both directions.
For Indian investors, the more important point is that weak global risk sentiment can affect:
- foreign portfolio flows;
- valuations;
- emerging-market currencies;
- and domestic technology stocks.
That global backdrop adds another layer of uncertainty to an already difficult domestic market.
Jio IPO May Have Added to Liquidity Pressure
The Jio Platforms IPO remained one of the largest capital-market events in focus.
The issue attracted very strong demand and was reportedly subscribed 13.8 times.
Some market participants have suggested that such a large offering may temporarily absorb liquidity that might otherwise have remained in the secondary market.
That is possible, but it should not be overstated.
The evidence does not establish that the IPO caused today’s sell-off.
Oil, financial weakness and broader-market pressure were more clearly visible drivers.
Stock-Specific Moves Remain Sharp
Several individual stocks continued to experience unusually large moves.
Swiggy fell sharply to a record low, while Colgate-Palmolive India declined after its quarterly profit missed expectations.
Large moves in individual companies have become increasingly common during this period of weak market breadth.
That is another reason why the headline Nifty number alone can understate the actual volatility experienced by investors.
What to Watch Next
Brent crude
Oil near $115 remains the biggest macro variable. Further escalation would increase pressure on inflation, the rupee and corporate margins.
Smallcaps and midcaps
The broader market has now materially underperformed for several sessions. Whether that gap begins to narrow will be important.
Bank Nifty
Financials weakened again today. Stabilisation in large banks would help the headline indices.
Institutional flows
Both FIIs and DIIs were buyers today. Whether those inflows continue will matter more than one isolated session.
Rupee
The currency has lost some recent momentum as oil moved higher.
Global technology stocks
Further volatility in AI and semiconductor shares could continue influencing global risk appetite.
FintechEdge View
The Indian stock market today again demonstrated why the Nifty alone can give an incomplete picture.
The headline index fell just 0.39%, but the Smallcap 100 lost 2.94%, Midcap 100 fell 2.21%, and Next 50 dropped 2.25%.
That divergence has now persisted through several sessions and became even clearer over the full week.
Oil near $115 is the most important macro pressure, while weaker financials added another drag.
At the same time, both FIIs and DIIs were net buyers, showing that daily flow data alone cannot explain every market move.
The clearest conclusion from this week is that the larger benchmarks have been relatively resilient, while the real stress has been concentrated in the broader market.
Whether that gap begins to close will be one of the most important signals to watch next.
Sources & References
- Indian shares finish week lower as high oil prices and broader-market weakness weigh Reuters
- Oil trades near five-month high as Middle East supply concerns persist Reuters
- Rupee recovery faces renewed pressure from rising crude oil Reuters
- Global markets remain volatile as technology selling and high oil weigh Reuters
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.