Indian Stock Market Today: Nifty Tops 25,000 as Banks Lead Seventh-Day Rally
Quick Summary
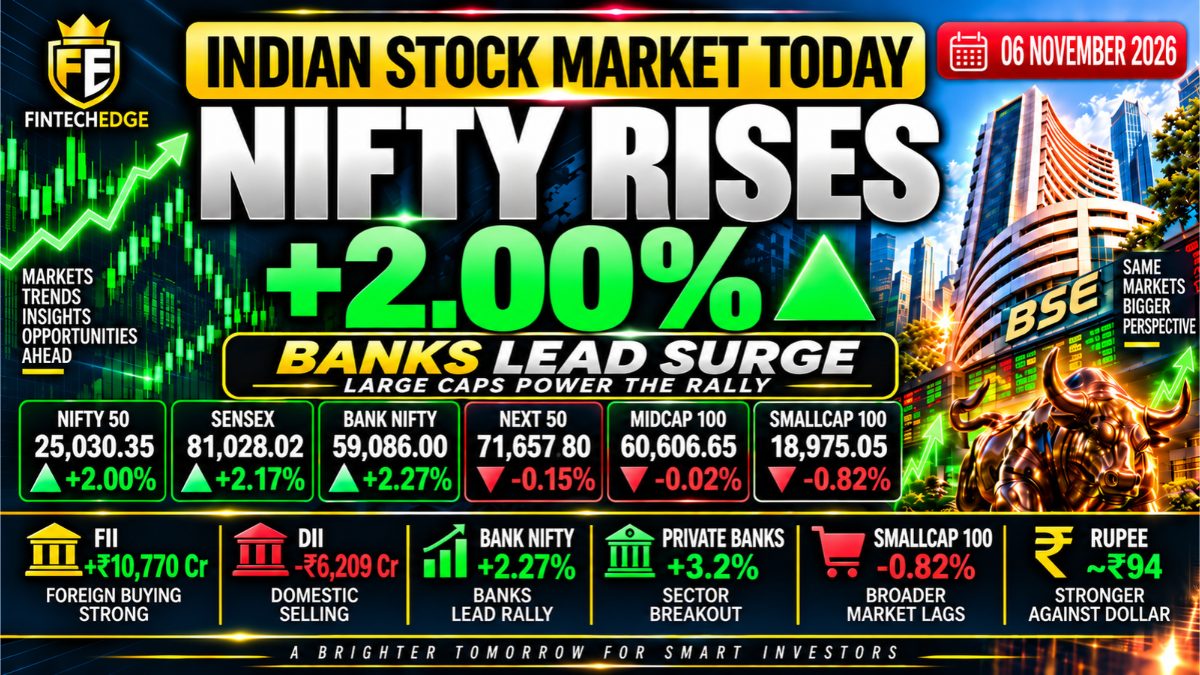
- Nifty 50 rose 2.01% to 25,030.35, while Sensex gained 2.17% to 81,028.02.
- The benchmarks extended their winning streak to seven consecutive sessions and closed at their highest levels in more than eight months.
- Nifty gained 8.6% for the week and Sensex rose 8.8%, their strongest weekly advances since February 2021.
- Bank Nifty advanced 2.27%, continuing to lead the large-cap rally.
- FIIs bought ₹10,769.84 crore, while DIIs sold ₹6,208.91 crore in the capital-market segment.
- Broader participation weakened, with Next 50 down 0.15%, Midcap 100 down 0.02%, and Smallcap 100 down 0.82%.
- Brent crude fell sharply during the week, while the rupee strengthened to around ₹93.9050 per dollar.
Indian Market Performance — 6 November 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian stock market today extended its remarkable recovery on 6 November 2026, with the Nifty 50 rising 2.01% to 25,030.35 and the Sensex gaining 2.17% to 81,028.02. Bank Nifty climbed another 2.27%, supported by strong buying in heavyweight financial stocks, while renewed foreign inflows and sharply lower crude oil continued to improve the domestic market backdrop.
The benchmarks have now risen for seven consecutive sessions and closed at their highest levels in more than eight months. The Nifty gained 8.6% for the week and the Sensex 8.8%, their strongest weekly advances since February 2021. But beneath those impressive headline numbers, the market was much less uniform: the Next 50 and Midcap 100 ended marginally lower, while the Smallcap 100 fell 0.82%.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 25,030.35 | +2.01% |
| Sensex | 81,028.02 | +2.17% |
| Bank Nifty | 59,086.00 | +2.27% |
| Nifty Next 50 | 71,657.80 | -0.15% |
| Nifty Midcap 100 | 60,606.65 | -0.02% |
| Nifty Smallcap 100 | 18,975.05 | -0.82% |
The headline indices were exceptionally strong, but the broader market told a different story.
Large-cap and banking stocks continued to attract aggressive buying, while smaller companies failed to participate. That divergence is the most important counterbalance to today’s bullish headline.
Nifty Closes Above 25,000
The Nifty closed above 25,000 for the first time in several months, ending at 25,030.35, its highest close in more than eight months.
The milestone marks a major recovery from the weakness seen during the second half of October.
Only a little over a week ago, the market was dealing with falling smallcaps, elevated crude oil, persistent foreign selling and concerns around global yields. Since then, the environment has changed quickly.
The benchmark has now advanced for seven straight sessions.
That does not make 25,000 a technical signal by itself. Round numbers attract attention because they are psychologically important and easy to remember, but they do not determine what happens next.
What matters more is how the rally has been built: foreign flows have improved, crude oil has fallen sharply, the rupee has strengthened, and heavyweight banks have moved from laggards to market leaders.
Best Week Since 2021
The weekly performance was even more striking than today’s move.
The Nifty gained 8.6% during the week, while the Sensex climbed 8.8%, marking their strongest weekly advances since February 2021.
This is no longer simply a one- or two-session relief bounce.
The recovery began building around the end of October, strengthened on 2 November as Reliance and lower crude supported the market, and accelerated further as banks and foreign investors joined the move.
By 5 November, the Nifty had already recorded its strongest single-day gain in seven months.
Today extended that move.
Still, the size of the rebound should be viewed with discipline.
An 8%+ weekly advance is large. It shows that sentiment and flows have improved sharply, but it does not establish that the earlier correction is permanently over or that another uninterrupted rally will follow.
Banks Continue to Lead
Bank Nifty rose another 2.27%, again outperforming the Nifty.
Financials gained about 10.4% for the week, while HDFC Bank and ICICI Bank recorded their strongest weekly performances in roughly six years.
This represents one of the biggest leadership changes in the market over the past two weeks.
At the end of October, banks often lagged even when the Nifty rose.
Now they are among the strongest parts of the market.
Because banking and financial stocks carry heavy weight in both the Nifty and Sensex, their strength has had a direct impact on benchmark performance.
The pattern has become clearer over the past several sessions. On 3 November, Bank Nifty was already participating more strongly. By 5 and 6 November, banks had become one of the main drivers of the entire rally.
FIIs Buy ₹10,769.84 Crore
Foreign investors remained aggressive buyers.
Official NSE data for 6 November showed:
- FII/FPI net buying: ₹10,769.84 crore
- DII net selling: ₹6,208.91 crore
Foreign investors bought nearly $3 billion of Indian equities during the week, including approximately $1.6 billion on Thursday.
This is one of the clearest changes in market structure compared with October.
For much of last month:
- FIIs were selling;
- DIIs were absorbing those flows;
- large-cap sentiment remained weak.
This week, that pattern reversed.
Foreign investors have become strong buyers, while domestic institutions have been net sellers.
The direction of FII flows matters because foreign money tends to be concentrated heavily in large, liquid stocks—precisely the segment that has performed best during the recent rally.
But one week of aggressive buying should not be extrapolated indefinitely.
The correct conclusion is that foreign participation has changed materially in the short term, not that India has entered a permanent period of FII inflows.
Large Caps Rally While Smallcaps Fall
This was the most important internal divergence today.
The Nifty rose 2.01%.
Bank Nifty gained 2.27%.
But:
- Next 50 fell 0.15%
- Midcap 100 slipped 0.02%
- Smallcap 100 dropped 0.82%
That means the rally remained powerful at the benchmark level but narrowed underneath.
This is almost the opposite of 4 November, when smallcaps and midcaps substantially outperformed the Nifty.
Leadership has rotated quickly.
Earlier this week:
- broader markets led;
- then banks strengthened;
- today the biggest gains were concentrated in large caps and heavyweight financials.
For investors, that distinction matters.
A portfolio concentrated in Nifty large caps may have enjoyed another very strong session. A smallcap-heavy portfolio may have experienced a negative day despite the Nifty crossing 25,000.
That is why benchmark performance alone never tells the complete story.
India Defies Global Tech Rout
India’s performance was especially striking because it came during a severe selloff in global technology markets.
The Nasdaq Composite fell 5.5%, while the Nasdaq 100 dropped 6.4%. Roughly $2.5 trillion to $3 trillion in market value was erased across major US equities, while technology-heavy markets in South Korea, Japan and Taiwan also fell sharply.
India behaved very differently.
One reason is structural.
India has relatively less direct exposure to the capital-intensive AI infrastructure trade that dominates several global technology-heavy markets.
That may partly explain why Indian large caps were able to attract capital even as semiconductor and AI-linked stocks elsewhere came under pressure.
But this needs careful wording.
It would be too strong to claim that India has become an “anti-AI trade” or that all capital leaving global technology is automatically moving into India.
The verified evidence supports a narrower conclusion:
India’s market behaved differently from AI- and semiconductor-heavy global markets, while foreign allocations to Indian large caps increased.
That is significant without overstating the cause.
Lower Oil Supports the Macro Backdrop
Crude oil has become another major tailwind.
Brent fell nearly 20% during the week, sharply reducing one of the main pressures on Indian assets.
This matters because India imports most of its crude requirements.
Lower oil can help:
- reduce imported inflation;
- improve the trade balance;
- reduce pressure on the current account;
- lower dollar demand from oil importers;
- improve margins for fuel-sensitive companies;
- and support the rupee.
This is a dramatic change from late October, when crude prices above $110 were one of the largest macro concerns for India.
Lower crude does not guarantee equity gains.
But it materially improves the environment in which Indian companies and policymakers operate.
Rupee Strengthens Below ₹94
The rupee closed at ₹93.9050 per dollar, its strongest level since 22 April, and gained about 1.1% during the week.
The currency has benefited from the same factors helping equities:
- lower crude oil;
- renewed FII buying;
- and improved relative sentiment toward Indian assets.
The move below ₹94 is important after the currency weakness seen earlier in the year.
A firmer rupee can reduce imported inflation pressure and improve foreign-investor confidence.
As with equities, however, the pace of the recent move should not be extrapolated automatically.
The rupee remains sensitive to oil, global yields, the dollar and capital flows.
Sector Leadership Remains Concentrated
Banks remained the strongest large sector.
Other sector moves were more moderate:
- Bank Nifty: +2.27%
- Consumer Durables: about +1.78%
- Metals: about +0.79%
- Autos: about +0.76%
- Oil & Gas: about +0.69%
- IT: about +0.43%
- Capital Goods: about -1.36%
So while headline indices surged more than 2%, the entire market was not moving at that pace.
Banks and selected large caps did most of the heavy lifting.
Reports around possible changes to equity taxation also remained in the background, but no confirmed policy change has been announced. Until that changes, tax-relief expectations should remain a secondary sentiment factor rather than a core market driver.
What to Watch Next
FII flows
Foreign investors bought ₹10,769.84 crore today and nearly $3 billion during the week. Whether this buying persists is one of the most important variables for large caps.
Broader-market participation
The Next 50, midcaps and smallcaps all lagged today. A more balanced rally would require broader participation to return.
Banks
Banks have moved from laggards to leaders within days. Their performance will remain crucial because of their heavy benchmark weight.
Global technology selloff
India has so far held up exceptionally well relative to global technology-heavy markets. Whether that divergence persists will be important.
Crude oil
The near-20% weekly decline in Brent has materially improved India’s macro backdrop.
Rupee
The currency has strengthened below ₹94. Continued stability would reinforce the improvement in India’s external environment.
FintechEdge View
The Indian stock market today completed an exceptional week.
The Nifty closed above 25,000, Bank Nifty continued to outperform, foreign investors remained aggressive buyers, crude oil fell sharply and the rupee strengthened below ₹94.
Those are meaningful improvements.
The Nifty’s 8.6% weekly gain and the Sensex’s 8.8% advance also confirm that this has become far more than a routine two-day rebound.
But today introduced an important warning beneath the headline.
The Next 50 fell, midcaps were almost flat and smallcaps dropped 0.82%.
So the strongest conclusion is not simply that the entire Indian market is surging.
It is that a powerful large-cap and banking rally is being supported by renewed foreign buying and a much better macro backdrop, while broader-market participation has started to narrow again.
That distinction will be important when the market reopens next week.
Sources & References
- Indian stocks buck global tech rout, post best week in six years — Reuters
- Rupee draws support from returning foreign flows amid global tech meltdown — Reuters
- FII/FPI & DII trading activity in Capital Market segment — NSE India
- Nifty 50 and broader Indian market index data — NSE India
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.