Indian Stock Market Today: Nifty Rises 1.30% as IT Stocks Lead Rebound
Quick Summary
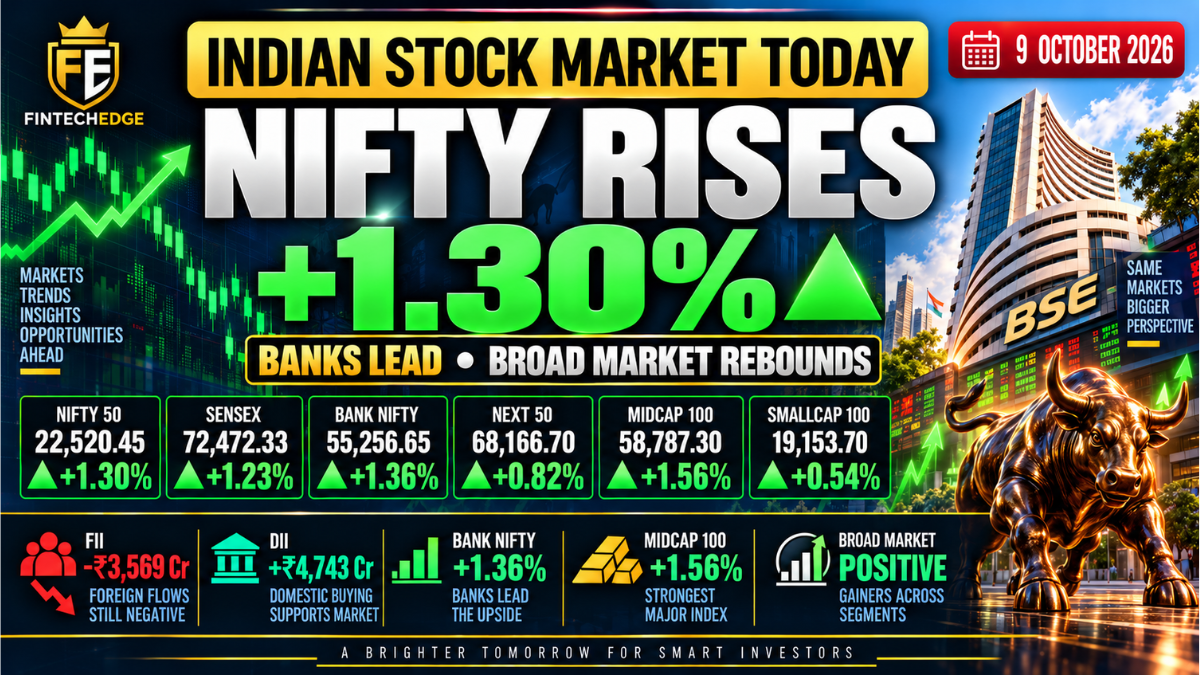
- Nifty 50 rose 1.30% to 22,520.45, while Sensex gained 1.23% to 72,472.33.
- Bank Nifty gained 1.36% and Midcap 100 rose 1.56%, both outperforming the Nifty.
- IT stocks led the rebound after TCS earnings, with the Nifty IT index gaining about 3.02%.
- Oil prices eased and the US 10-year Treasury yield retreated to around 5.29%.
- FIIs sold ₹3,569 crore, sharply lower than the previous session’s outflow, while DIIs bought ₹4,743 crore.
- Smallcap 100 gained 0.54%, but lagged the benchmark, banks and midcaps.
- Nifty and Sensex ended an eight-week losing streak, their longest in 25 years.
Indian Market Performance — 9 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
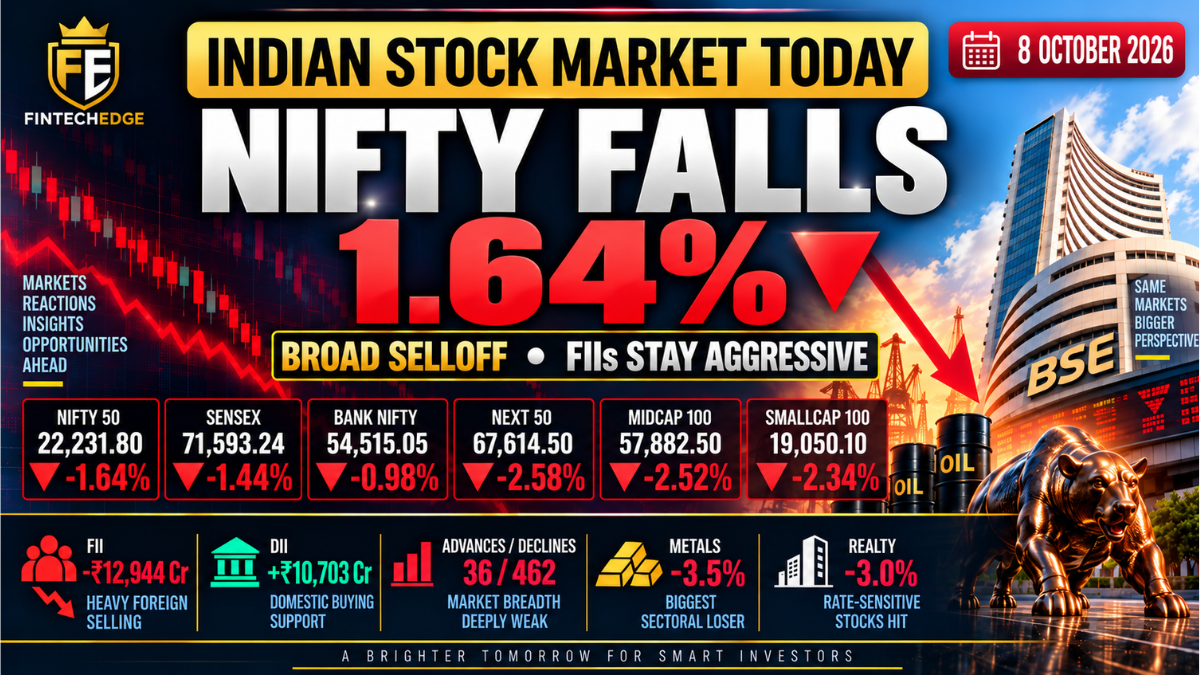
Indian equities rebounded strongly on 9 October 2026, with the Nifty 50 rising 1.30% to 22,520.45 and the Sensex gaining 1.23% to 72,472.33, recovering part of the losses from the previous session’s broad sell-off.
The strongest support came from IT after TCS earnings reassured investors on margins and AI-linked growth. Softer oil prices and easing US Treasury yields also reduced some of the macro pressure that had built earlier in the week, while banks and midcaps participated in the recovery.
Foreign investors remained net sellers, but the scale of outflows fell sharply from the previous session. The rebound was also enough to end an eight-week losing streak, the longest weekly decline for the benchmarks in 25 years.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,520.45 | +1.30% |
| Sensex | 72,472.33 | +1.23% |
| Bank Nifty | 55,256.65 | +1.36% |
| Nifty Next 50 | 68,166.70 | +0.82% |
| Nifty Midcap 100 | 58,787.30 | +1.56% |
| Nifty Smallcap 100 | 19,153.70 | +0.54% |
The recovery was broad, but leadership was uneven.
Midcaps and banks outperformed the Nifty, while smallcaps finished positive but lagged the rest of the market.
IT Stocks Lead After TCS Earnings
IT was the clearest stock-market driver of the session.
Reuters reported that TCS rose 3.85% after maintaining stable operating margins despite higher AI investments, while annualised AI-related revenue rose 20% quarter-on-quarter to $3.1 billion. The Nifty IT index gained about 3.02%, its best session in six weeks.
That helped improve sentiment toward the sector after a weak stretch.
The key takeaway is not that one result changes the entire IT outlook, but that TCS delivered enough reassurance on margins and AI-linked growth to trigger a meaningful sector rebound.
Reuters also reported that the recent US suspension of the PERM programme is not expected to materially affect Indian IT companies in the near term, although longer-term regulatory uncertainty remains.
Oil Prices Ease
Oil prices eased on Friday, giving Indian equities some macro relief.
For India, softer oil matters because it can reduce pressure on:
- inflation;
- the import bill;
- the current account;
- the rupee;
- and domestic rate expectations.
This was a meaningful change from the previous session, when Brent crude above $103 was one of the main pressures on the market.
That does not mean the oil risk has disappeared. Prices remain volatile, and geopolitical developments can quickly change the picture.
But for today, lower oil removed one important headwind.
US Treasury Yields Retreat
US Treasury yields also eased.
The US 10-year yield was around 5.29%, below the previous week’s peak near 5.34%.
That matters because high US yields can pull capital toward dollar assets, pressure emerging-market currencies and weigh on equity valuations.
The retreat therefore reduced some pressure on global risk assets.
Still, yields remain near multi-decade highs, so this should be viewed as relief rather than evidence that the global rate problem has ended.
FIIs Still Sell, but Outflows Slow Sharply
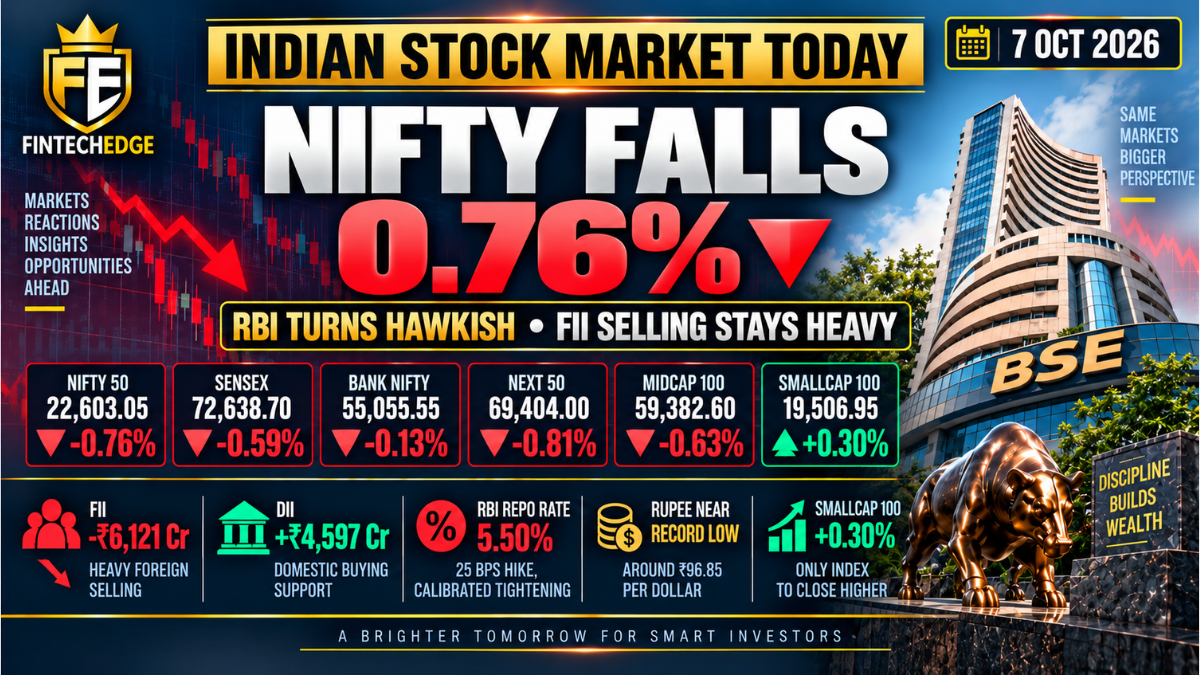
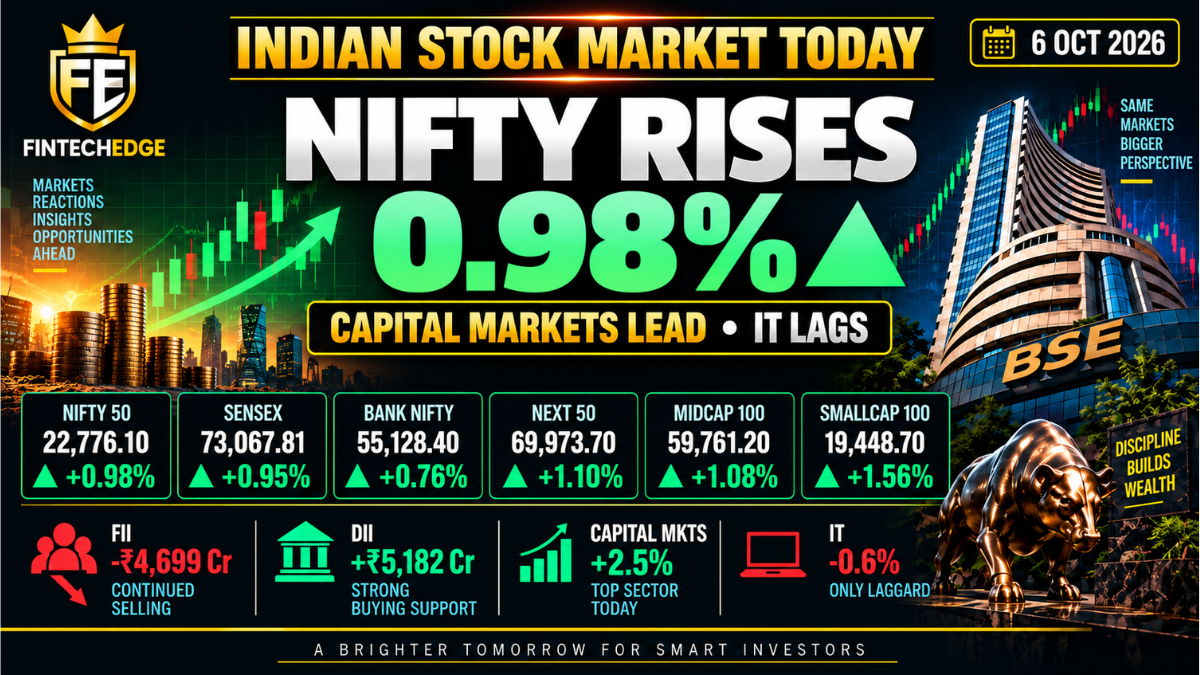
Institutional flows improved meaningfully compared with the previous session. This also contrasts with the RBI-driven weakness seen on 7 October, when policy tightening and currency pressure were dominant themes.
Your 9 October stock-segment data showed:
- FII: -₹3,569 crore
- DII: +₹4,743 crore
The important part is the change in intensity.
On 8 October, FIIs sold ₹12,944 crore. Today’s outflow was much smaller.
That does not mean foreign selling has ended, but it does reduce one of the pressures that had weighed heavily on the market earlier in the week.
Domestic institutions also remained supportive.
Banks and Midcaps Strengthen the Rebound
The recovery was not limited to IT.
Bank Nifty gained 1.36%, while the Midcap 100 rose 1.56%, both outperforming the Nifty 50.
This added breadth to the rebound.
Banks matter because of their heavy weight in the headline indices, while midcap outperformance suggests buying interest extended beyond the largest companies.
The Nifty Next 50 also gained 0.82%, confirming that the recovery spread across multiple parts of the market.
Smallcaps Lag Despite Positive Close
Smallcaps also finished higher, but they were the weakest of the six tracked indices.
The Smallcap 100 gained 0.54%, compared with:
- Midcap 100: +1.56%
- Bank Nifty: +1.36%
- Nifty 50: +1.30%
- Sensex: +1.23%
This matters because it shows risk appetite improved without becoming uniformly aggressive.
Today’s move was broad, but not every part of the market participated equally.
Rupee Stabilises, but Weekly Pressure Remains
The rupee ended roughly flat on Friday but still posted a weekly decline despite the RBI’s rate hike.
That is a secondary point today, but it remains important.
Currency pressure has not disappeared, and the rupee continues to reflect the same external forces affecting equities: oil prices, global yields and foreign flows.
The stabilisation is therefore useful, but it does not yet signal a meaningful change in the broader currency trend.
Eight-Week Losing Streak Ends
One of the most notable developments came at the weekly level.
Reuters reported that the Nifty and Sensex ended their longest weekly losing streak in 25 years.
The Nifty gained about 0.4% for the week, while the Sensex rose about 0.8%, ending an eight-week run of declines.
This is a meaningful milestone.
But it should be interpreted carefully.
One positive week does not confirm that the broader correction has ended. It simply marks the first weekly gain after a prolonged stretch of weakness. The positive weekly close also marks a change from the market weakness seen on 1 October, when global yields, foreign selling and macro pressure weighed on equities.
What to Watch Next
US inflation data
Upcoming US inflation data will be important because a stronger-than-expected reading could push Treasury yields higher again and pressure risk assets.
Oil prices
Oil eased today, but volatility remains high. A renewed rise would bring inflation and currency concerns back into focus.
US Treasury yields
Yields retreated but remain elevated. Their direction will continue to matter for emerging-market flows.
FII activity
Foreign selling slowed sharply today. Whether that continues will be one of the most important near-term market signals.
IT earnings
TCS helped lift the sector. The next set of IT earnings will show whether that strength can broaden.
Market breadth
Banks and midcaps led today, while smallcaps lagged. Whether the recovery becomes more balanced will be worth watching.
FintechEdge View
The Indian stock market today delivered a much better session than the previous day’s sell-off.
The rebound had several supports: TCS earnings improved sentiment in IT, oil prices eased, US Treasury yields softened, and FII selling slowed sharply.
Banks and midcaps also participated, which gave the move more breadth than a purely sector-led rebound.
The end of the eight-week losing streak is important, but it should not be treated as proof that the correction is over.
Oil, global yields, foreign flows and the rupee remain active risks, while upcoming US inflation data could quickly change the macro backdrop again.
For now, the most useful conclusion is that market pressure eased meaningfully today, but the durability of the rebound still depends on whether those external and flow-related headwinds continue to improve.
Sources & References
- TCS rises as investors welcome stable margins and AI-linked growth Reuters
- Global markets recover as oil and bond yields ease Reuters
- US 10-year Treasury yield eases from recent peak Reuters
- Indian shares rebound and end eight-week losing streak Reuters
- Rupee stabilises on the day but remains weak on the week Reuters
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.