Indian Stock Market Today: Nifty Jumps 1.60% as IT Stocks Lead Rally
Quick Summary
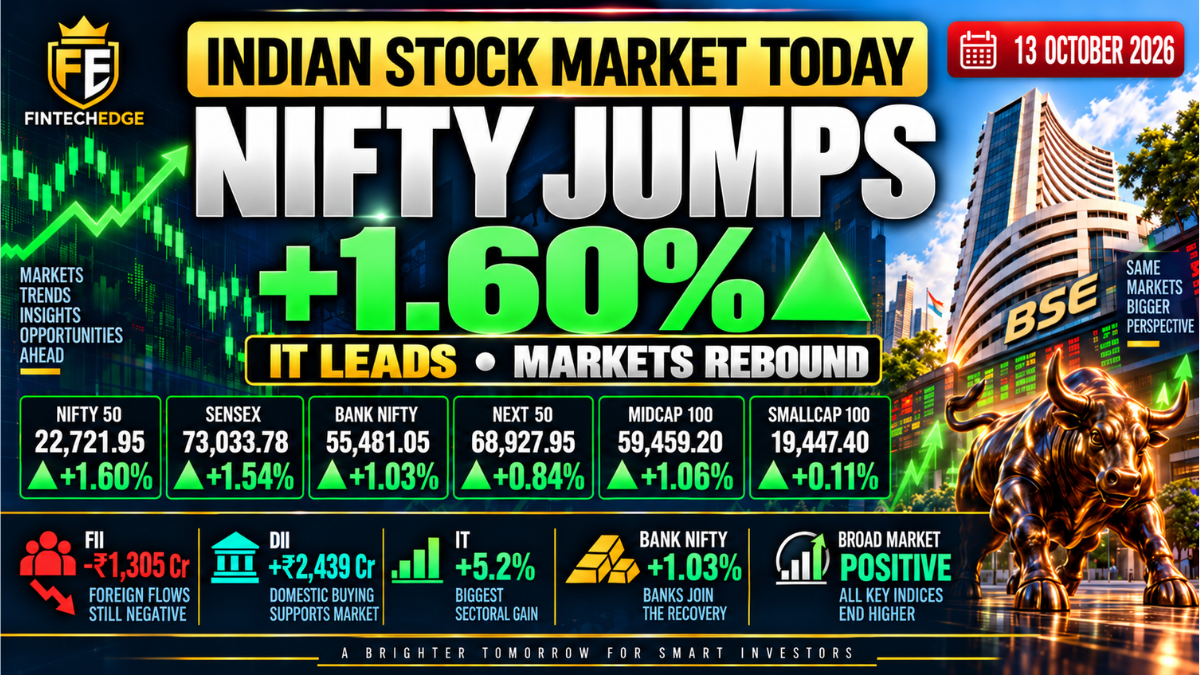
- Nifty 50 rose 1.60% to 22,721.95, while Sensex gained 1.54% to 73,033.78.
- Nifty IT surged 5.2%, led by strong gains in HCLTech and TCS.
- Bank Nifty gained 1.03% and Midcap 100 rose 1.06%, adding breadth to the rally.
- Nifty Next 50 advanced 0.84%, while Smallcap 100 lagged with a 0.11% gain.
- FIIs sold ₹1,305 crore, while DIIs bought ₹2,439 crore in the stock segment.
- The rupee strengthened to around ₹95.28 per dollar, reducing some immediate currency pressure.
- US Treasury yields eased somewhat but remained near multi-decade highs.
Indian Market Performance — 13 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian equities rebounded sharply on 13 October 2026, with the Nifty 50 rising 1.60% to 22,721.95 and the Sensex gaining 1.54% to 73,033.78.
The strongest driver was IT. The Nifty IT index surged 5.2%, its best session in more than 17 months, after encouraging earnings from HCLTech. TCS also contributed strongly, while banks and midcaps participated in the recovery.
The rebound was broader than a one-sector move, but participation was not uniform. Smallcaps barely advanced, FIIs remained net sellers, and domestic institutions once again provided support.
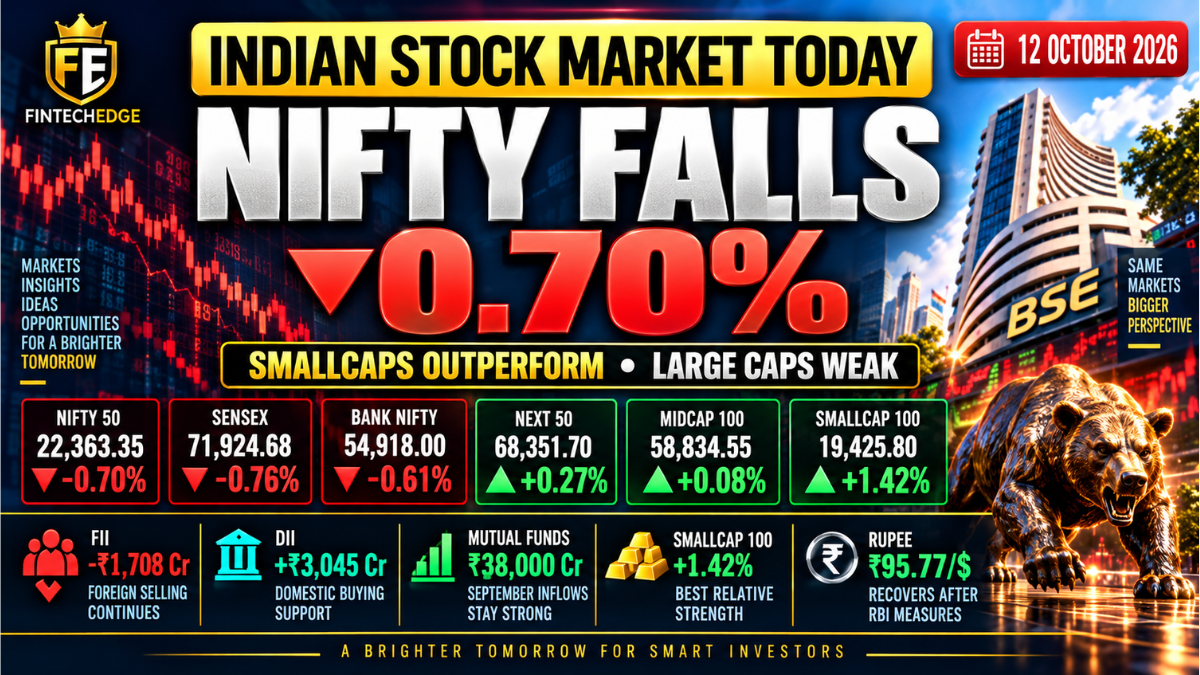
The move also came after the split market seen on 12 October, when headline indices fell even as smallcaps outperformed.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,721.95 | +1.60% |
| Sensex | 73,033.78 | +1.54% |
| Bank Nifty | 55,481.05 | +1.03% |
| Nifty Next 50 | 68,927.95 | +0.84% |
| Nifty Midcap 100 | 59,459.20 | +1.06% |
| Nifty Smallcap 100 | 19,447.40 | +0.11% |
All six tracked indices finished higher, but the strength was concentrated in large caps, IT, banks and midcaps.
Smallcaps barely moved, which makes today’s rally strong but not uniformly broad.
IT Stocks Lead After HCLTech Earnings
IT was the clearest driver of the session.
Reuters reported that the Nifty IT index jumped 5.2%, its strongest session in more than 17 months.
HCLTech gained 8.4%, its biggest one-day rise in more than six years, after earnings showed better profitability metrics. TCS also rose 6.8%, adding further support to the sector.
The move matters because IT companies carry significant weight in the Nifty and Sensex. A sharp rally in large technology names can therefore have a meaningful impact on the benchmark indices.
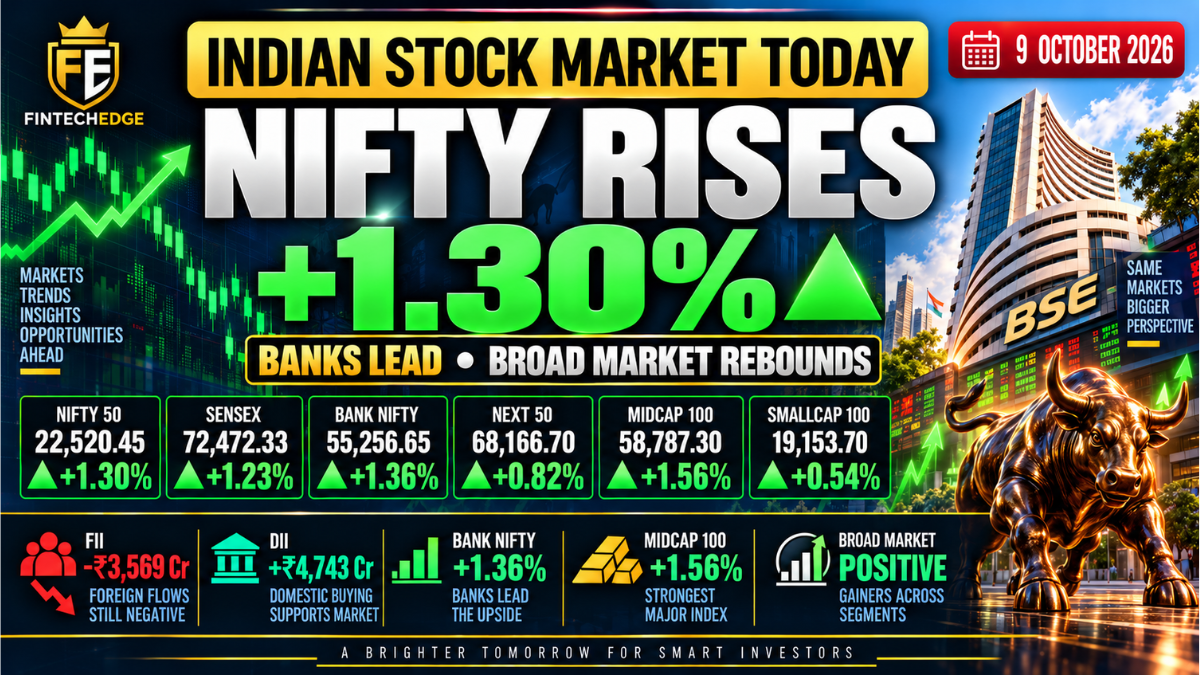
Today’s move also follows the IT-led rebound seen on 9 October, when TCS earnings had already improved sentiment toward the sector.
Still, one strong session does not confirm that IT has formed a lasting bottom.
The more defensible conclusion is that earnings from major companies have improved sentiment toward a sector that had been under significant pressure.
Banks and Midcaps Add Breadth
The rally was not limited to IT.
Bank Nifty gained 1.03%, while the Midcap 100 rose 1.06%. The Nifty Next 50 also advanced 0.84%.
That helped broaden the recovery beyond technology stocks.
Banks matter because of their large weight in the benchmark indices, while midcap participation suggests buying extended beyond the largest companies.
This makes today’s rebound stronger than a rally driven entirely by a few IT heavyweights.
However, the difference between large-cap strength and smallcap weakness shows that risk appetite was still selective.
Smallcaps Lag Despite Positive Close
Smallcaps were the weakest segment among the six indices tracked by FintechEdge.
The Smallcap 100 gained only 0.11%, compared with:
- Nifty 50: +1.60%
- Sensex: +1.54%
- Midcap 100: +1.06%
- Bank Nifty: +1.03%
This is an important divergence.
All major indices finished higher, but smaller companies did not participate with the same intensity.
That makes it inaccurate to describe the session as a uniformly strong risk-on move.
A better interpretation is:
Large caps, IT, banks and midcaps led the rebound, while smallcaps remained relatively subdued.
FIIs Sell ₹1,305 Crore, DIIs Buy ₹2,439 Crore
Institutional flows remained mixed.
Your 13 October stock-segment data showed:
- FII: -₹1,305 crore
- DII: +₹2,439 crore
FIIs therefore remained net sellers, while domestic institutions once again provided support.
The scale of foreign selling was much smaller than during some of the heavier outflow sessions earlier this month.
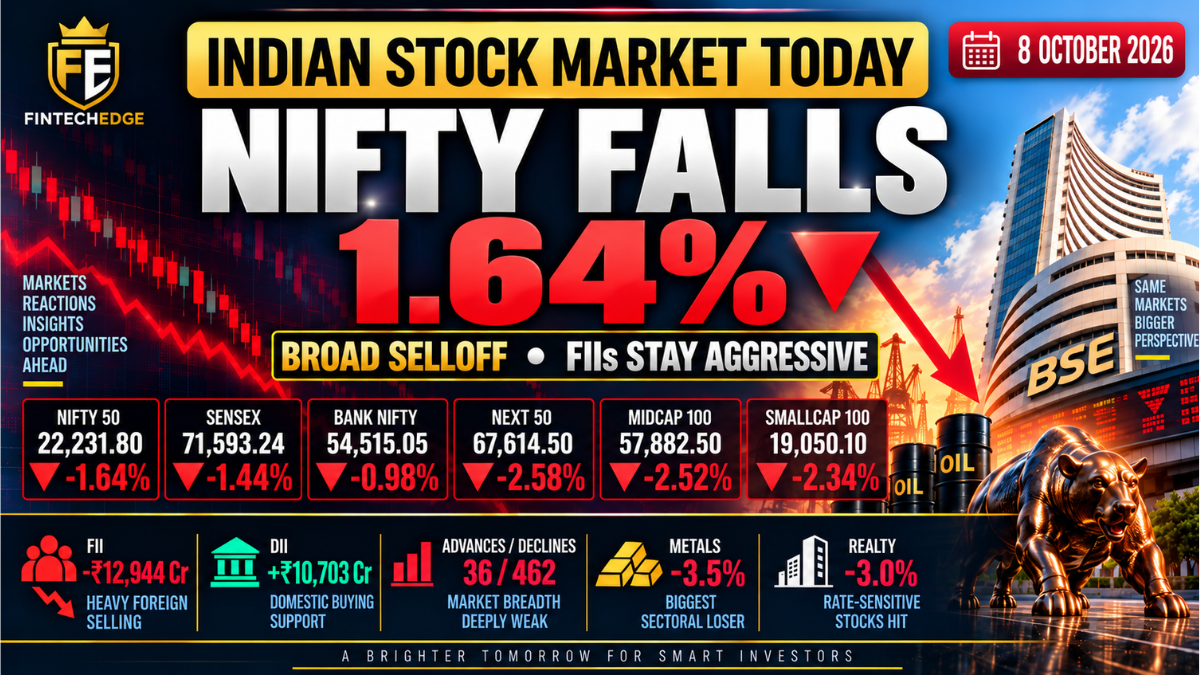
For example, FII selling reached ₹12,944 crore on 8 October.
That difference matters.
Foreign selling has not disappeared, but the current outflow is considerably more manageable than the extreme pressure seen during the sharp sell-off.
At the same time, DII buying again exceeded FII selling on the day.
That domestic support remains an important feature of the current market structure.
Rupee Strengthens Further
The rupee continued to recover.
Reuters reported the currency around ₹95.28 per dollar, supported by recent RBI measures aimed at reducing pressure in the foreign-exchange market.
That is supportive for Indian equities because currency weakness had become an important concern in recent weeks.
A stronger rupee can reduce some pressure from:
- imported inflation;
- foreign investor sentiment;
- energy imports;
- and external financing conditions.
However, the recent recovery should not be interpreted as proof that the currency problem is permanently resolved.
Oil remains elevated, foreign investors remain net sellers, and global yields are still high.
The better conclusion is that immediate currency pressure has eased.
Global Yields Ease but Remain Elevated
Some easing in US Treasury yields also helped global risk sentiment.
But the broader global rate environment remains restrictive.
Reuters reported that yields remain near multi-decade highs, while PIMCO’s Dan Ivascyn warned that the peak may still lie ahead.
That is one investor’s view rather than an established outcome, but it highlights the uncertainty around global rates.
For India, high US yields matter because they can:
- increase demand for dollar assets;
- pressure emerging-market currencies;
- reduce foreign appetite for equities;
- and weigh on valuations.
So while today’s easing provided relief, the global rate backdrop is still an important risk.
Indian IT Rallies as Global AI Stocks Stay Mixed
There was also an interesting contrast between Indian and global technology markets.
Indian IT stocks rallied strongly on company earnings, while parts of the global AI and semiconductor trade remained under pressure over concerns around valuations, profitability and rate sensitivity.
That suggests today’s Indian IT move was driven more by company-level earnings than by a broad global technology rally.
This distinction is important.
It means the strongest domestic catalyst was specific to the Indian earnings cycle rather than simply a reflection of stronger global tech markets.
Oil Remains in the Background
Oil remained an important macro variable, but it was not the main driver of today’s rally.
Global supply conditions remain uncertain, even as OPEC+ production rose in September.
For India, crude still matters because higher oil can affect:
- inflation;
- the import bill;
- the rupee;
- the current account;
- and domestic rate expectations.
But compared with IT earnings and the broad domestic rebound, oil played more of a background role today.
What to Watch Next
IT earnings
The sector led today’s rally. More earnings reports will show whether the improvement extends beyond HCLTech and TCS.
Banks and midcaps
Both participated strongly. Continued strength would make the rebound broader and more durable at the index level.
Smallcaps
Smallcaps barely moved today. Whether they begin to participate more strongly will be an important breadth signal.
FII activity
Foreign investors remain net sellers. Continued moderation in the pace of outflows would reduce a major source of pressure.
Rupee
The currency has recovered after recent RBI measures. Whether that stability continues will remain important.
US Treasury yields
Yields have eased somewhat but remain elevated. Another sharp rise could quickly bring global rate pressure back into focus.
FintechEdge View
The Indian stock market today delivered a strong rebound, but the internal structure matters.
IT was the clear catalyst, with HCLTech and TCS driving one of the sector’s strongest sessions in more than a year. Banks and midcaps also participated, which gave the rally more breadth.
But smallcaps barely moved, and FIIs remained net sellers.
That means the session was strong without being uniformly bullish across every part of the market.
The rupee’s continued recovery removed one source of pressure, while global yields eased somewhat. At the same time, the broader rate environment remains restrictive.
The most useful conclusion is therefore straightforward:
today’s rally had clear earnings and sectoral support, but confirmation of a broader improvement will require continued participation beyond IT and large caps.
Sources & References
- Indian shares rally as IT stocks surge after HCLTech earnings Reuters
- US Treasury yields may not have peaked, PIMCO investor says Reuters
- Global AI and chip stocks face renewed pressure Reuters
- OPEC+ output rises as global oil supply conditions remain unsettled Reuters
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.