Indian Stock Market Today: Nifty Holds Above 25,000 as Banks Lead
Quick Summary
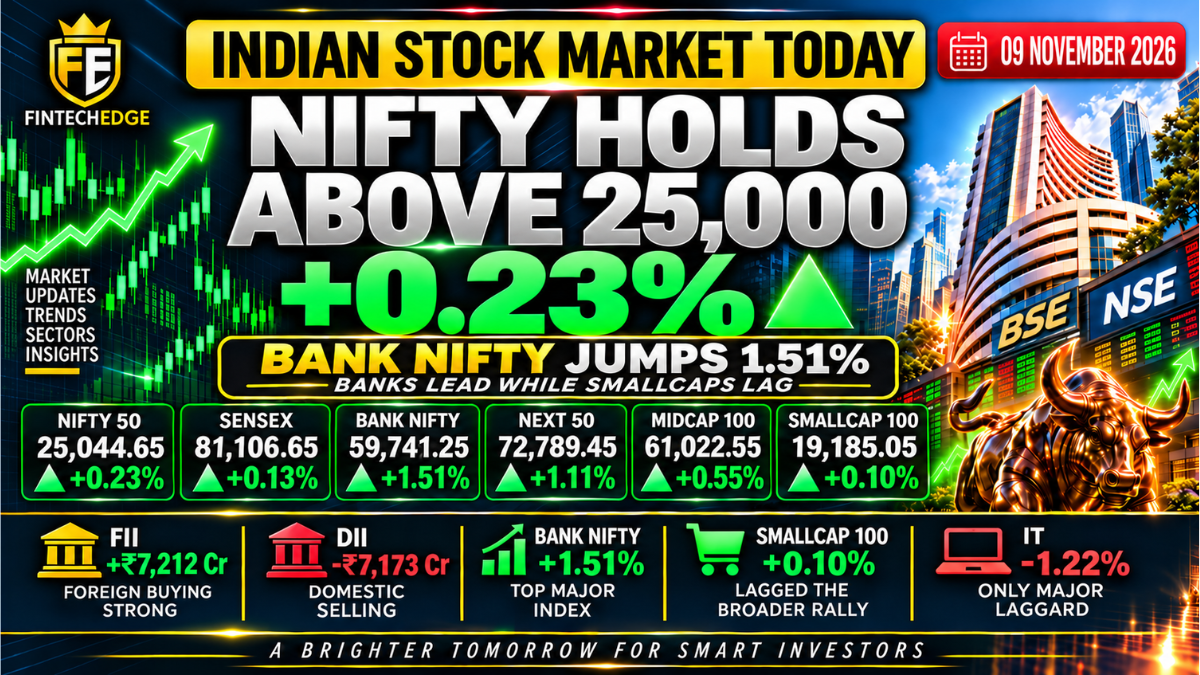
- Nifty 50 rose 0.23% to 25,044.65, while the Sensex gained 0.13% to 81,106.65.
- Bank Nifty jumped 1.51%, while Nifty Next 50 rose 1.11%, Midcap 100 gained 0.55% and Smallcap 100 added only 0.10%.
- FIIs bought ₹7,212 crore while DIIs sold around ₹7,173 crore in the cash market.
- Citi raised its end-2027 Nifty target to 28,000, HSBC upgraded India to overweight and Jefferies increased its India allocation. These remain brokerage views, not guaranteed outcomes.
- Brent crude slipped to around $97 per barrel, while pharma gained and IT remained the major weak pocket.
- Indian equity markets will remain closed on Tuesday for Diwali and reopen on Wednesday.
Indian Market Performance — 9 November 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian stock market today ended higher on 9 November 2026, with the Nifty 50 rising 0.23% to 25,044.65 and the Sensex gaining 0.13% to 81,106.65.
The headline gains were modest, but the session was far more interesting beneath the surface. Bank Nifty jumped 1.51%, the Nifty Next 50 gained 1.11% and the Midcap 100 advanced 0.55%, while smallcaps barely moved and IT stocks weakened.
Foreign institutional investors remained strong buyers, while several global brokerages also adopted a more constructive stance toward Indian equities.
However, after the sharp rally of the previous week, Monday’s session looked more like consolidation near recent highs than another broad-based surge.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 25,044.65 | +0.23% |
| Sensex | 81,106.65 | +0.13% |
| Bank Nifty | 59,741.25 | +1.51% |
| Nifty Next 50 | 72,789.45 | +1.11% |
| Nifty Midcap 100 | 61,022.55 | +0.55% |
| Nifty Smallcap 100 | 19,185.05 | +0.10% |
The difference between the indices is more important than the small positive move in the benchmarks.
Bank Nifty outperformed the Nifty 50 by more than a percentage point, while the Next 50 and midcaps also performed better than the headline index. At the same time, smallcaps lagged substantially.
That suggests Monday was not a uniformly strong market session. Leadership remained concentrated in selected pockets.
Nifty Holds Above 25,000 After Last Week’s Surge
The Nifty finished at 25,044.65, keeping the psychologically important 25,000 level after the extraordinary rally seen during the previous week.
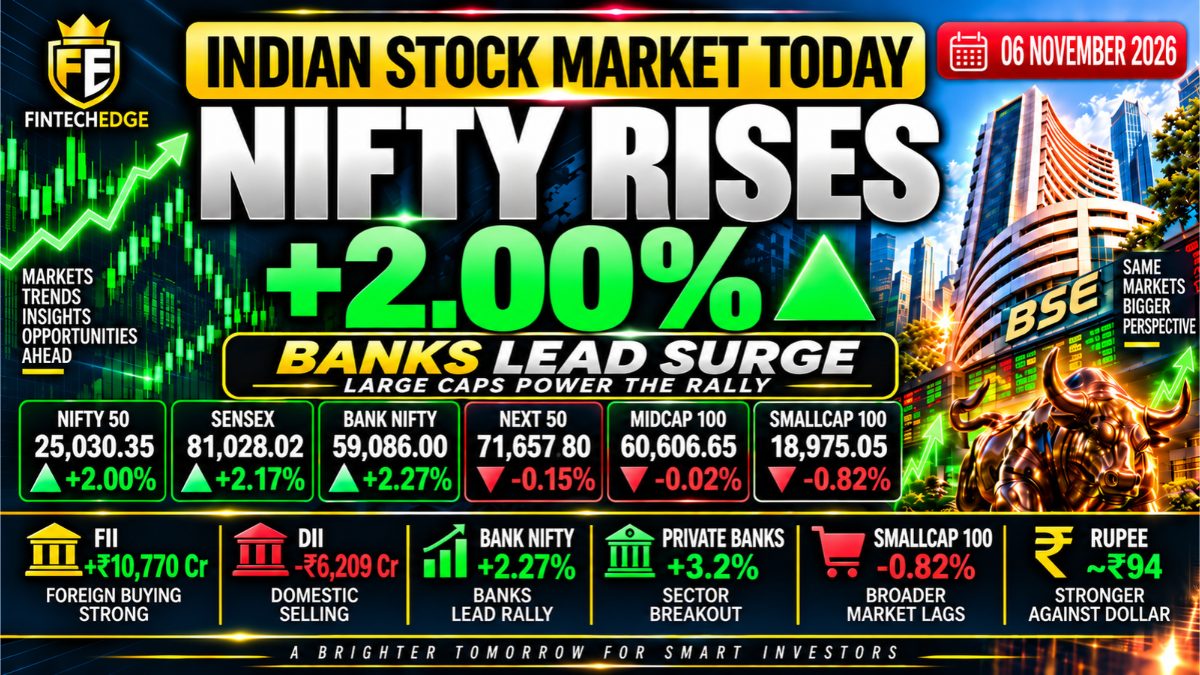
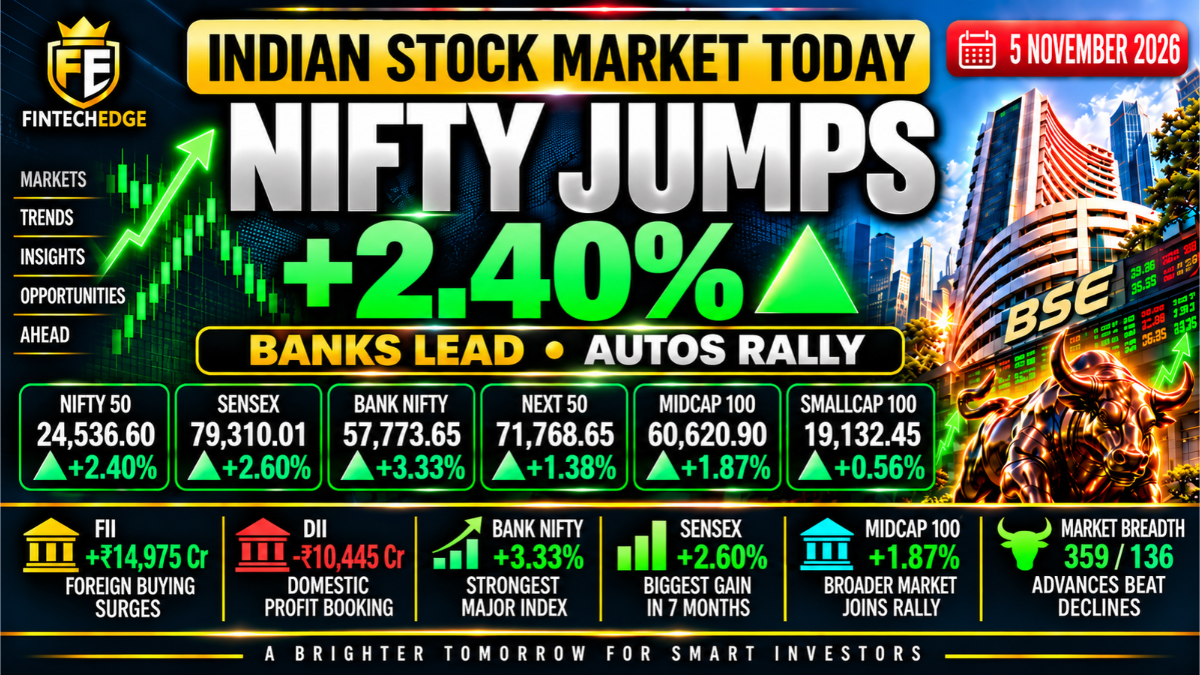
The Nifty and Sensex had climbed roughly 10.5% over seven sessions through Friday, marking their longest winning streak of the year. Monday’s close also left the major benchmarks at their strongest levels in more than eight months.
We covered the rally as it developed in our reports on the 5 November market surge and the Nifty’s 6 November close above 25,000.
Against that backdrop, Monday’s 0.23% Nifty gain is better viewed as consolidation than as another major breakout session.
The index managed to hold most of last week’s gains despite weakness in IT and mixed market breadth.
However, holding above 25,000 should not automatically be interpreted as confirmation of a fresh bull market or proof that the previous correction is permanently over.
It tells us where the index closed. It does not tell us where it will trade next.
Bank Nifty Jumps 1.51% as PSU Banks Lead
Banking stocks were the clearest source of strength.
Bank Nifty climbed 1.51% to 59,741.25, dramatically outperforming the Nifty 50’s 0.23% rise.
PSU banks were even stronger, with the Nifty PSU Bank index gaining roughly 3.7% during the session.
This matters because financial stocks carry substantial weight in India’s headline indices. Strong banking performance therefore helped the broader benchmarks remain positive even as some other heavyweight sectors struggled.
It also continues an important change in market leadership.
During parts of the earlier rebound, banks had lagged. More recently, they have moved toward the front of the rally.
For investors and traders, the key question is therefore not simply whether the Nifty remains above 25,000, but whether banking leadership can remain durable.
The sharp move in PSU banks should still be treated carefully. A strong single-day percentage gain does not by itself establish a longer-term trend.
FIIs Buy ₹7,212 Crore
Foreign institutional investors remained significant buyers in the Indian equity market.
FIIs purchased approximately ₹7,212 crore in the cash market on Monday, while domestic institutional investors sold roughly ₹7,173 crore.
The two numbers were almost equal in size.
November has therefore produced a very different institutional-flow picture from October.
Foreign investors have bought roughly ₹53,000 crore in the stock segment so far during November, while domestic institutions have been net sellers.
This represents a notable reversal from October, when foreign investors were substantial sellers and domestic institutions absorbed much of that selling.
Institutional flows should never be used in isolation to predict the market. But when strong foreign buying coincides with falling crude prices and improving sentiment toward Indian equities, it becomes an important part of the broader market picture.
Global Brokerages Turn More Positive on India
One of Monday’s more notable developments came from global brokerage positioning.
Several major firms have become more constructive on Indian equities.
Citi raised its end-2027 Nifty 50 target to 28,000, while HSBC upgraded India to overweight from neutral.
Jefferies also increased India’s recommended weighting in its Asia-Pacific ex-Japan relative-return portfolio from 12% to 14%, while reducing exposure to South Korea and Taiwan.
The reasons behind these moves are also worth understanding.
India’s relative attractiveness has improved as crude oil prices have fallen, domestic earnings remain comparatively resilient and investors reassess exposure to heavily crowded global AI-related trades.
India is a major crude importer, while its equity market is considerably less dependent on the semiconductor and AI-hardware cycle than markets such as Taiwan and South Korea.
That can improve India’s relative positioning when investors become more cautious about technology-heavy markets.
However, this distinction is important:
Brokerage targets are opinions, not outcomes.
Citi’s 28,000 Nifty target represents the firm’s expectations for the end of 2027. It does not mean the index will necessarily reach that level.
Similarly, an overweight recommendation does not mean Indian equities cannot correct.
The useful information here is simply that several large global institutions have become more constructive toward India at roughly the same time that foreign investor flows have improved.
Smallcaps Continue to Lag
Smallcaps were again among the weakest major parts of the market.
The Nifty Smallcap 100 gained only 0.10%, compared with:
- Bank Nifty: +1.51%
- Nifty Next 50: +1.11%
- Nifty Midcap 100: +0.55%
- Nifty 50: +0.23%
The divergence suggests that the recent recovery has still not translated into equally strong participation across the market.
That follows a difficult period for smaller stocks.
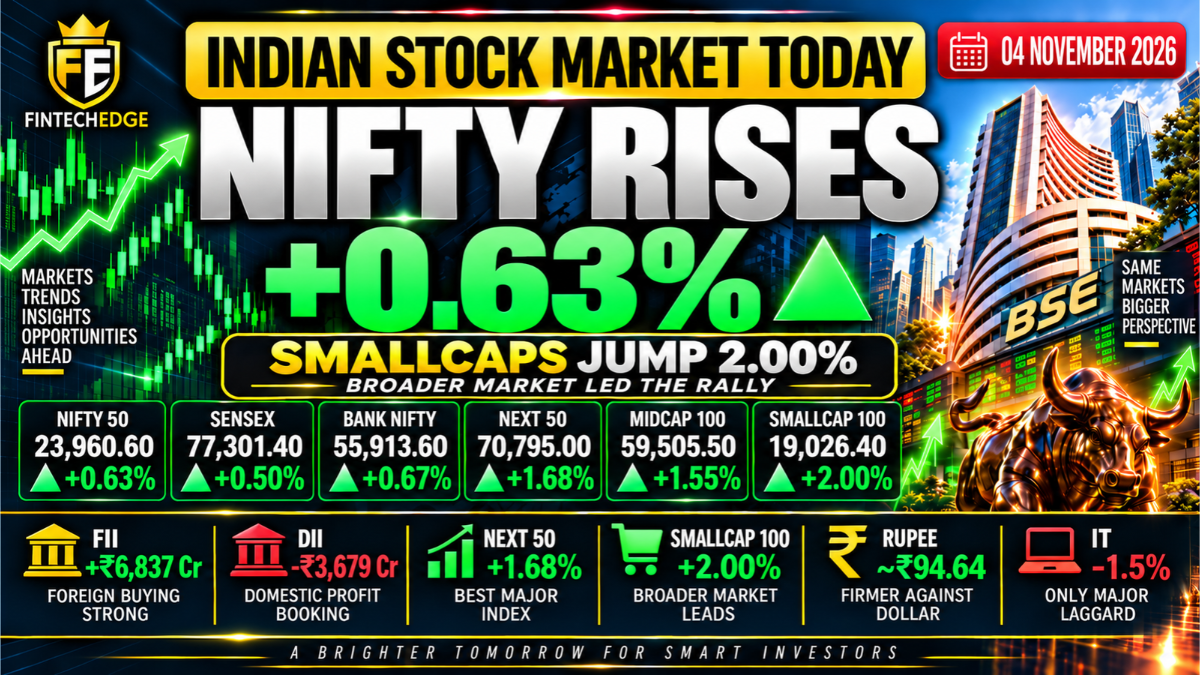
During October, midcaps and smallcaps fell significantly even while the headline benchmarks performed much better, something we highlighted in our 30 October market report.
Smallcaps have recovered from some of that weakness, but Monday’s limited gain shows that they are still not matching the strength visible in banking stocks and selected large caps.
For market health, breadth matters almost as much as the index level itself.
Lower Crude Improves India’s Macro Backdrop
Brent crude declined around 1% to approximately $97 per barrel, extending the improvement from the $110-plus levels seen during parts of late October.
For India, lower crude is generally favourable because the country imports most of its oil requirements.
Sustained lower oil prices can potentially help:
- reduce the import bill,
- ease inflationary pressure,
- improve the current-account balance,
- support the rupee, and
- reduce input-cost pressure for some businesses.
That does not mean crude was solely responsible for Monday’s market gain.
Banking leadership and institutional flows were more visible market-level drivers during the session.
Lower crude should therefore be viewed primarily as an improving macroeconomic backdrop, rather than a standalone explanation for every move in Indian equities.
IT Weakens While Pharma Gains
Sector performance remained uneven.
Pharmaceutical stocks were among the stronger groups, with the sector gaining around 1.6%, while the Nifty IT index dropped approximately 1.2%.
PSU banks were the strongest major group, followed by pharma and banking.
IT remained the most visible weak pocket among heavyweight sectors.
Global investors have recently been reassessing crowded technology and AI-related trades, but it would be too simplistic to attribute every move in Indian IT stocks directly to that trend.
The more defensible conclusion is simply that IT lagged while domestic financials and pharma provided leadership.
Market Breadth Remains Selective
The benchmark indices finished in positive territory, but market breadth was considerably less impressive.
Moneycontrol’s market snapshot showed approximately 1,445 advancing stocks against 1,848 declining stocks on the NSE.
The Nifty 50 itself also had more declining stocks than advancing stocks in one closing snapshot.
When the index rises while more individual stocks fall than rise, it indicates that gains are being driven disproportionately by a relatively small group of influential companies or sectors.
On Monday, banks were a major part of that leadership.
This is why looking only at the Nifty’s +0.23% closing move would miss an important part of the day’s story.
The market was positive — but not broadly strong.
What to Watch Next
With Indian equity markets closed on Tuesday for Diwali, the next regular trading session will be Wednesday.
Several factors deserve attention when trading resumes:
- FII flows: Whether strong foreign buying continues after the large November inflows.
- Banking leadership: Bank Nifty and PSU banks have become important drivers of the recent rally.
- Market breadth: A healthier continuation would ideally involve broader participation beyond banks and selected large caps.
- Smallcaps: Whether smaller companies begin to catch up with large caps and the Next 50.
- Inflation data: Upcoming macroeconomic data could influence expectations around inflation and monetary conditions.
- Crude oil: Brent near $97 remains a meaningful macro variable for India.
- Rupee: Foreign flows and crude prices could continue to influence the currency.
- Corporate earnings: Results and management commentary remain important as the market evaluates whether earnings can support the recent valuation recovery.
FintechEdge View
Monday’s market was less about the Nifty’s modest 0.23% gain and more about what happened underneath it.
Banks and PSU banks remained strong, foreign investors continued buying aggressively and several major global brokerages became more constructive toward India.
At the same time, breadth remained mixed, smallcaps lagged and IT weakened.
That combination matters.
The market is holding near its strongest level in more than eight months, but leadership is still selective. The recent rally has improved sentiment significantly, yet one week of strong gains and renewed foreign buying are not enough to eliminate market risk.
The more useful signal over the next few sessions will be whether the rally develops broader participation or remains dependent on a relatively narrow group of sectors.
Brokerage upgrades and index targets are worth monitoring as indicators of institutional sentiment — not as predictions investors should blindly follow.
Sources & References
- Indian shares close at eight-month high as crude oil falls — Reuters
- Citi and HSBC turn more constructive on Indian equities — Reuters
- Indian market indices, sector performance and FII/DII activity — Moneycontrol
- Jefferies raises India allocation to 14% — Moneycontrol
- Nifty and broader-market index closing data — NSE India
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.