Indian Stock Market Today: Nifty Rises 0.68% as Smallcaps Rebound 1.38%
Quick Summary
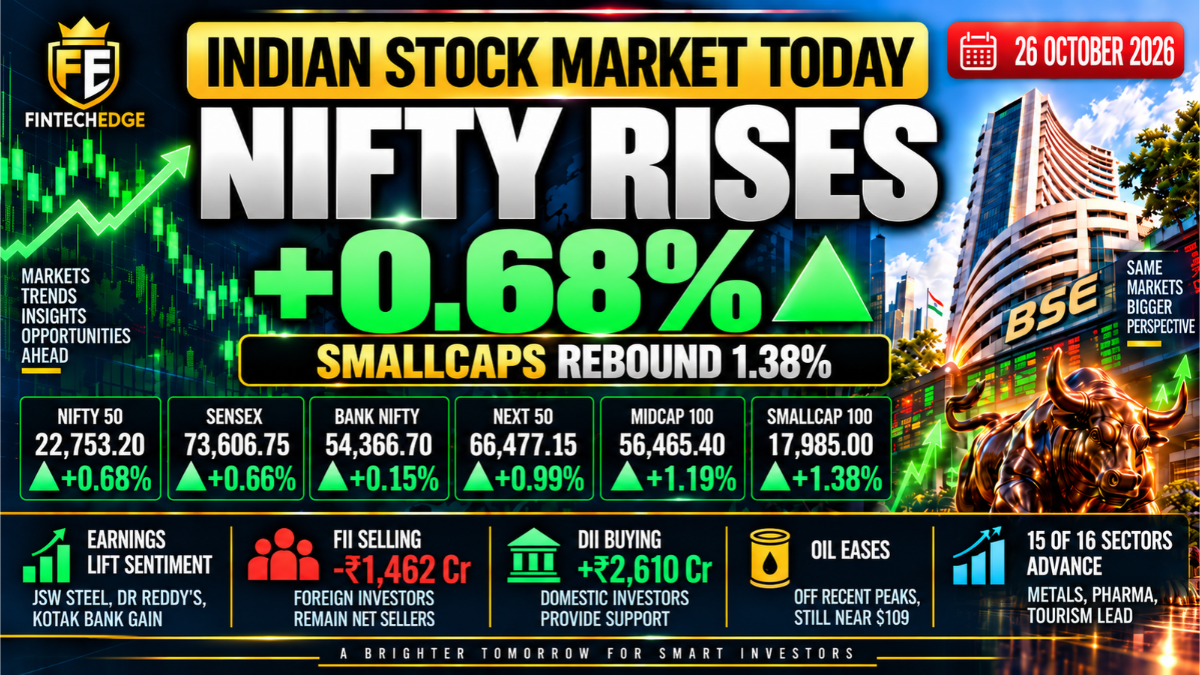
- Nifty 50 rose 0.68% to 22,753.20, while Sensex gained 0.66% to 73,606.75.
- The rebound was broad-based, with Next 50 up 0.99%, Midcap 100 up 1.19%, and Smallcap 100 up 1.38%.
- Bank Nifty lagged the recovery, gaining only 0.15%.
- Strong quarterly results supported sentiment, with gains in JSW Steel, Dr Reddy’s and Kotak Mahindra Bank.
- FIIs sold ₹1,462 crore, while DIIs bought ₹2,610 crore in the stock segment.
- Oil eased from recent peaks but remained elevated, keeping inflation and margin concerns in focus.
- Most major sectors finished higher, marking a broader recovery after four consecutive declining sessions.
Indian Market Performance — 26 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
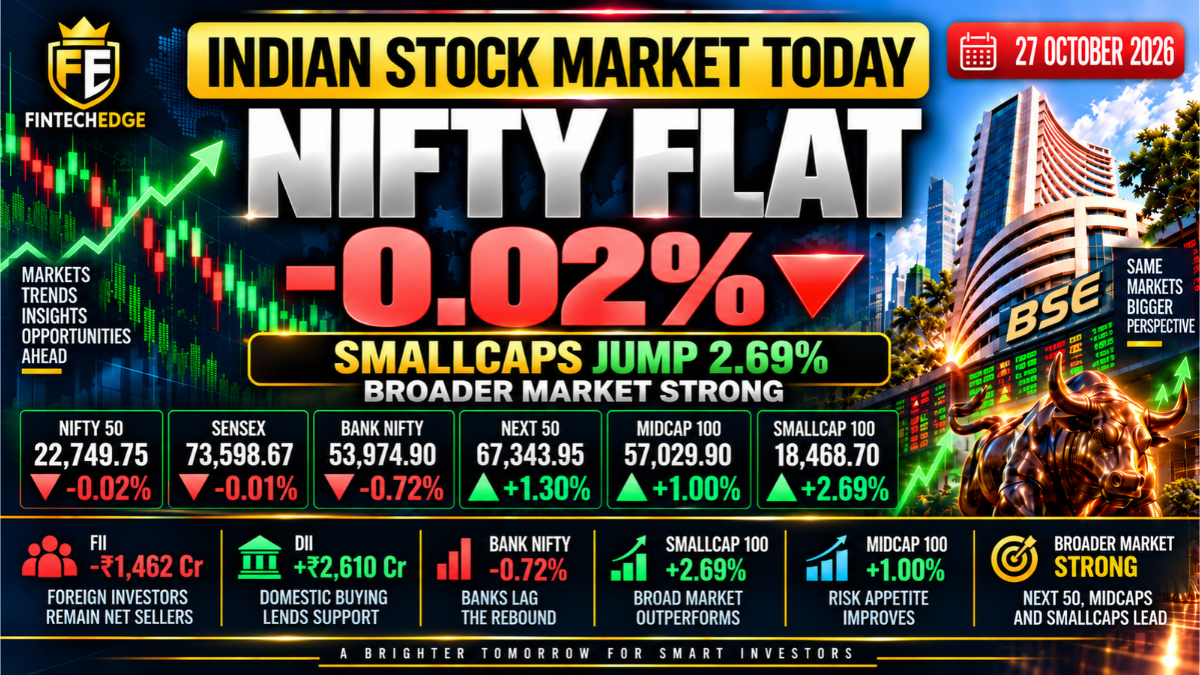
Indian stock market today snapped a four-session losing streak on 26 October 2026, with the Nifty 50 rising 0.68% to 22,753.20 and the Sensex gaining 0.66% to 73,606.75.
More importantly, the recovery was not limited to the headline indices. The Nifty Next 50 rose 0.99%, Midcap 100 gained 1.19%, and Smallcap 100 advanced 1.38%. Bank Nifty was the clear laggard, rising only 0.15%.
The change in market breadth was notable after the heavy selling seen last week. Earnings from selected companies supported sentiment, most major sectors finished higher, and oil eased from its recent peak. However, FIIs remained net sellers and Brent crude was still elevated enough to keep inflation and margin concerns alive.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,753.20 | +0.68% |
| Sensex | 73,606.75 | +0.66% |
| Bank Nifty | 54,366.70 | +0.15% |
| Nifty Next 50 | 66,477.15 | +0.99% |
| Nifty Midcap 100 | 56,465.40 | +1.19% |
| Nifty Smallcap 100 | 17,985.00 | +1.38% |
The important change was not simply that the Nifty finished higher.
The broader market, which had been hit much harder than the benchmarks during the previous week, finally outperformed.
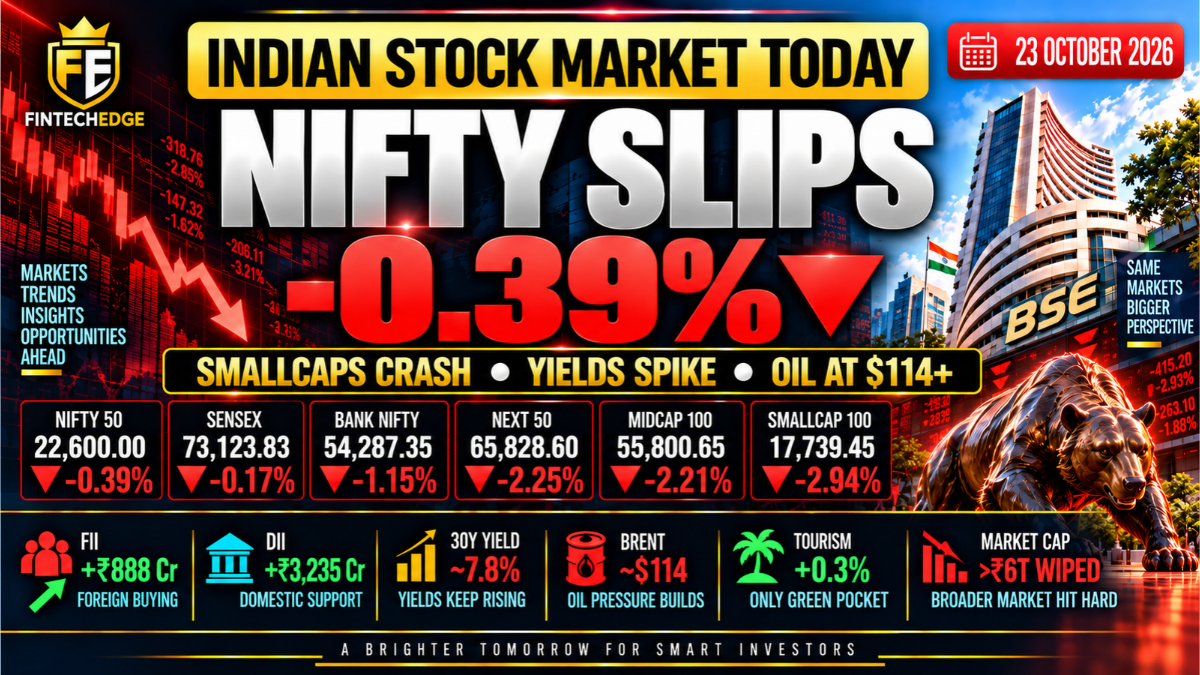
That makes 26 October different from 23 October, when the Nifty fell only 0.39% but the Smallcap 100 dropped 2.94%.
Smallcaps and Midcaps Lead the Rebound
The strongest internal signal today came from the broader market.
The Smallcap 100 gained 1.38%, Midcap 100 rose 1.19%, and Next 50 advanced 0.99%, compared with a 0.68% gain in the Nifty.
That is a meaningful change from last week.
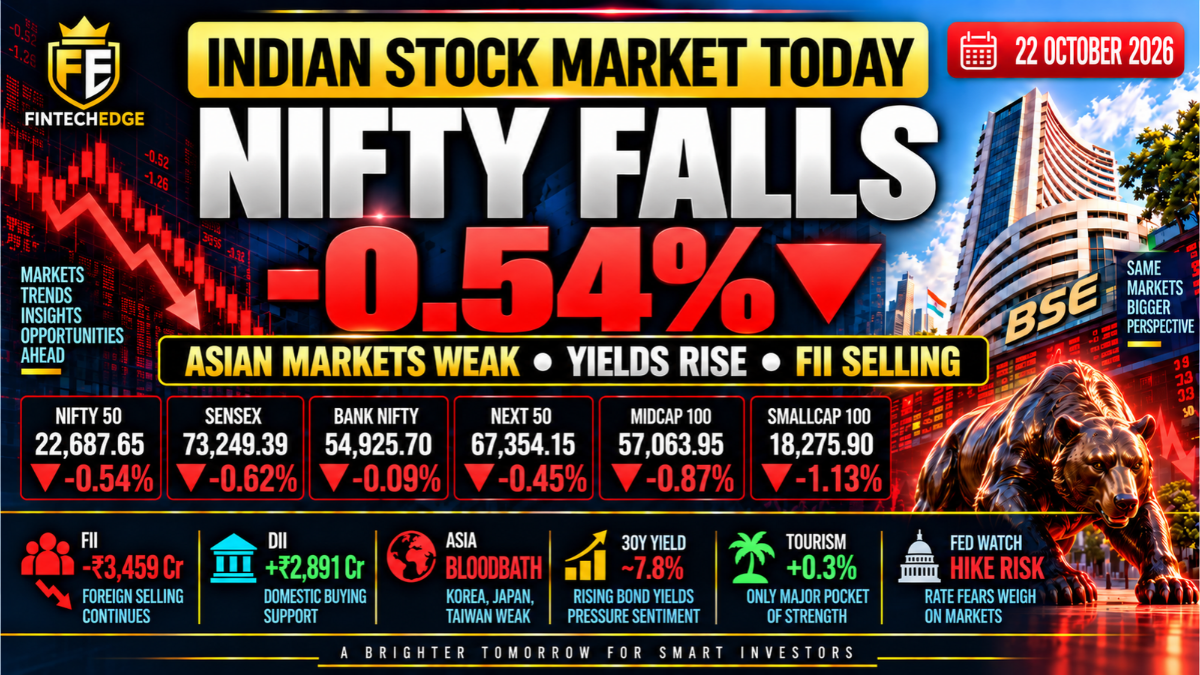
Between 21 and 23 October, smaller companies repeatedly underperformed the benchmarks. The pressure intensified on 21 October, when smallcaps fell 2.37%, and remained severe through Friday.
Today’s rebound therefore matters because participation improved across market-cap segments rather than being concentrated in a handful of large stocks.
But the move should be kept in perspective.
A one-day gain of around 1%–1.4% recovers only a fraction of the losses suffered by smallcaps and midcaps last week.
So this is best described as a broad-based rebound, not confirmation that the broader-market correction has ended.
Earnings Improve Sentiment
Corporate earnings provided one of the clearest positive catalysts.
Several companies reacted strongly to quarterly results:
- JSW Steel rose about 6.3% after quarterly profit increased sharply, supported by record volumes and improved capacity utilisation.
- Dr Reddy’s gained about 6.6% after beating profit expectations.
- Kotak Mahindra Bank rose roughly 2.4% after reporting better-than-expected quarterly profit.
- BSE gained around 4% following a brokerage upgrade.
The important point is that the rebound had identifiable company-level support.
After several sessions dominated by oil, foreign flows and broader risk aversion, earnings gave investors specific reasons to buy selected stocks.
This also helped improve sector participation.
Still, a few strong results do not automatically mean the entire earnings season is strong. The coming results from other large companies will determine whether earnings can remain a consistent support for the market.
FIIs Sell ₹1,462 Crore, DIIs Buy ₹2,610 Crore
Institutional flows remained mixed.
Your 26 October stock-segment data showed:
- FII: -₹1,462 crore
- DII: +₹2,610 crore
FIIs therefore remained net sellers, while domestic institutions again provided support.
This makes today’s rally more interesting.
The market advanced even though foreign investors were still selling.
That means today’s gain should not be interpreted as evidence that foreign capital has decisively returned to Indian equities.
October’s cumulative FII flow remains negative.
Domestic institutional buying continued to offset some of that pressure, and today DII buying exceeded the foreign selling figure.
For the market, a sustained reduction in FII selling would be more meaningful than a single positive session in the indices.
Oil Eases but Remains Elevated
Crude oil provided some relief after last week’s sharp rise.
The key distinction is that oil eased from recent peaks, but remained elevated enough to continue posing a macro risk.
That matters because high crude prices can affect India through:
- imported inflation;
- the trade and current-account balance;
- the rupee;
- corporate input costs;
- interest-rate expectations;
- and consumer demand.
The market had been under severe pressure when crude moved close to $115 during the 23 October sell-off.
A pullback from those highs gives equities some breathing room.
But as long as oil remains elevated, it cannot yet be considered a resolved risk.
Bank Nifty Lags the Recovery
Banks were the weakest major part of today’s rebound.
Bank Nifty gained only 0.15%, compared with:
- Nifty 50: +0.68%
- Next 50: +0.99%
- Midcap 100: +1.19%
- Smallcap 100: +1.38%
This is important because financials carry a large weight in the headline indices.
If banks had participated more strongly, the Nifty and Sensex could have seen a broader contribution from heavyweight sectors.
Within banking, however, performance was not uniformly weak.
Kotak Mahindra Bank gained after strong results, showing that stock-specific earnings continued to matter even though the banking index as a whole lagged.
The correct reading is therefore:
Banks participated only marginally in the recovery, while broader-market stocks led the session.
Most Sectors Finish Higher
Sector breadth improved considerably.
Most major sectors finished higher, marking a sharp improvement in market breadth compared with the broad weakness seen last week.
Metals gained around 2.2%, while pharma advanced roughly 1.8%. Tourism and capital-market stocks also performed well.
This improves the quality of today’s rebound.
A market rise is generally more meaningful when gains are spread across multiple sectors rather than concentrated in one heavyweight industry.
That said, this remains one session following a difficult week.
The next few sessions will show whether sector participation can remain broad or whether the gains narrow again.
Tax-Relief Chatter Adds Support, but No Policy Change Yet
Reports of a possible reduction in long-term capital-gains tax also circulated in the market.
These reports may have contributed to sentiment, but they need to be handled carefully.
There was no confirmed policy change as of the session covered here.
So the correct framing is:
Reports of possible capital-gains-tax relief added to market optimism, but investors were still waiting for concrete government action.
It would be premature to build an investment conclusion around unconfirmed reports.
The more tangible drivers today were improving market breadth and positive earnings reactions.
Why Today’s Rebound Matters After Last Week
The context of the previous week makes today’s move more useful to analyse.
On 23 October:
- Nifty fell only 0.39%;
- Smallcap 100 dropped 2.94%;
- Midcap 100 lost 2.21%;
- Next 50 fell 2.25%.
Today:
- Nifty rose 0.68%;
- Smallcap 100 gained 1.38%;
- Midcap 100 rose 1.19%;
- Next 50 advanced 0.99%.
The direction of the divergence therefore reversed.
Last week, broader-market weakness was much worse than the headline indices.
Today, the broader market rose more than the Nifty.
That is the most constructive feature of the session.
It does not erase the previous losses, but it does show that buying interest returned to parts of the market that had suffered the most.
Global Backdrop Remains Mixed
Global markets remained mixed.
That means today’s Indian rebound was not simply the result of an overwhelmingly positive international session.
Domestic earnings, improved breadth and some easing in oil pressure played a larger role.
Global bond yields, oil, geopolitical developments and US monetary-policy expectations will nevertheless remain relevant because they influence capital flows and risk appetite toward emerging markets.
What to Watch Next
Broader-market follow-through
Today’s smallcap and midcap outperformance was important. The next question is whether it lasts beyond one session.
Earnings
Quarterly results supported several major stocks. Continued earnings strength could provide a more durable domestic catalyst.
FII flows
Foreign investors remained net sellers despite the market rally. A sustained moderation in selling would strengthen the recovery.
Brent crude
Oil has eased from recent peaks but remains elevated. Another sharp move higher would quickly return macro pressure to the centre of the market story.
Bank Nifty
Banks barely participated today. Stronger banking participation would make the recovery more balanced.
Capital-gains-tax reports
Investors should distinguish between market chatter and an actual government announcement.
FintechEdge View
The Indian stock market today produced its first broad relief session after four consecutive declines.
What stands out is not just the Nifty’s 0.68% gain.
Smallcaps rose 1.38%, midcaps gained 1.19%, and the Next 50 advanced almost 1%, meaning the parts of the market that suffered the most last week led today’s recovery.
Earnings also provided genuine stock-specific support.
At the same time, there are reasons to remain measured.
FIIs were still net sellers, Bank Nifty barely moved, and crude remains elevated despite easing from recent peaks.
So today’s move is best understood as a broad-based rebound after heavy selling, supported by earnings and improved market breadth—not yet proof that the recent pressure has fully reversed.
The next step is to see whether the broader market can hold these gains while oil, foreign flows and earnings continue to evolve.
Sources & References
- Indian shares snap four-session losing streak as earnings support sentiment — Reuters
- Nifty 50 and broader index market data — NSE India
- NSE market reports and historical data — NSE India
- FII/DII stock-segment activity for 26 October 2026 — FintechEdge market data
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.