Indian Stock Market Today: Nifty Flat as Smallcaps Surge 2.69%
Quick Summary
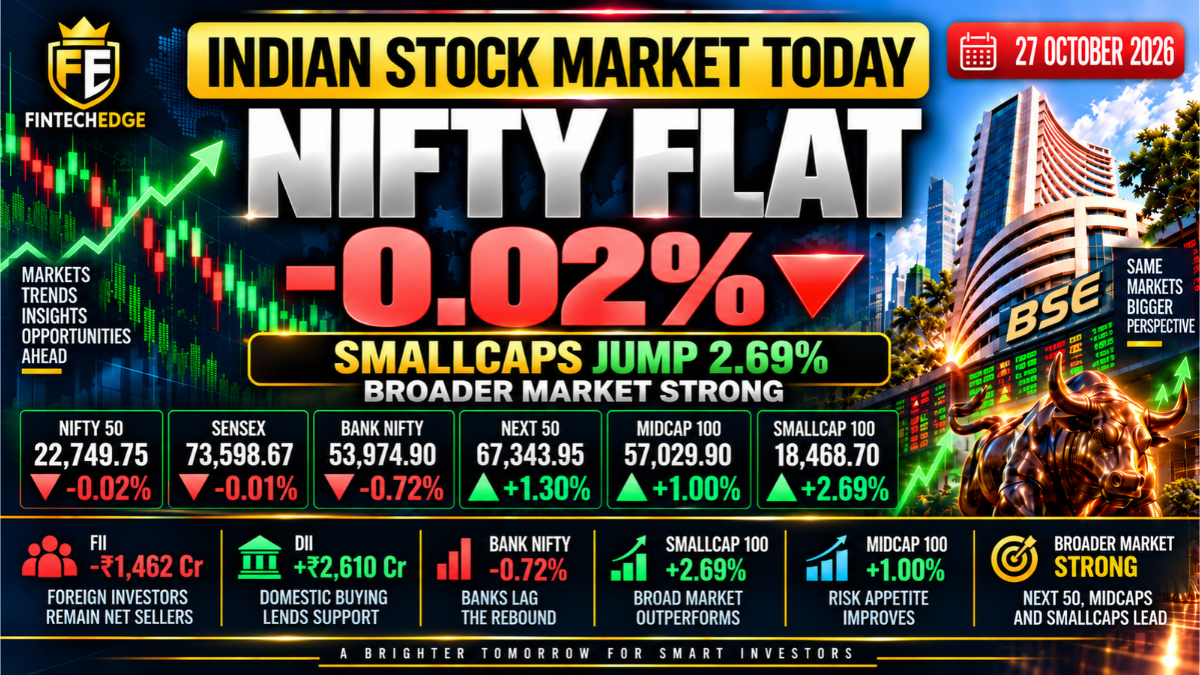
- Nifty 50 slipped 0.02% to 22,749.75, while Sensex fell 0.01% to 73,598.67.
- The broader market rallied sharply, with Next 50 up 1.30%, Midcap 100 up 1.00%, and Smallcap 100 up 2.69%.
- Bank Nifty was the major laggard, falling 0.72%.
- Smallcaps and midcaps extended their rebound for a second straight session after last week’s sharp decline.
- Brent crude remained near $116 per barrel, keeping inflation and external-balance concerns in focus.
- Most major sectors finished higher, although financials and IT lagged.
- Tata Consumer rose sharply after stronger-than-expected quarterly results, while investors stayed cautious ahead of the Federal Reserve decision.
Indian Market Performance — 27 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian stock market today finished almost unchanged on 27 October 2026, but the headline indices again hid a very different story underneath. The Nifty 50 slipped 0.02% to 22,749.75, while the Sensex fell 0.01% to 73,598.67. The broader market, however, strengthened sharply: the Nifty Next 50 rose 1.30%, the Midcap 100 gained 1.00%, and the Smallcap 100 surged 2.69%. Bank Nifty moved in the opposite direction, falling 0.72%. Pasted text
The session therefore looked flat only at the benchmark level. Beneath the Nifty and Sensex, buying returned strongly to smaller companies for a second consecutive session. At the same time, banks remained weak, crude oil hovered near $116 per barrel, and investors stayed cautious ahead of the Federal Reserve’s policy decision.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,749.75 | -0.02% |
| Sensex | 73,598.67 | -0.01% |
| Bank Nifty | 53,974.90 | -0.72% |
| Nifty Next 50 | 67,343.95 | +1.30% |
| Nifty Midcap 100 | 57,029.90 | +1.00% |
| Nifty Smallcap 100 | 18,468.70 | +2.69% |
The divergence is striking.
The Nifty and Sensex barely moved, but the Smallcap 100 rose almost 2.7%. That makes today very different from the broad weakness seen last week.
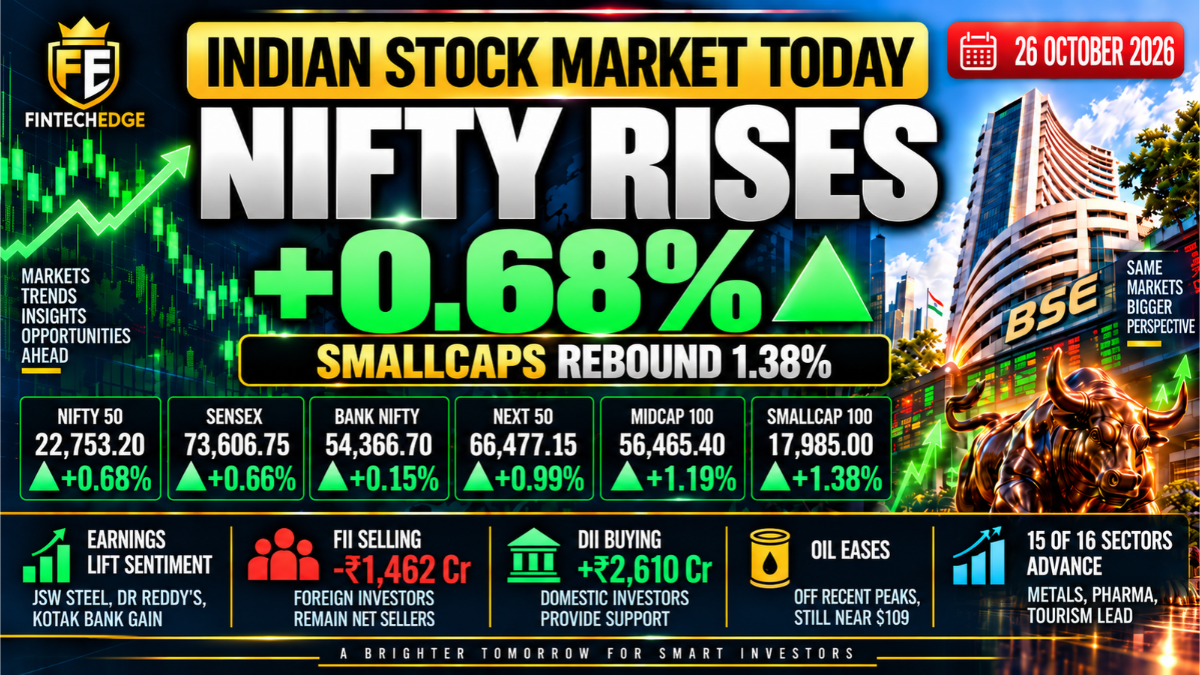
It also extends the improvement that began on 26 October, when smallcaps and midcaps led a broad rebound after four consecutive declining sessions.
Smallcaps Extend the Rebound
The broader-market recovery continued for a second straight session.
The Smallcap 100 jumped 2.69%, while the Midcap 100 gained 1.00% and the Next 50 rose 1.30%.
That matters because these were the same areas of the market that suffered the deepest losses during the previous week.
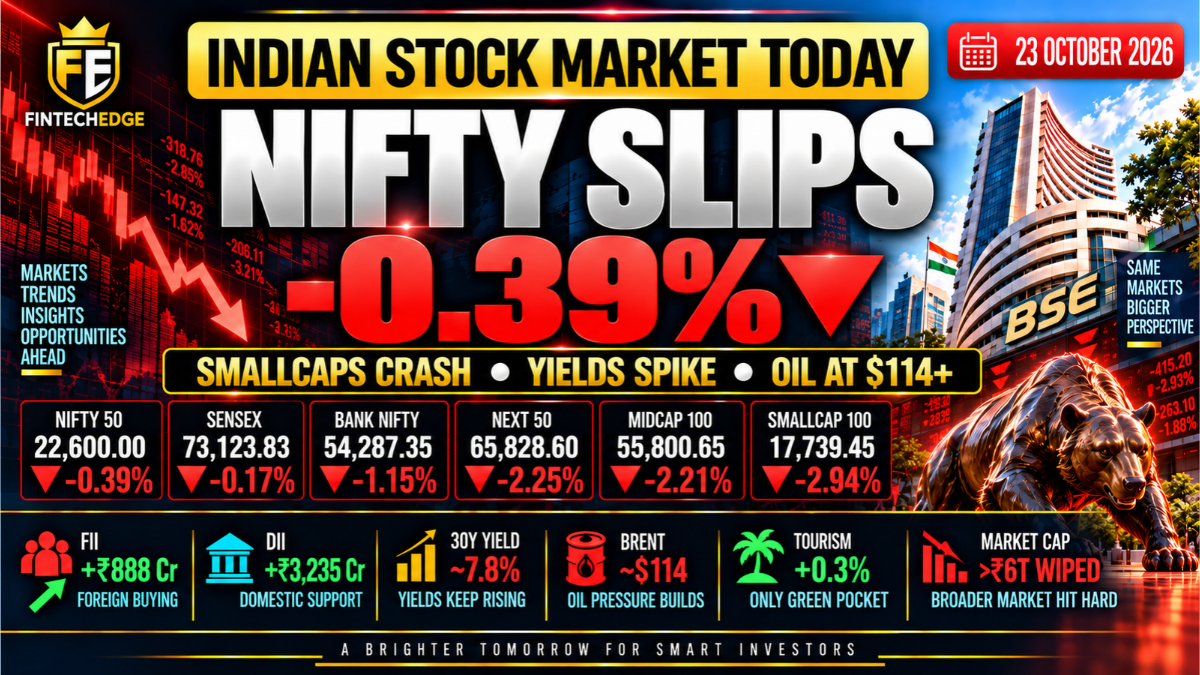
On 23 October, for example, the Smallcap 100 had fallen 2.94% and the Midcap 100 lost 2.21%, while the Nifty declined only 0.39%.
The last two sessions have reversed part of that divergence.
That does not mean the smallcap correction is over.
Two strong sessions after a steep fall recover only a portion of the previous losses. But they do show that buying interest has returned to parts of the market that had been under the greatest pressure.
This is the most constructive feature of today’s session.
Bank Nifty Falls 0.72%
Banks told a very different story.
Bank Nifty fell 0.72%, even as smallcaps surged 2.69% and midcaps gained 1%.
Financials were among the weaker parts of the market, and because banks carry substantial weight in both the Nifty and Sensex, their weakness helps explain why the headline benchmarks remained flat despite positive broader-market participation.
This divergence has now been visible for two sessions.
On 26 October, Bank Nifty gained just 0.15% while smallcaps rose more than 1%.
Today the gap widened further.
The important point is not that banks are entering a new downtrend. The data do not establish that.
What they do show is that financials are currently lagging the broader-market recovery.
That difference is worth watching because a more balanced rally would normally require participation from large financial stocks as well.
Fed Decision Keeps Benchmarks Cautious
The Federal Reserve’s policy decision is one of the biggest global events in focus.
The Fed meeting concludes on Wednesday, and markets are paying close attention not only to the policy rate itself but also to what policymakers say about future tightening.
That distinction matters.
When a decision is widely anticipated, the market reaction often depends more on guidance than on the headline rate announcement.
For India, a more hawkish Federal Reserve stance could have implications for:
- US Treasury yields;
- the dollar;
- emerging-market currencies;
- foreign portfolio flows;
- and equity valuations.
That helps explain why investors in the large-cap benchmarks remained cautious even while smaller stocks rallied.
The article should not assume that a Fed hold would automatically produce a positive market reaction.
The tone of the guidance will likely matter just as much as the decision.
Oil Near $116 Remains a Macro Risk
Crude oil remains another important constraint.
Brent crude hovered near $116 per barrel, close to a six-month high.
For India, that level matters because the country imports a significant share of its energy requirements.
High crude can affect:
- imported inflation;
- the trade and current-account balances;
- the rupee;
- corporate input costs;
- and interest-rate expectations.
This is why the broader-market rebound should not be viewed in isolation.
Domestic market breadth improved today, but the external backdrop remains difficult.
That combination—stronger smallcaps but elevated oil—is one of the most important contradictions in the current market.
Most Sectors Finish Higher
Sector breadth was broadly positive.
According to the session data, 12 of 16 major sectors advanced, although financials and IT remained weak. Autos and pharmaceuticals were among the better-performing groups.
This is another reason the flat Nifty reading does not tell the whole story.
A majority of sectors finished higher.
Yet the Nifty barely moved because some of its heaviest components, particularly financials and IT, failed to participate.
That is an important lesson in index structure.
A benchmark can remain flat even when a large portion of the market is advancing if its largest weighted sectors are weak.
Tata Consumer Jumps After Strong Results
Tata Consumer Products was one of the standout large-cap gainers.
The stock rose about 6.8%, its biggest one-day gain in nearly 19 months, after stronger-than-expected quarterly results and supportive brokerage commentary.
Profit increased about 16%, while revenue rose around 14%.
The move fits a pattern visible over the last several sessions.
Earnings are increasingly creating sharp stock-specific reactions.
That is healthy from a market-analysis perspective because it means not every stock is moving purely on macro sentiment.
Company-level performance is again becoming an important differentiator.
IT Takes a Breather
IT stocks, which had been one of the strongest parts of the market during the earlier rebound, were weaker today.
The sector has delivered strong relative performance over the last month, but today some of that momentum eased.
This does not invalidate the recent IT recovery.
It simply means sector leadership rotated.
On some recent sessions, IT had supported the Nifty while the broader market struggled. Today the opposite happened: broader-market stocks strengthened while some heavyweight IT names lagged.
That rotation is another reason the headline index remained flat.
Rupee Holds Near ₹95.12
The rupee remained broadly stable around ₹95.12 per dollar.
But the underlying pressures remain visible.
High crude prices increase India’s dollar demand through energy imports, while elevated US yields can reduce the relative attraction of emerging-market assets.
RBI support has helped limit the downside, but the currency remains sensitive to both oil and global rate expectations.
That makes the upcoming Federal Reserve communication particularly relevant.
A sharp move in US yields could quickly feed through to the rupee and foreign flows.
Capital-Gains Discussion Remains Unconfirmed
Discussion around possible changes to long-term capital-gains taxation continues in the market.
But there has been no confirmed policy announcement.
That means it should remain a secondary sentiment factor rather than a core explanation for market movements.
Investors should distinguish clearly between:
- media reports;
- market speculation;
- and an actual government notification.
Until there is a confirmed policy change, the stronger explanations for daily market movement remain earnings, oil, interest-rate expectations, global risk sentiment and domestic market breadth.
Why Today’s Divergence Matters
Today’s session provides another useful example of why investors should look beyond the Nifty.
Consider the difference:
Nifty 50: -0.02%
Smallcap 100: +2.69%
Those two numbers describe completely different market experiences.
An investor concentrated in large financial stocks could have had a weak day.
An investor heavily exposed to smaller companies may have experienced a strong rebound.
That is why market breadth, sector performance and market-cap segmentation matter when interpreting a daily close.
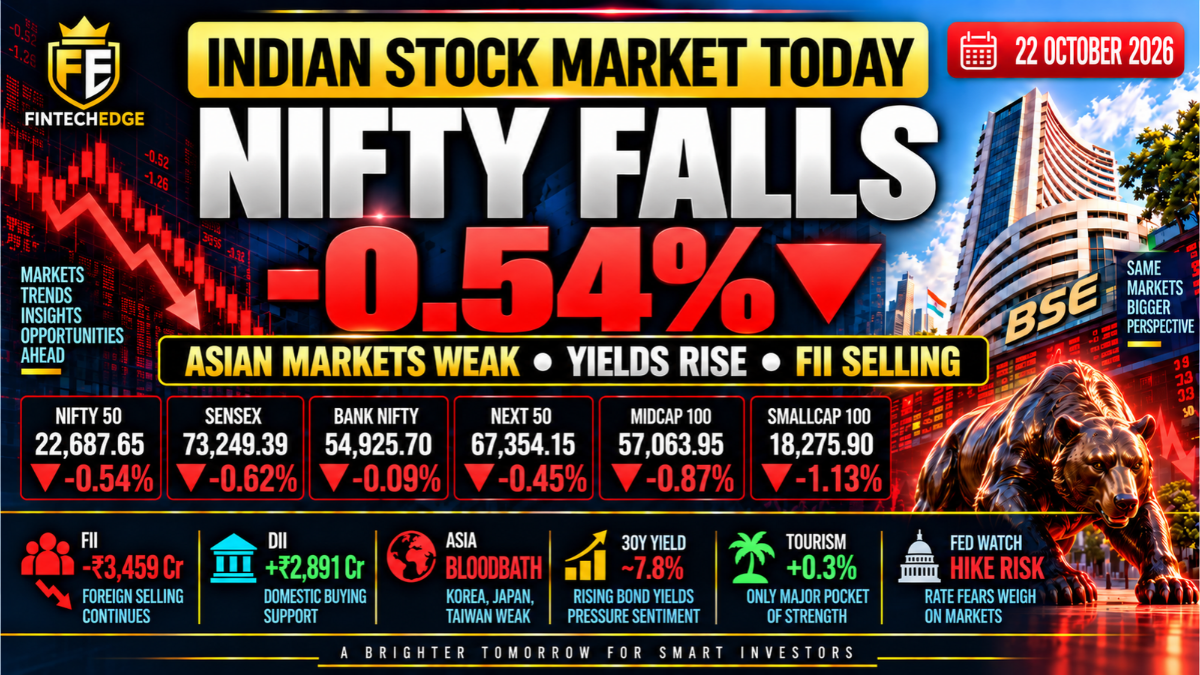
It also highlights how different today was from 21 October, when the Nifty fell only modestly but smallcaps dropped sharply.
Today, that divergence moved in the opposite direction.
What to Watch Next
Federal Reserve guidance
The market will focus on what the Fed says about future interest rates rather than only the headline decision.
Brent crude
Oil near $116 remains one of India’s clearest macro risks.
Smallcap and midcap follow-through
The broader market has now recovered for two consecutive sessions. Whether that continues for a third session will help indicate the durability of the rebound.
Bank Nifty
Banks have lagged for two sessions. Stabilisation in financials would make the recovery more balanced.
Earnings
Company results are producing increasingly large individual stock moves. That is likely to remain a major driver.
Rupee
The currency remains near ₹95.12, with oil and global yields still acting as important pressure points.
FintechEdge View
The Indian stock market today was almost unchanged at the headline level, but the session was anything but flat underneath.
Smallcaps surged 2.69%, midcaps gained 1%, and the Next 50 rose 1.30%, extending the broader-market recovery for a second session.
At the same time, Bank Nifty fell 0.72%, IT weakened, crude remained near $116, and investors stayed cautious ahead of the Federal Reserve.
The strongest conclusion is therefore not that the market was flat.
It is that market leadership shifted sharply toward the broader market while heavyweight financial stocks held back the benchmarks.
That is an improvement from last week’s severe breadth weakness, but two recovery sessions do not yet establish a durable trend.
The next important test is whether smallcaps and midcaps can retain their gains while banks, oil and the global rate environment remain challenging.
Sources & References
- Indian shares end nearly flat as investors await Federal Reserve decision — Reuters
- Tata Consumer rises after strong quarterly results and brokerage upgrades — Reuters
- Rupee holds near ₹95.12 as oil and US yields remain in focus — Reuters
- Global central-bank decisions and technology earnings in focus — Reuters
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.