Indian Stock Market Today: Nifty Falls 0.22% as Jio Surges on Debut
Quick Summary
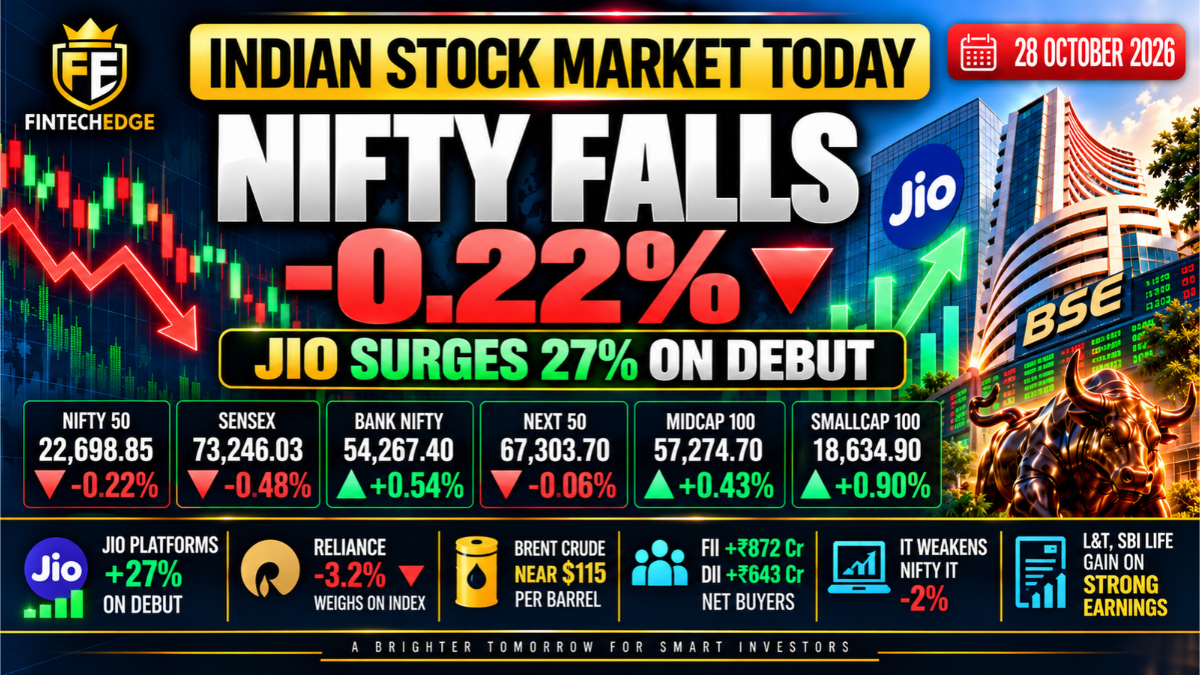
- Nifty 50 fell 0.22% to 22,698.85, while Sensex declined 0.48% to 73,246.03.
- Bank Nifty outperformed with a 0.54% gain, while Midcap 100 rose 0.43% and Smallcap 100 advanced 0.90%.
- Jio Platforms jumped about 27% on its stock-market debut, while Reliance Industries fell around 3.2% and weighed on the benchmarks.
- FIIs bought ₹872 crore, while DIIs bought ₹643 crore in the stock segment.
- Brent crude remained near $115 per barrel, keeping inflation and external-balance concerns in focus.
- IT weakened, while selected earnings-driven stocks such as L&T and SBI Life gained.
- Investors remained focused on the Federal Reserve decision and guidance on future interest rates.
Indian Market Performance — 28 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian stock market today ended lower on 28 October 2026, with the Nifty 50 falling 0.22% to 22,698.85 and the Sensex declining 0.48% to 73,246.03, while Jio Platforms surged on its market debut and smallcaps continued to outperform.
The headline indices were weak, but the session was far from uniformly negative. Bank Nifty gained 0.54%, the Midcap 100 rose 0.43%, and the Smallcap 100 advanced 0.90%. The Nifty Next 50 was almost unchanged at -0.06%.
The biggest corporate event was the listing of Jio Platforms, which jumped sharply on debut. Yet Reliance Industries fell around 3%, creating an unusual contrast between the newly listed business and its parent. At the macro level, crude oil remained near $115 per barrel, while investors waited for the Federal Reserve’s policy decision.
Indian Market Performance
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,698.85 | -0.22% |
| Sensex | 73,246.03 | -0.48% |
| Bank Nifty | 54,267.40 | +0.54% |
| Nifty Next 50 | 67,303.70 | -0.06% |
| Nifty Midcap 100 | 57,274.70 | +0.43% |
| Nifty Smallcap 100 | 18,634.90 | +0.90% |
The day again showed why the Nifty alone can give an incomplete picture of the market.
The benchmark fell 0.22%, but smallcaps and midcaps closed higher, while Bank Nifty also outperformed.
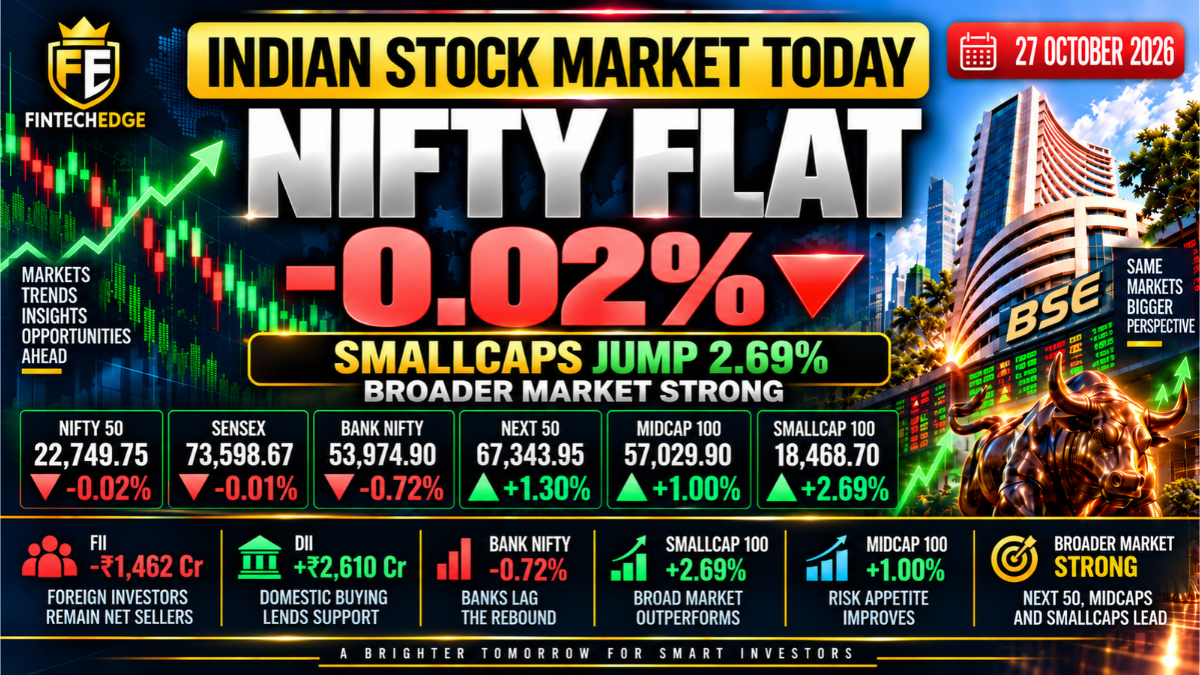
That continues the improvement seen on 27 October, when smallcaps surged 2.69% despite a flat Nifty.
Jio Platforms Surges on Market Debut
Jio Platforms was the standout corporate story.
The stock jumped about 27% to around ₹1,417.50 on debut, giving the company a market value of roughly $137 billion and immediately placing it among India’s largest listed companies.
That is significant not just because of the size of the IPO, but because of what it says about investor demand.
The listing followed exceptionally strong subscription interest, showing that investors were willing to commit substantial capital to a large new issue even while the broader market had been going through a difficult period.
But the stronger signal came from the contrast with Reliance Industries.
Jio surged.
Reliance fell.
That divergence made the session more interesting than a straightforward “successful IPO day.”
Reliance Weighs on the Benchmarks
Reliance Industries fell around 3.2%, becoming one of the major drags on the Nifty and Sensex.
Because Reliance carries substantial weight in both indices, a decline of that size can materially affect the headline benchmarks even when many other stocks are doing reasonably well.
That helps explain today’s market structure.
The Nifty fell 0.22%, yet:
- Bank Nifty rose 0.54%;
- Midcap 100 gained 0.43%;
- Smallcap 100 rose 0.90%.
The weakness was therefore concentrated enough in heavyweight stocks to pull down the benchmarks without producing a broad market sell-off.
It would be tempting to describe Reliance’s decline as a simple “sell-the-news” reaction after the Jio listing.
But that would go beyond what the data prove.
The safer conclusion is that Reliance weakness offset part of the positive broader-market participation and became an important drag on the indices.
Smallcaps and Midcaps Stay Resilient
The broader market remained comparatively strong.
Smallcap 100 gained 0.90%, while Midcap 100 rose 0.43%.
This is notable because smallcaps and midcaps were the weakest parts of the market during the sharp sell-off last week.
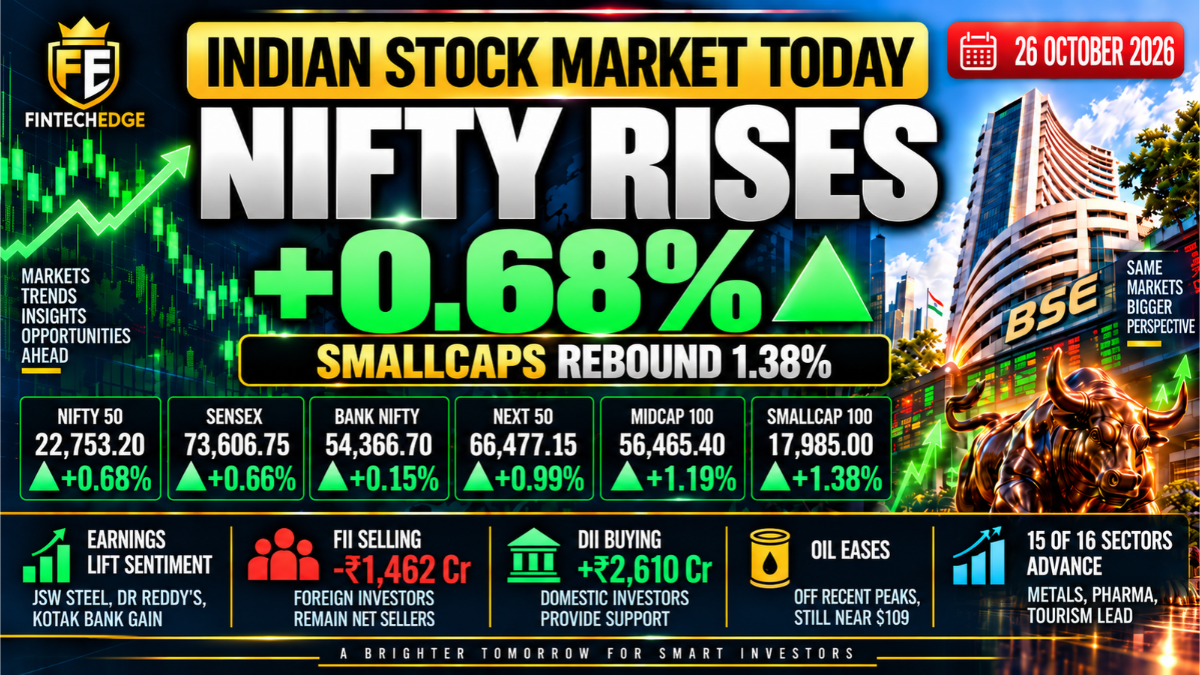
Their recovery started on 26 October, when smallcaps gained 1.38% and midcaps rose 1.19% and accelerated on 27 October.
Today’s gains were smaller, but they extended that recovery for another session.
That does not prove a durable bottom.
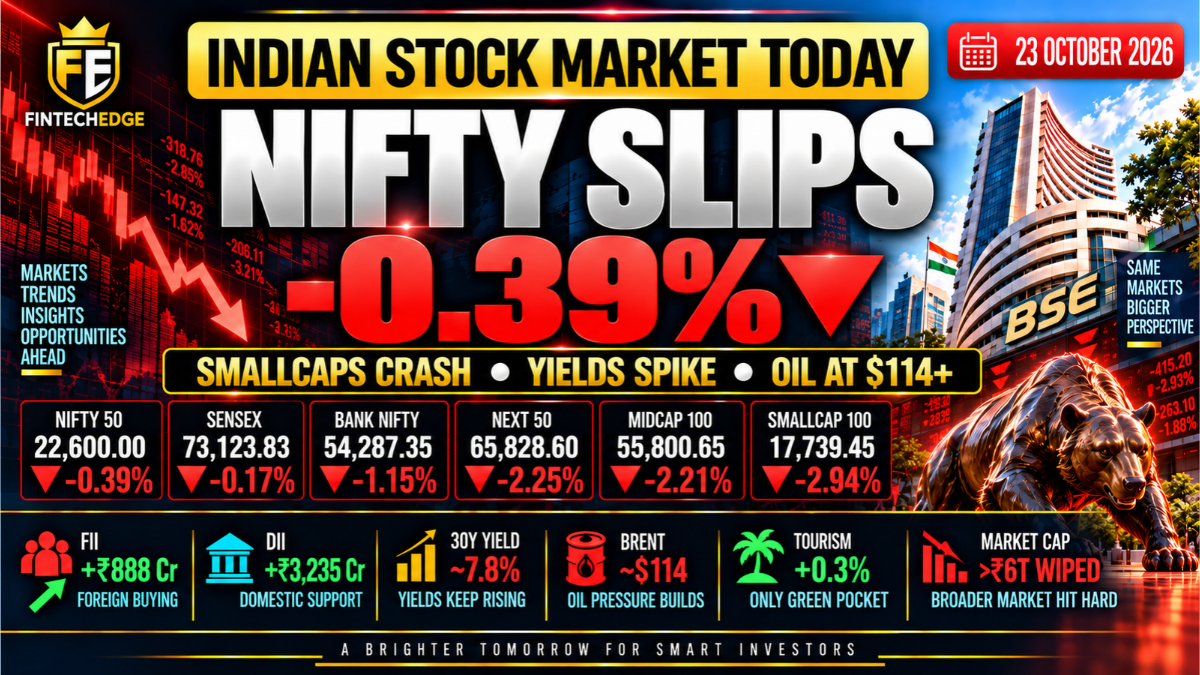
But the structure is clearly different from the market seen between 21 and 23 October, when the broader indices repeatedly suffered much larger losses than the Nifty.
The most useful conclusion is that selling pressure in smaller companies has eased for now, while participation beneath the large-cap benchmarks has improved.
Bank Nifty Outperforms
Bank Nifty gained 0.54%, making it one of the stronger major indices of the day.
That is a meaningful change.
Banks had lagged the recovery over the previous two sessions. On 27 October, Bank Nifty fell 0.72% even as smallcaps surged.
Today, the pattern reversed.
Banks moved higher even though the Nifty and Sensex declined.
This improved balance within the market because financials carry large weights in the benchmarks and had recently acted as a drag.
Still, one positive banking session does not establish a new sector trend.
It simply shows that financial stocks were relatively stronger today than they had been earlier in the week.
Oil Near $115 Keeps Macro Pressure High
Crude oil remained one of the biggest macro risks.
Brent stayed near $115 per barrel, close to recent highs.
For India, sustained oil prices at these levels matter because higher crude can affect:
- inflation;
- the import bill;
- the current account;
- the rupee;
- corporate margins;
- and interest-rate expectations.
High oil is particularly important when the rupee is already trading close to ₹95 per dollar.
Even if equities stabilise domestically, elevated oil can continue to influence foreign flows, currency expectations and monetary-policy assumptions.
That is why today’s smallcap and bank strength should be viewed alongside—not separately from—the external macro environment.
FIIs and DIIs Both Turn Net Buyers
Institutional flows were more supportive today.
Your 28 October stock-segment data showed:
- FII: +₹872 crore
- DII: +₹643 crore
Both foreign and domestic institutions were net buyers.
That is a notable change because foreign investors had been net sellers on many recent sessions.
But one positive day should not be interpreted as confirmation that the broader FII trend has changed.
October’s cumulative foreign-flow figure remains deeply negative.
What today’s numbers do show is that the benchmark decline was not driven by net institutional selling in the cash market.
That strengthens the interpretation that heavyweight stock-specific weakness—particularly Reliance—played a major role in the index performance.
Fed Decision Keeps Investors Cautious
The Federal Reserve decision remained one of the most important global events in focus.
Markets broadly expected the Fed to leave interest rates unchanged, but the bigger issue was the guidance on future policy.
For Indian markets, that matters because a more hawkish Fed can influence:
- US Treasury yields;
- the dollar;
- emerging-market currencies;
- foreign capital flows;
- and equity valuations.
A pause in rates does not automatically mean positive markets.
If policymakers signal that further tightening remains possible, global financial conditions can still remain restrictive.
That is why the communication accompanying the policy decision deserves as much attention as the headline rate itself.
IT Weakens as Sector Leadership Rotates
IT stocks were among the weaker parts of the market.
This is notable because IT had been one of the strongest sectors during the rebound earlier this month.
Sector leadership has therefore continued to rotate.
Earlier, IT supported the benchmarks while the broader market struggled.
Over the last few sessions, smallcaps, midcaps and selected cyclical sectors have improved while IT has lost some momentum.
This does not mean the IT recovery has ended.
It simply shows that the market is becoming more selective again.
That kind of rotation is normal when different parts of the market respond to earnings, global technology sentiment and interest-rate expectations differently.
Earnings Continue to Drive Individual Stocks
Quarterly results remained an important stock-specific driver.
Larsen & Toubro and SBI Life were among the notable gainers following strong earnings.
That follows several recent sessions when earnings produced large individual moves.
This is constructive from a market-quality perspective.
A market driven entirely by macro headlines can become highly correlated, with most stocks moving together.
When earnings begin to differentiate winners from losers, company-specific fundamentals regain importance.
That does not necessarily lift the entire index, but it creates opportunities for more selective market participation.
Rupee Remains Near ₹95.2
The rupee remained around ₹95.2 per dollar.
That keeps currency pressure relevant, particularly while crude remains close to $115.
High oil increases dollar demand from Indian importers, while elevated global yields can influence foreign capital flows.
The transcript contained several claims around possible restrictions on dollar outflows and changes to the Liberalised Remittance Scheme.
Those should not be treated as established facts.
Unless any such measure is formally announced, the more useful variables remain:
- crude oil;
- global yields;
- RBI actions;
- and foreign portfolio flows.
Why Today’s Market Was Stronger Than the Nifty Suggested
The headline Nifty fell.
But underneath:
Bank Nifty: +0.54%
Midcap 100: +0.43%
Smallcap 100: +0.90%
At the same time:
Nifty 50: -0.22%
Sensex: -0.48%
That divergence tells us the decline was not broad-based.
Large benchmark stocks—especially Reliance—had enough weight to pull the indices lower, while several other market segments remained positive.
This is almost the opposite of what happened during the 23 October sell-off, when the Nifty fell modestly but smallcaps and midcaps suffered much larger declines.
The quality of today’s session was therefore better than the negative Nifty close initially suggests.
What to Watch Next
Federal Reserve guidance
The Fed decision and communication on future rates could influence yields, the dollar and global risk appetite.
Brent crude
Oil near $115 remains one of the clearest macro risks for India.
Reliance Industries
Because Reliance is a heavyweight, further weakness or stabilisation could have a meaningful impact on the headline indices.
Jio Platforms
After the strong debut, attention shifts to how the stock trades once the initial listing excitement settles.
Smallcaps and midcaps
The broader-market recovery has now extended across multiple sessions. Whether that participation continues will be important.
Bank Nifty
Banks finally outperformed today after lagging the previous recovery sessions.
FII flows
FIIs returned to net buying today. Whether that continues is more important than the single-session figure.
FintechEdge View
The Indian stock market today looked weaker at the benchmark level than it did underneath.
The Nifty fell 0.22% and the Sensex lost 0.48%, but Bank Nifty gained 0.54%, midcaps rose 0.43%, and smallcaps advanced 0.90%.
Jio Platforms’ strong debut was the major corporate event, while Reliance Industries moved in the opposite direction and weighed on the benchmarks.
At the same time, both FIIs and DIIs were net buyers, suggesting that institutional cash-market flows were more supportive than the negative index close implies.
The unresolved risks remain external: crude near $115, a rupee near ₹95.2, and uncertainty around the Fed’s next signal.
So the most important takeaway is not simply that the Nifty fell.
It is that the benchmark decline was concentrated, while broader-market participation and banking performance remained comparatively resilient.
Sources & References
- Indian shares slip as oil rises; Jio market debut in focus — Reuters
- Jio Platforms jumps on market debut after record IPO — Reuters
- Federal Reserve expected to remain in wait-and-see mode — Reuters
- Nifty 50 and broader index data — NSE India
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.