Indian Stock Market Today: Nifty Reclaims 23,400 as Metals Lead Broad-Based Rally
Quick Summary
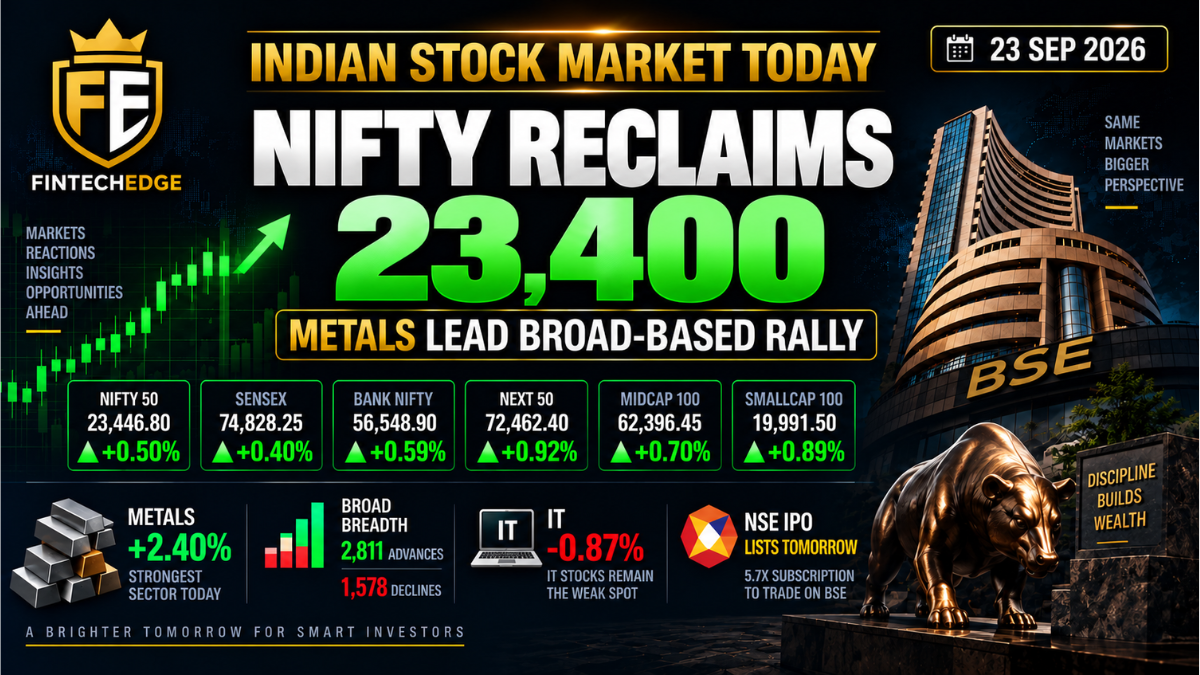
- Nifty 50 gained 0.50% to 23,446.80, while Sensex rose 0.40% to 74,828.25.
- Bank Nifty advanced 0.59%, supporting the benchmark recovery.
- Broader markets participated strongly: Nifty Next 50 rose 0.92%, Midcap 100 gained 0.70%, and Smallcap advanced 0.89%.
- Metals led the sectoral rally, with the Nifty Metal index rising around 2.4%.
- IT remained the main weak pocket, extending its recent underperformance.
- The NSE is scheduled to list on the BSE on 24 September after its IPO was subscribed about 5.7 times.
Indian Market Performance — 23 September 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Nifty Reclaims 23,400 as Metals Lead Broad-Based Rally
Indian equities rebounded on 23 September 2026, with gains extending well beyond the headline benchmarks.
The Nifty 50 rose 0.50% to 23,446.80, while the Sensex gained 0.40% to 74,828.25. Bank Nifty advanced 0.59%.
Unlike several recent sessions, the rebound was broad. The Nifty Next 50 gained 0.92%, Midcap 100 rose 0.70%, and Smallcap climbed 0.89%, while metals emerged as the strongest major sector.
The key takeaway was therefore not simply that Nifty reclaimed 23,400. It was that large caps, banks and broader markets participated together, while IT remained the main weak spot.
Indian Market Performance — 23 September 2026
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 23,446.80 | +0.50% |
| Sensex | 74,828.25 | +0.40% |
| Bank Nifty | 56,548.90 | +0.59% |
| Nifty Next 50 | 72,462.40 | +0.92% |
| Nifty Midcap 100 | 62,396.45 | +0.70% |
| Nifty Smallcap | 19,991.50 | +0.89% |
Sources: NSE market data | FintechEdge Research.
Why Metals Led the Rally
Metals were the standout part of Wednesday’s session.
The Nifty Metal index gained around 2.4%, with steel and aluminium names among the strongest performers. The move was significant enough to matter because it substantially outpaced the broader market.
The sector benefited from firmer pricing expectations and renewed buying in cyclical stocks. Names such as Tata Steel and Hindalco were among the notable gainers.
This was not simply a broad “risk-on” move. Metals clearly provided one of the strongest sources of leadership during the session.
Broad Market Participation Improves
The quality of Wednesday’s rebound was stronger than some of the recent benchmark-led rallies.
The Nifty Next 50 gained 0.92%, Midcap 100 rose 0.70%, and Smallcap advanced 0.89%.
That matters because all three segments participated alongside the Nifty and Bank Nifty.
Reuters also reported that Indian shares advanced as softer oil prices and financial stocks supported the market.
The useful interpretation is straightforward:
Wednesday’s rebound was broad rather than concentrated in a handful of heavyweight stocks.
That makes the move more internally convincing than a session where only the Sensex or Nifty rises while the rest of the market remains weak.
Bank Nifty Supports the Recovery
Bank Nifty gained 0.59%, helping reinforce the positive market tone.
Banks had repeatedly switched between leadership and weakness over recent sessions, so their participation today is worth noting.
There is no need to overanalyse a routine 0.59% move, but in the context of:
- strong metals;
- positive broader markets;
- and improved breadth,
banking participation helped make the rebound more balanced.
IT Remains the Weak Spot
Information technology continued to lag.
The Nifty IT index remained negative even while most of the market advanced, extending the sector’s recent underperformance.
That is becoming a recurring theme rather than a single-session anomaly.
Indian IT shares have struggled even while US technology and semiconductor stocks have shown strength, which suggests domestic investors remain more focused on company-specific demand, client spending and earnings expectations than on the global AI rally.
Since IT was already covered deeply in the previous session, today it is better treated as a persistent secondary weakness rather than the main story.
Lower Oil Continues to Support India
Brent crude remained below $100 per barrel, continuing to provide some relief to India’s macro backdrop. Market reports put Brent around $99 during Wednesday trade.
For India, lower crude can help reduce pressure on:
- inflation;
- the import bill;
- the current account;
- and the rupee.
This mechanism has already been important across several recent sessions, so it does not need a long explanation every day.
The useful point today is simply that oil remained supportive rather than becoming another headwind.
NSE IPO Listing Tomorrow
The National Stock Exchange of India is scheduled to list on the BSE on 24 September.
Its IPO was subscribed about 5.7 times, with total bids worth roughly ₹96,000 crore at the upper end of the price band.
That makes tomorrow’s listing one of the most closely watched domestic market events.
The listing itself should be treated as a separate event from today’s Nifty movement.
It would be too strong to claim the NSE IPO caused Wednesday’s rally.
The more useful interpretation is that the offering has drawn substantial institutional attention even after several volatile weeks for Indian equities.
Previous-Session FII/DII Context
The latest confirmed institutional-flow data available before Wednesday’s close was for 22 September:
- FII: -₹3,810 crore
- DII: +₹4,120 crore
These are previous-session figures, not September 23 data.
They show that heavy foreign selling continued to be offset by domestic institutional buying.
Until the September 23 figures are confirmed, it is better not to infer whether that pattern changed today.
Stocks in Focus
Tata Steel and Hindalco were among the stronger large-cap names, tracking the broader rally in metals.
Bajaj Finance also contributed to the positive tone in financials.
On the weaker side, HCL Technologies, TCS and Infosys remained under pressure as the IT sector continued to lag.
These stock moves support the main sector narrative, but they do not require separate long explanations.
What to Watch Next
NSE listing:
The biggest immediate domestic event is the NSE’s debut on the BSE on September 24.
Metals:
After a roughly 2.4% sector rally, the next question is whether buying continues or normalises.
Market breadth:
Today’s broad participation was encouraging. Continued strength outside the Nifty 50 would make the rebound more convincing.
IT:
The sector remains the main laggard and is now showing persistent relative weakness.
Crude oil:
Brent staying below $100 would remain supportive for India’s macro backdrop.
FII/DII flows:
September 23 cash-market data should be added only after confirmation.
FintechEdge View
September 23 had something several recent positive sessions lacked: broad participation.
Nifty rose 0.50%, but the more important signal was that Bank Nifty, Next 50, midcaps and smallcaps all moved higher together.
Metals provided the strongest sectoral leadership, while lower crude remained supportive and IT was the main area of weakness.
That makes Wednesday’s rebound healthier internally than a narrow large-cap rally.
However, one positive session does not establish a durable trend by itself.
The next test is whether this broader participation continues beyond a single day, especially as investors turn their attention to the NSE listing and ongoing foreign institutional flows.
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.