Indian Stock Market Today: Nifty Rises 1.05% After Fed Holds Rates
Quick Summary
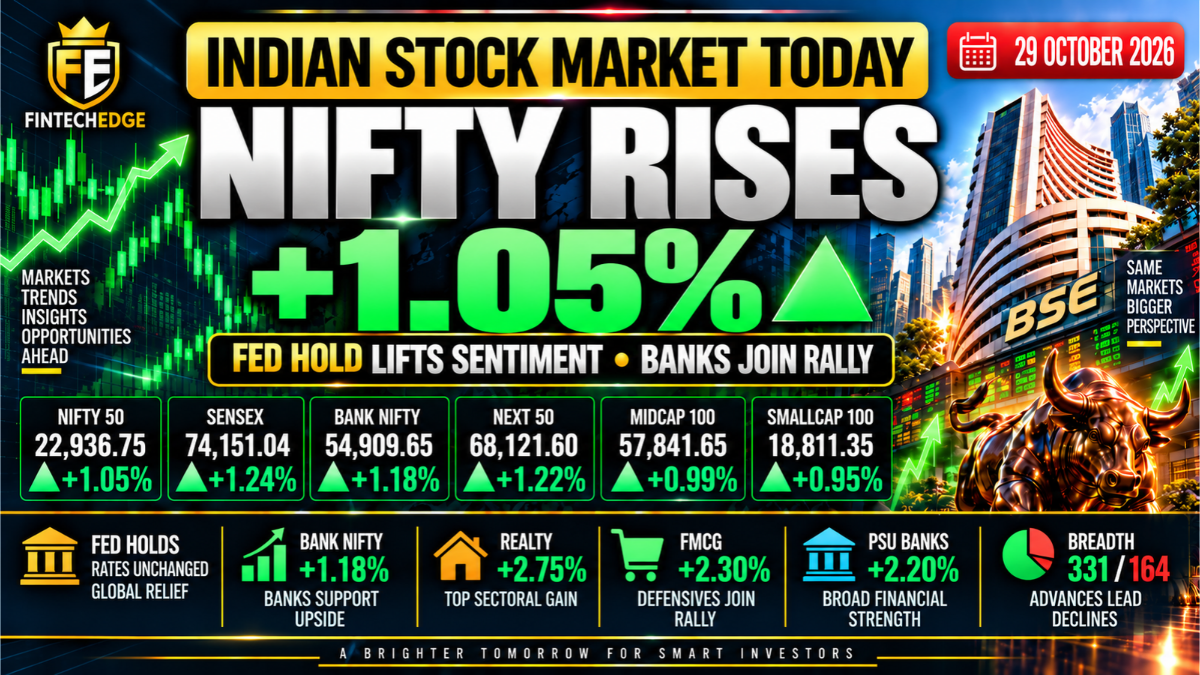
- Nifty 50 rose 1.05% to 22,936.75, while Sensex gained 1.24% to 74,151.04.
- The rebound was broad-based, with Bank Nifty up 1.18%, Next 50 up 1.22%, Midcap 100 up 0.99%, and Smallcap 100 up 0.95%.
- The Federal Reserve kept US interest rates unchanged, removing one immediate source of global policy uncertainty.
- Positive earnings supported stocks including Adani Ports, Adani Enterprises and Hindustan Unilever.
- Brent crude eased to around $114.40 per barrel, while the rupee ended broadly stable near ₹95.26 per dollar.
- India’s 10-year benchmark bond yield eased to around 7.35%.
- Most major sectors finished higher, making the rally more balanced than several recent sessions.
Indian Market Performance — 29 October 2026
Daily change in key Indian equity indices
Indian Stock Market Today: Closing Summary
Indian stock market today rebounded strongly on 29 October 2026, with the Nifty 50 rising 1.05% to 22,936.75 and the Sensex gaining 1.24% to 74,151.04 after the Federal Reserve kept US interest rates unchanged.
Unlike several recent sessions, the recovery was broad. Bank Nifty gained 1.18%, the Nifty Next 50 rose 1.22%, the Midcap 100 advanced 0.99%, and the Smallcap 100 added 0.95%. All six major indices tracked by FintechEdge finished higher.
The Fed decision removed one immediate source of global uncertainty, while positive earnings reactions, softer crude oil and easing Indian bond yields provided additional support. The rebound was also stronger internally than some of the recent index-led rallies because banks, smaller companies and most major sectors participated together.
| Index | Close | Change |
|---|---|---|
| Nifty 50 | 22,936.75 | +1.05% |
| Sensex | 74,151.04 | +1.24% |
| Bank Nifty | 54,909.65 | +1.18% |
| Nifty Next 50 | 68,121.60 | +1.22% |
| Nifty Midcap 100 | 57,841.65 | +0.99% |
| Nifty Smallcap 100 | 18,811.35 | +0.95% |
The most important feature of the session was the consistency of the gains.
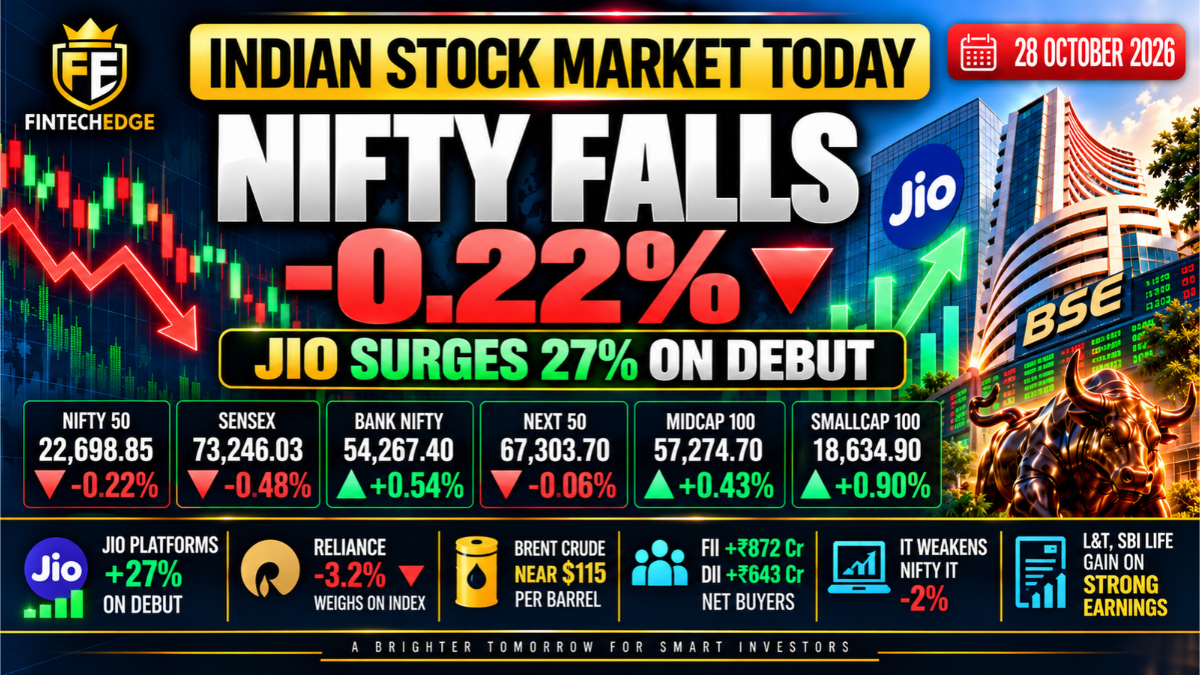
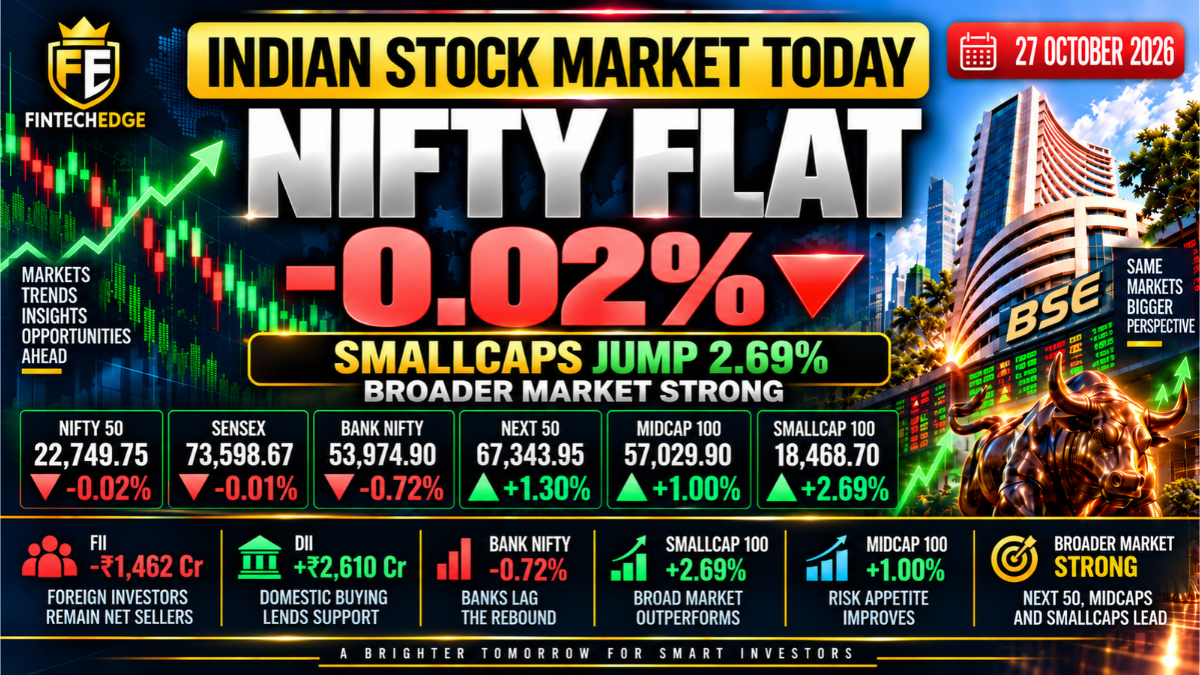
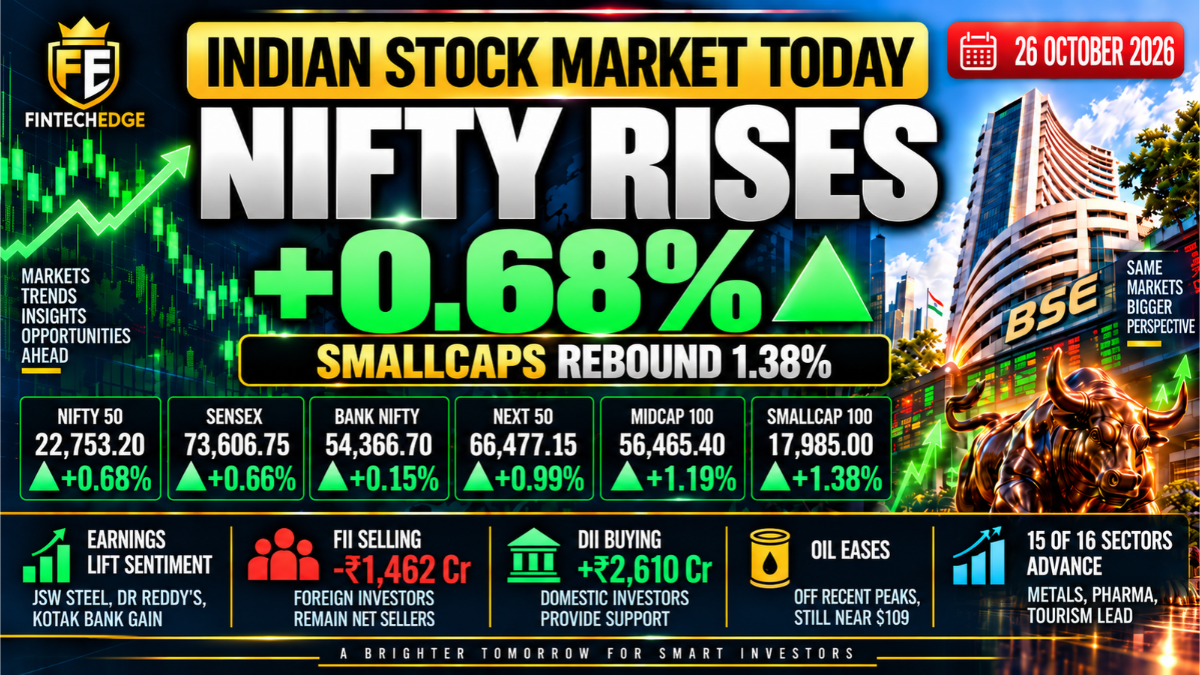
All six indices rose by roughly 0.95%–1.24%. That is very different from 28 October, when the Nifty and Sensex fell even as Bank Nifty, midcaps and smallcaps remained positive.
Today, large caps and the broader market moved in the same direction.
Fed Holds Rates and Removes Immediate Uncertainty
The Federal Reserve was the main global catalyst.
The Fed kept US interest rates unchanged, a decision markets had largely expected.
That matters for Indian markets because investors had spent several sessions worrying about whether another US rate increase could push global yields higher, strengthen the dollar and increase pressure on emerging-market assets.
The decision therefore removed one immediate uncertainty.
But it would be a mistake to interpret the outcome as a major dovish shift.
Inflation risks remain, and future policy will still depend on incoming economic data. The US yield curve also remained sensitive after the meeting, showing that bond investors are still evaluating the possibility that rates may need to stay restrictive.
For Indian investors, the practical takeaway is narrower:
The Fed pause reduced immediate tightening fears, but the future path of US rates remains important for yields, currencies and foreign capital flows.
Broad Rally Across Large Caps and Smaller Stocks
The strength of the session was not confined to a handful of heavyweight companies.
The Nifty rose 1.05%, Sensex gained 1.24%, Bank Nifty advanced 1.18%, Next 50 rose 1.22%, Midcap 100 gained 0.99%, and Smallcap 100 added 0.95%.
That is significant after the market’s recent volatility.
During the sell-off between 21 and 23 October, smallcaps and midcaps fell much faster than the headline benchmarks. They began recovering on 26 October and strengthened further over the following sessions.
Today’s move was different again: the recovery became more balanced.
Large caps, banks and smaller companies all participated.
That does not establish a new uptrend by itself, but it does improve the quality of the session compared with rallies driven by only one or two pockets of the market.
Bank Nifty Rises 1.18%
Banks rejoined the recovery.
Bank Nifty gained 1.18%, slightly outperforming the Nifty’s 1.05% rise.
This matters because financials carry substantial weight in the headline indices.
Banks had lagged several previous rebound sessions. On 27 October, for example, Bank Nifty fell 0.72% even while smallcaps surged 2.69%.
The latest session therefore showed a healthier internal balance.
When banks, the broader market and large-cap benchmarks rise together, the rally is less dependent on a narrow group of stocks.
Still, one strong day does not establish a lasting sector trend.
Earnings Support Adani Ports, Adani Enterprises and HUL
Corporate results provided another layer of support.
Adani Ports rose around 6.3%, Adani Enterprises gained about 5.2%, and Hindustan Unilever advanced roughly 2.3% following positive earnings reactions. Power Grid and NTPC also posted strong gains.
This is important because it means the rebound was not driven only by the Fed.
Company-specific fundamentals also mattered.
That improves the quality of market participation.
A rally based entirely on a global macro event can reverse quickly when the external narrative changes. Earnings-driven gains, by contrast, reflect information specific to individual companies.
That does not mean the entire earnings season is strong, but it does mean investors had more than one reason to buy today.
Oil Eases to Around $114.40
Crude oil moved lower, providing some relief.
Brent fell about 0.8% to around $114.40 per barrel.
For India, even a modest decline in crude can help sentiment because high oil affects several parts of the economy:
- imported inflation;
- the trade balance;
- the current account;
- corporate margins;
- the rupee;
- and interest-rate expectations.
But the level still matters.
Oil above $114 remains historically elevated and continues to represent a macro risk.
So today’s move should be described as some relief from oil pressure, not the disappearance of the oil problem.
Most Sectors Finish Higher
Sector participation was strong.
Fifteen of the 16 major sectors advanced, with financials gaining around 1.2% and IT rising about 1%.
That is one of the clearest signs that today’s rebound was broad.
It contrasts sharply with the sessions earlier in October when most sectors were simultaneously falling.
Sector breadth matters because it helps distinguish between a genuine market-wide recovery and a benchmark gain produced by a small number of heavyweight stocks.
Today was much closer to the former.
That said, one sector still finished lower, so it would be inaccurate to describe the session as universally positive.
Broader Market Participates Instead of Lagging
Another constructive feature was that midcaps and smallcaps did not trail the benchmarks materially.
The Midcap 100 gained 0.99%, while the Smallcap 100 rose 0.95%.
That matters after the severe weakness seen earlier in the month.
On 23 October, the Smallcap 100 dropped 2.94% while the Nifty lost only 0.39%.
Today there was no such divergence.
The gains across market-cap segments were relatively close together.
For market breadth, that is a healthier configuration.
Rupee Ends Near ₹95.26
The rupee recovered from intraday weakness and finished broadly stable near ₹95.26 per dollar.
Softer crude helped reduce some pressure, while likely RBI support limited the downside.
The currency remains important because the combination of high crude and elevated global yields has been one of the main external challenges for Indian assets in recent weeks.
A stable rupee therefore contributes to a more supportive backdrop, but the underlying risks remain.
If oil rises sharply again or US yields move higher, pressure on the currency could return.
Indian Bond Yields Ease
The bond market also delivered some relief.
India’s 10-year benchmark government bond yield fell about 8 basis points to 7.35%.
This matters beyond the bond market itself.
Higher yields can:
- increase corporate borrowing costs;
- tighten financial conditions;
- pressure valuation multiples;
- and affect rate-sensitive sectors.
The recent rise in yields had therefore become an important equity-market concern.
Today’s decline eased some of that pressure.
But, as with crude oil, one session does not establish a lasting trend.
Why Today’s Rally Was Better Balanced
Recent Indian market sessions have frequently featured large internal divergences.
Sometimes the Nifty was relatively stable while smallcaps collapsed.
On other days, smallcaps rallied while banks and heavyweight stocks held the benchmarks back.
Today was different.
All six major indices tracked by FintechEdge finished higher:
Nifty 50: +1.05%
Sensex: +1.24%
Bank Nifty: +1.18%
Next 50: +1.22%
Midcap 100: +0.99%
Smallcap 100: +0.95%
That consistency makes the session more meaningful than a headline-index rally alone.
It still does not prove that the recent correction has ended.
But from a market-structure perspective, broader participation is an improvement.
What to Watch Next
Fed guidance and US inflation
The rate pause removed immediate uncertainty, but the next direction will depend heavily on inflation and future Fed communication.
Brent crude
Oil remains above $114. A renewed spike would quickly return inflation and currency concerns to the forefront.
Broad-market participation
Banks, midcaps and smallcaps all participated today. Whether that continues will be more important than a single strong close.
Earnings
Company results continue to create large stock-specific moves. Upcoming results could determine whether earnings remain a meaningful domestic support.
Indian bond yields
The 10-year yield eased to around 7.35%. Whether yields continue falling will matter for financial conditions.
FII and DII flows
Fresh 29 October daily stock-segment figures were not available, so no FII/DII numbers should be carried forward from earlier sessions.
FintechEdge View
The Indian stock market today produced one of the more balanced rebound sessions of the recent period.
The Fed’s decision to hold rates steady removed one immediate macro uncertainty, but the strength of the session went beyond that single event.
Banks participated, midcaps and smallcaps rose alongside the benchmarks, most sectors finished higher, and positive earnings gave individual stocks additional support.
Softer crude, a stable rupee and lower Indian bond yields also helped improve the backdrop.
There are still reasons to remain measured. Brent crude remains above $114, US inflation risks have not disappeared, and the benchmarks are recovering only part of their recent losses.
The most important takeaway is therefore not simply that the Nifty rose 1.05%.
It is that the rebound was broad enough to include large caps, banks, smaller companies and nearly every major sector at the same time.
Whether that breadth continues will be more important than today’s percentage gain alone.
Sources & References
- Indian shares rebound after Fed holds rates steady — Reuters
- Federal Reserve policy decision and global bond-market reaction — Reuters
- Corporate earnings and sector performance — Reuters
- Brent crude, rupee and Indian bond-market movements — Reuters
- Nifty 50 and broader index closing data — NSE India
This article is for educational and informational purposes only and does not constitute investment advice, trading advice or a recommendation to buy or sell any security.
Our content is written for educational purposes and focuses on clarity, evidence, risk awareness and practical decision-making.